Insights

Notes on the IC market

Practical observations on supply, sourcing, and the IC trading landscape.

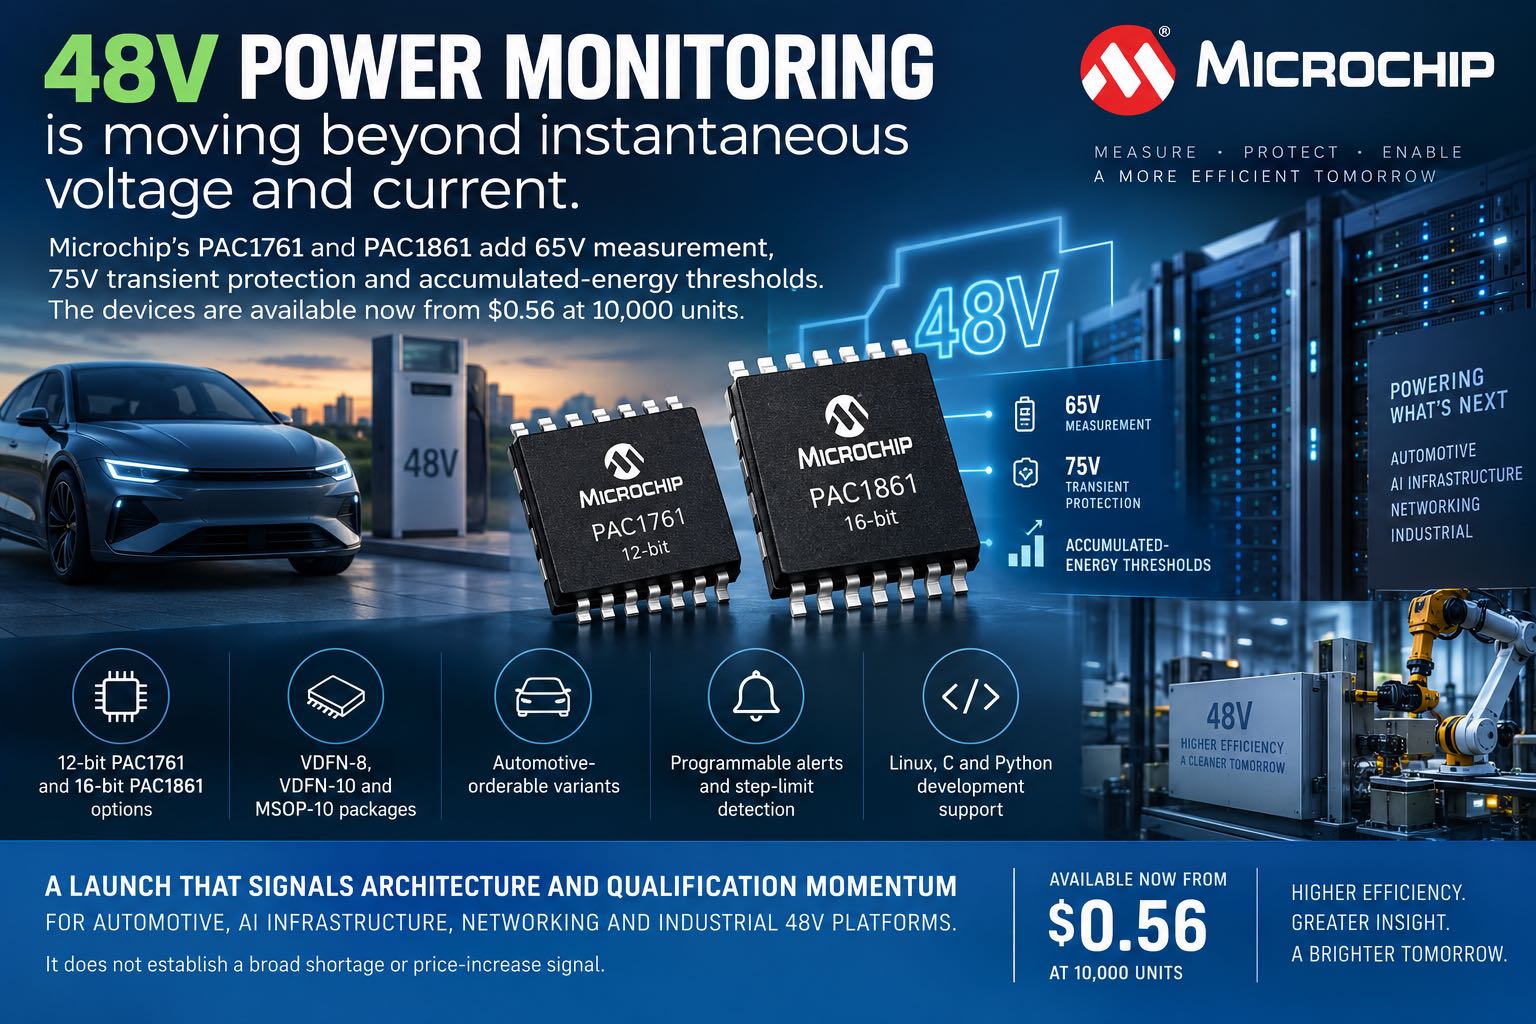
Microchip PAC1761 and PAC1861 Add 65V Headroom and Accumulated-Energy Monitoring to 48V Systems

September 25, 2026

Microchip PAC1761 and PAC1861 Add 65V Headroom and Accumulated-Energy Monitoring to 48V Systems

Microchip has introduced the PAC1761 and PAC1861 digital power-monitor families for 48V architectures. The devices combine 65V measurement, 75V transient protection and accumulated-energy data. The launch broadens the qualification checklist for automotive, AI infrastructure, networking and industrial power systems without establishing a shortage signal.

marketprocurementindustrialsupply-chain
Read more →
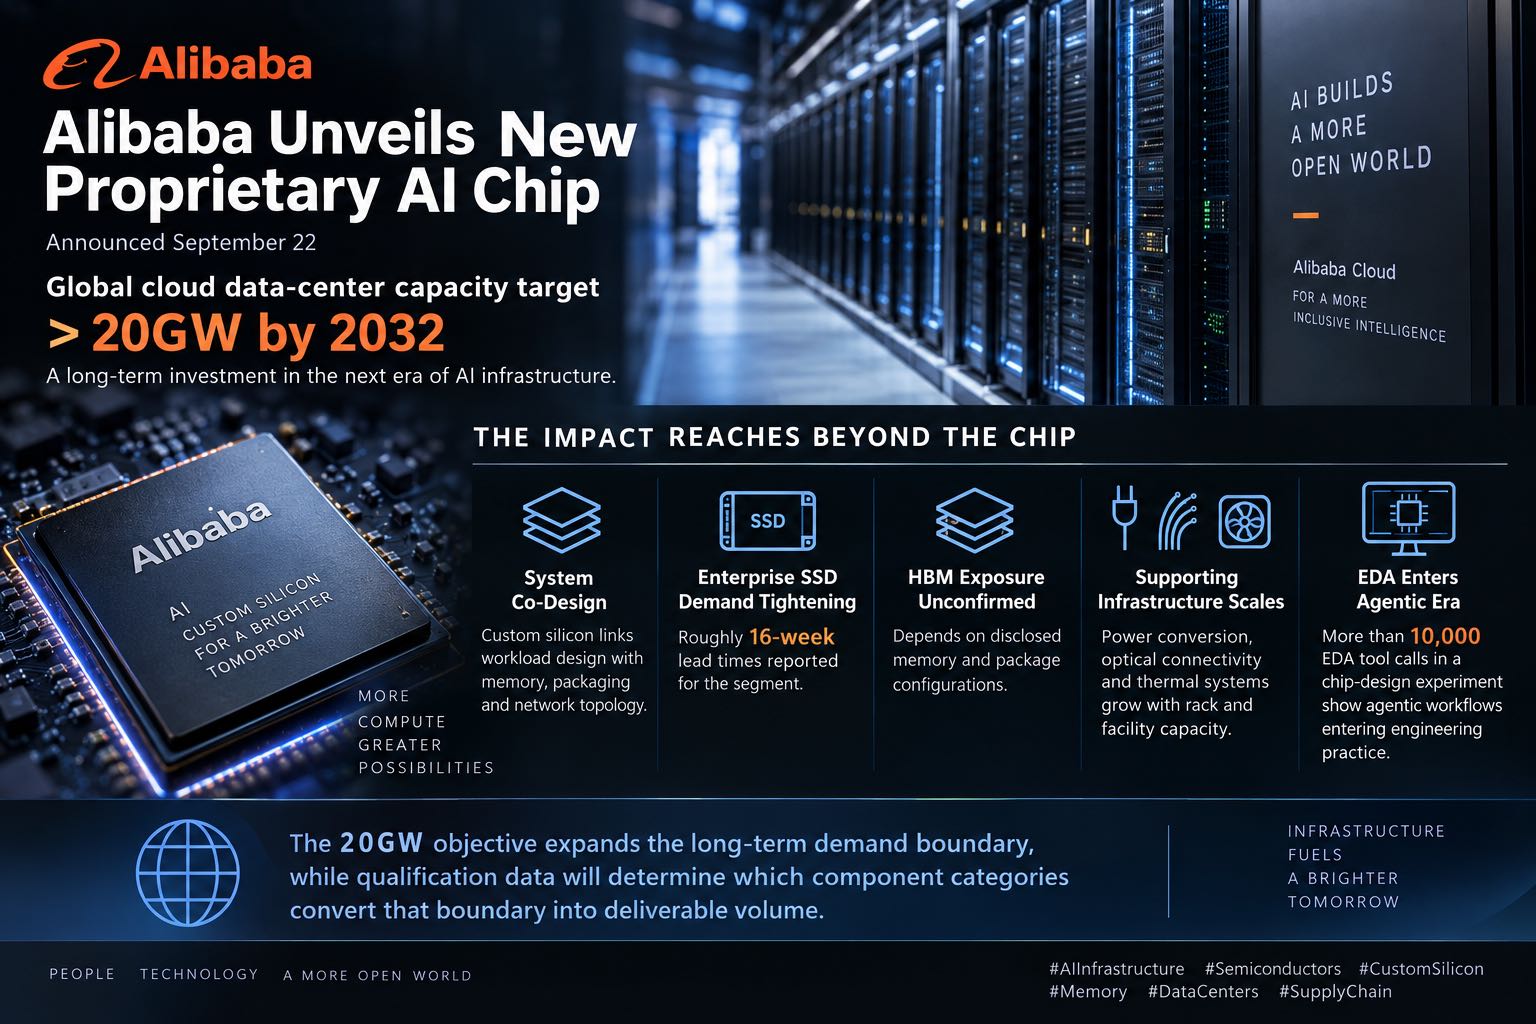
Alibaba Links a New Custom AI Chip to a 20GW Cloud Infrastructure Roadmap Through 2032

September 23, 2026

Alibaba Links a New Custom AI Chip to a 20GW Cloud Infrastructure Roadmap Through 2032

Alibaba announced a new proprietary AI chip on September 22, 2026 and set a target of more than 20GW of global cloud data-center capacity by 2032. The roadmap combines silicon, models, agentic cloud services and physical infrastructure. Process technology, HBM configuration, packaging and production partners remain undisclosed, so strategic demand should be separated from qualified component demand.

marketai-demandprocurementsupply-chain
Read more →
CoWoS-L Moves Beyond Reticle Limits as AI Chips Add More Compute Dies and HBM Stacks

September 21, 2026

CoWoS-L Moves Beyond Reticle Limits as AI Chips Add More Compute Dies and HBM Stacks

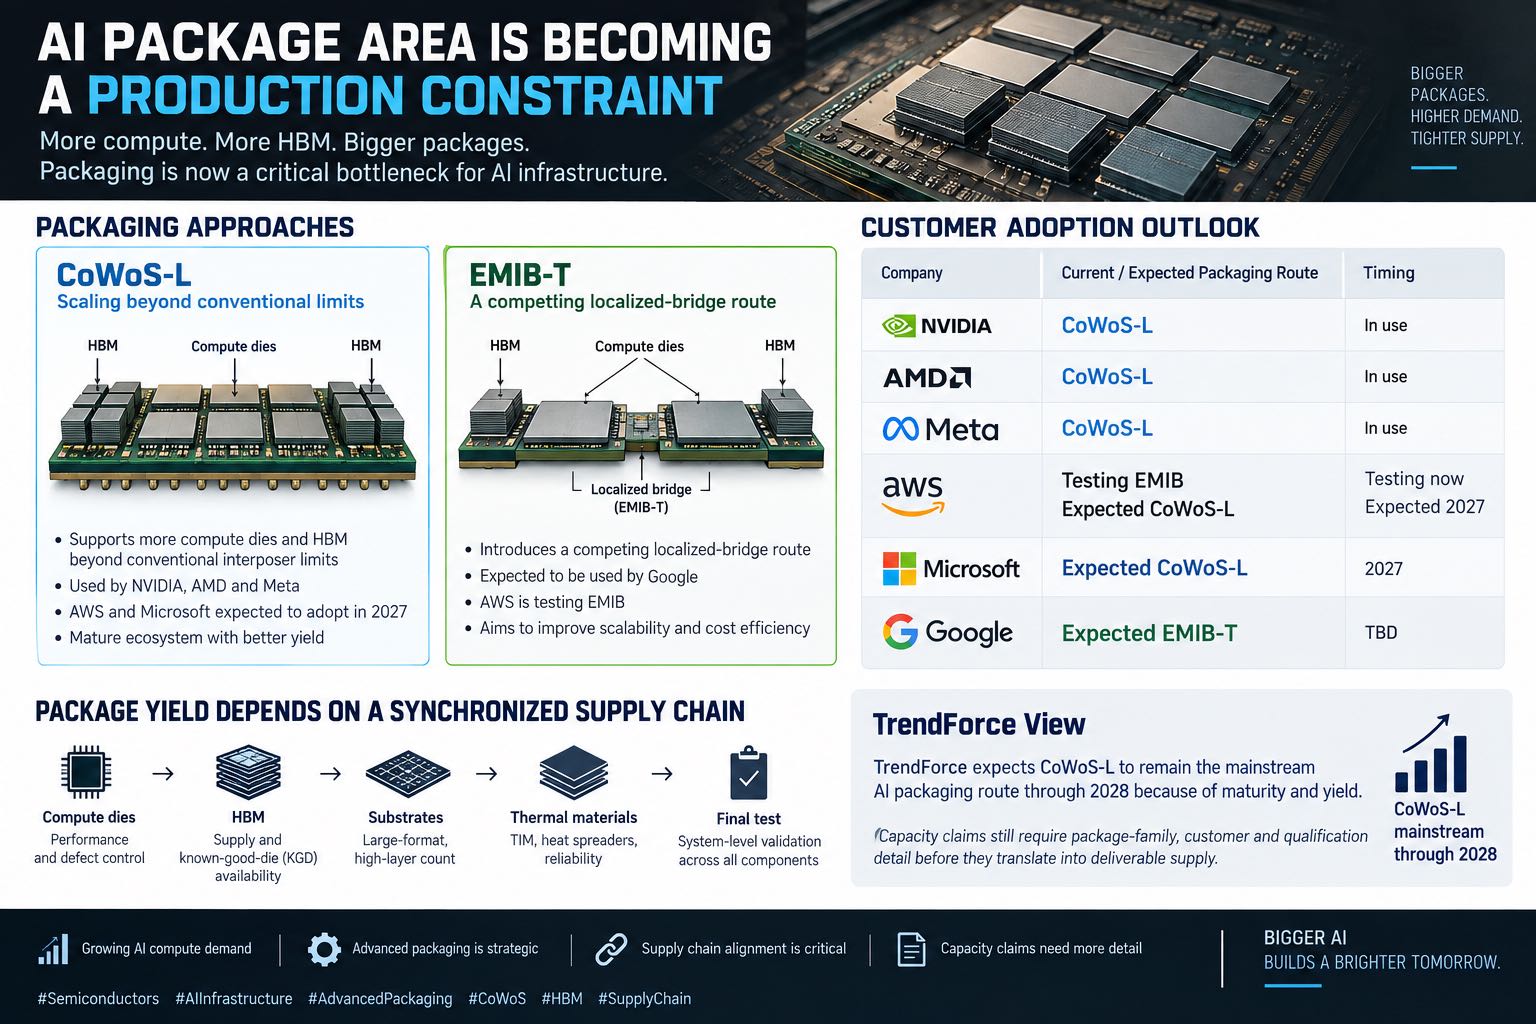
TrendForce said on September 18, 2026 that larger AI packages are pushing conventional silicon interposers toward physical limits. CoWoS-L uses localized silicon bridges to support more compute dies and HBM, while Intel EMIB-T offers a competing bridge-based route. The commercial constraint now spans architecture, substrate routing, yield, thermal design and platform qualification.

marketai-demandprocurementsupply-risk
Read more →
Qualcomm and Amazon Pair Multi-Generation Custom AI Inference Silicon With 1.6T Optical Connectivity

September 9, 2026

Qualcomm and Amazon Pair Multi-Generation Custom AI Inference Silicon With 1.6T Optical Connectivity

Qualcomm and Amazon will co-develop multiple generations of customized silicon for AWS AI inference. The program also includes optical connectivity up to 1.6T and future generations. Product specifications, qualification dates and deployment volumes remain undisclosed, so the announcement is a long-term architecture signal rather than a near-term procurement forecast.

ai-demandprocurementsupply-chain
Read more →
Samsung Targets 2× HBM4E Performance With HBM5 as zHBM Pushes Stacking, Thermal and Test Validation Into a New Cycle

September 2, 2026

Samsung Targets 2× HBM4E Performance With HBM5 as zHBM Pushes Stacking, Thermal and Test Validation Into a New Cycle

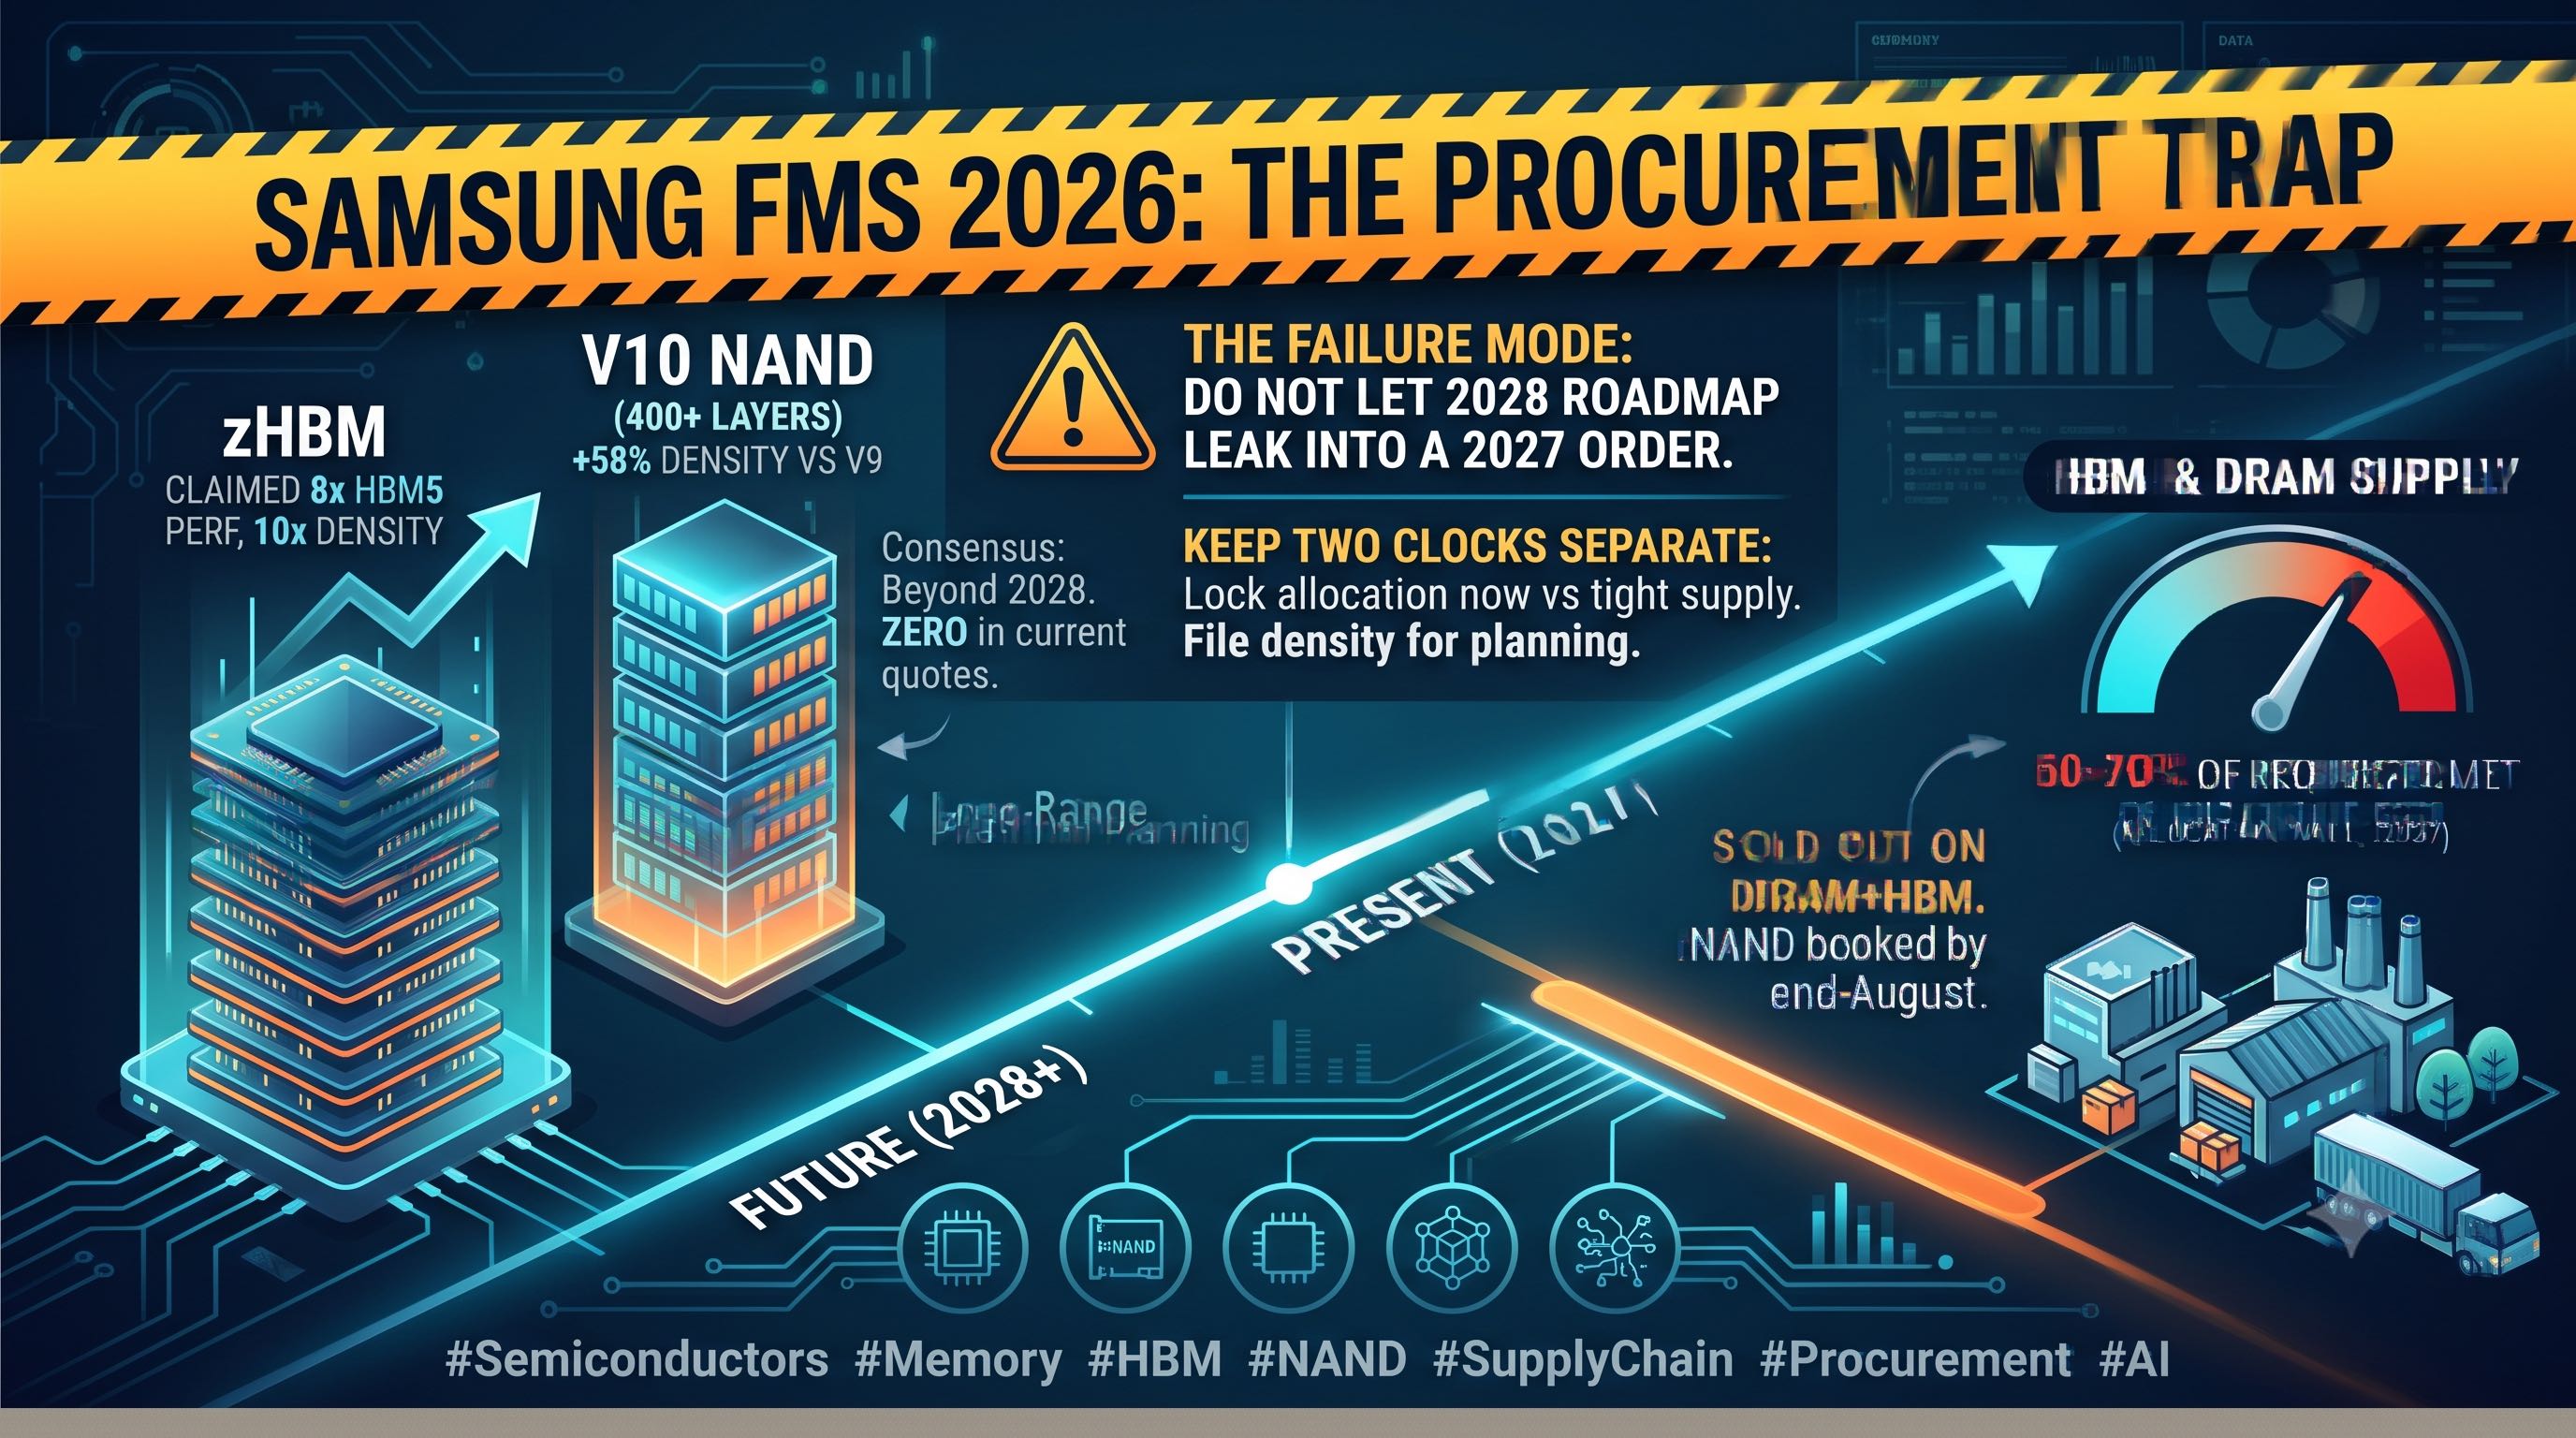
Samsung disclosed new HBM5 and zHBM roadmap targets at SEMICON Taiwan on September 1, 2026. HBM5 targets roughly twice HBM4E performance, while zHBM aims for another eightfold step over HBM5. These are roadmap objectives, not qualified production specifications, so supply conclusions still depend on yield, packaging throughput, thermal validation and platform certification.

memoryai-demandprocurementsamsung
Read more →
Diodes Acquires ElevATE for $250 Million as ATE Analog ICs Become a Portfolio Expansion Target

August 31, 2026

Diodes Acquires ElevATE for $250 Million as ATE Analog ICs Become a Portfolio Expansion Target

Diodes has completed its all-cash acquisition of ElevATE Semiconductor for $250 million. ElevATE is expected to contribute about $50 million of revenue in the first twelve months and will remain a product line inside Diodes. The transaction expands exposure to high-performance analog and mixed-signal ICs used in automated test equipment, with no EOL or channel change disclosed at closing.

marketprocurementsupply-chain
Read more →
The MATCH Act Extends China Controls From Equipment Sales to Servicing, Putting Mature-Node Installed Base at Risk

August 26, 2026

The MATCH Act Extends China Controls From Equipment Sales to Servicing, Putting Mature-Node Installed Base at Risk

The MATCH Act is being pushed toward the Senate NDAA. Beyond banning DUV immersion lithography and cryogenic etch exports to China, it would bar ASML from servicing tools already installed there. A sales ban constrains future capacity; a servicing ban degrades installed-base uptime. China's mature nodes produce general-purpose MCUs, analog, power discretes, NOR and DDR4, the same categories buyers have been shifting to in order to escape Western repricing and 52-week lead times.

marketprocurementsupply-risksupply-chain
Read more →
STMicroelectronics' Third 2026 Price Increase Took Effect August 23 as Power Device Lead Times Reach 52 Weeks

August 24, 2026

STMicroelectronics' Third 2026 Price Increase Took Effect August 23 as Power Device Lead Times Reach 52 Weeks

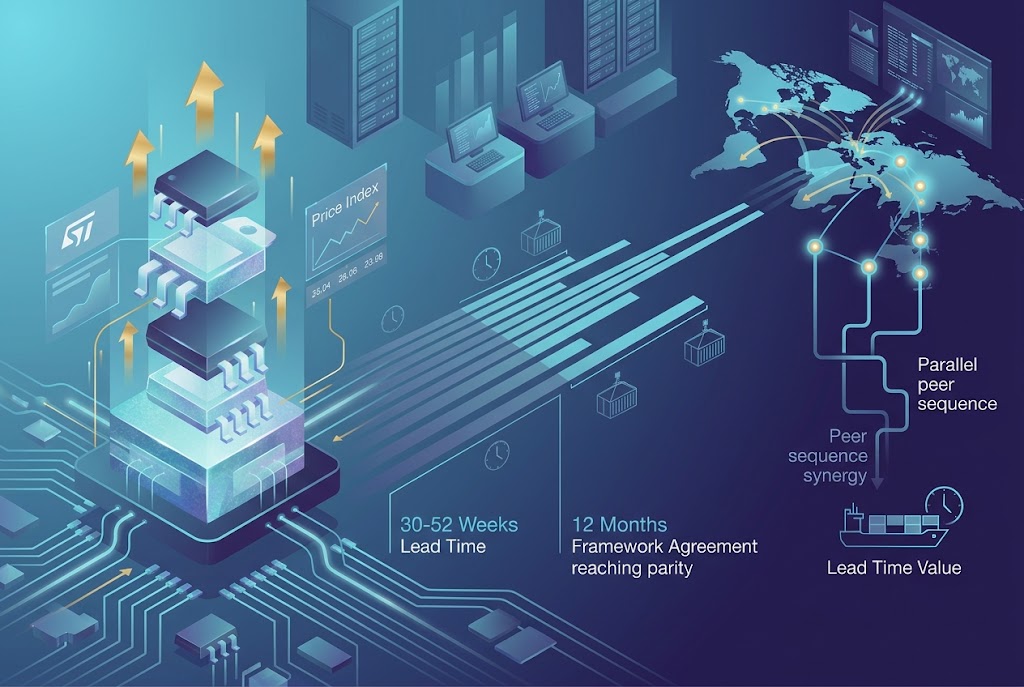
STMicroelectronics' third price increase of 2026 took effect on August 23, covering power ICs, general-purpose MCUs, NFC RF chips and power semiconductors, with automotive MCUs up a cumulative 15–20%. Power device lead times generally exceed 30 weeks and reach 52 weeks on some parts. Placed alongside TI's five adjustments in twelve months, NXP's 5–15% effective August 1 and Infineon's 10–20% in July, analog and power repricing has moved from individual supplier action to a category-wide pattern. This piece breaks down the cadence of the three rounds, the mutual reinforcement between lead times and pricing, and what remains verifiable on the secondary channel side.

marketprocurementindustrialsupply-risk
Read more →
AI Racks Hit a Thermal Ceiling: How 1kW-Plus TDP Reshapes Data-Center Part Structure in 2026

August 21, 2026

AI Racks Hit a Thermal Ceiling: How 1kW-Plus TDP Reshapes Data-Center Part Structure in 2026

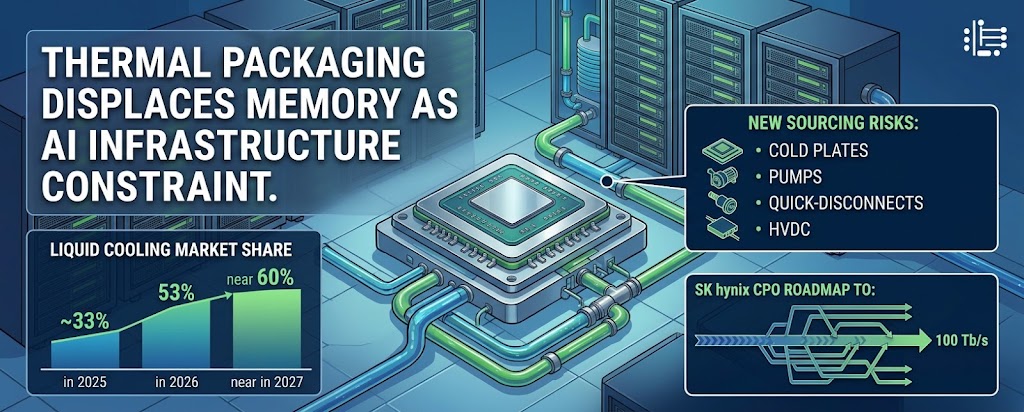
Individual AI processors from NVIDIA, AMD and Google have crossed 1kW TDP, and rack-scale systems now draw hundreds of kilowatts. Researchers at KAIST and Seoul National University this week placed packaging thermals ahead of further performance gains as the primary bottleneck on AI infrastructure expansion. Liquid cooling penetration moves from roughly 33% in 2025 to 53% in 2026 and near 60% in 2027. For secondary-channel and industrial OEM sourcing, the consequence sits in cold plates, pumps, quick-disconnects and high-voltage DC power components rather than in compute silicon.

ai-demandsupply-chainmarketsupply-risk
Read more →
NAND Supplier Revenue Jumped 77% in Q2 2026 — The Price Increase Is Already Booked as Profit

August 19, 2026

NAND Supplier Revenue Jumped 77% in Q2 2026 — The Price Increase Is Already Booked as Profit

Combined Q2 2026 revenue at the five largest NAND Flash brands reached US$68.87bn, up 77% quarter-on-quarter, with Micron rising 99.2% into third place and SK hynix Group posting a record operating margin. The growth was ASP-driven rather than bit-driven, which matters more than the headline number. For channel buyers and spot traders, this is harder evidence than any supply-demand forecast: suppliers have converted the price cycle into booked profit, and the commercial case for loosening in Q4 has effectively disappeared. At the same time, YMTC's 8-plane QLC reached retail shelves, giving the domestic second-source conversation its first real quotable data point.

marketmemoryai-demandprocurement
Read more →
SK Hynix Just Opened a Labor Front at the World's #1 HBM Maker — What Spot Buyers Should Actually Track

August 17, 2026

SK Hynix Just Opened a Labor Front at the World's #1 HBM Maker — What Spot Buyers Should Actually Track

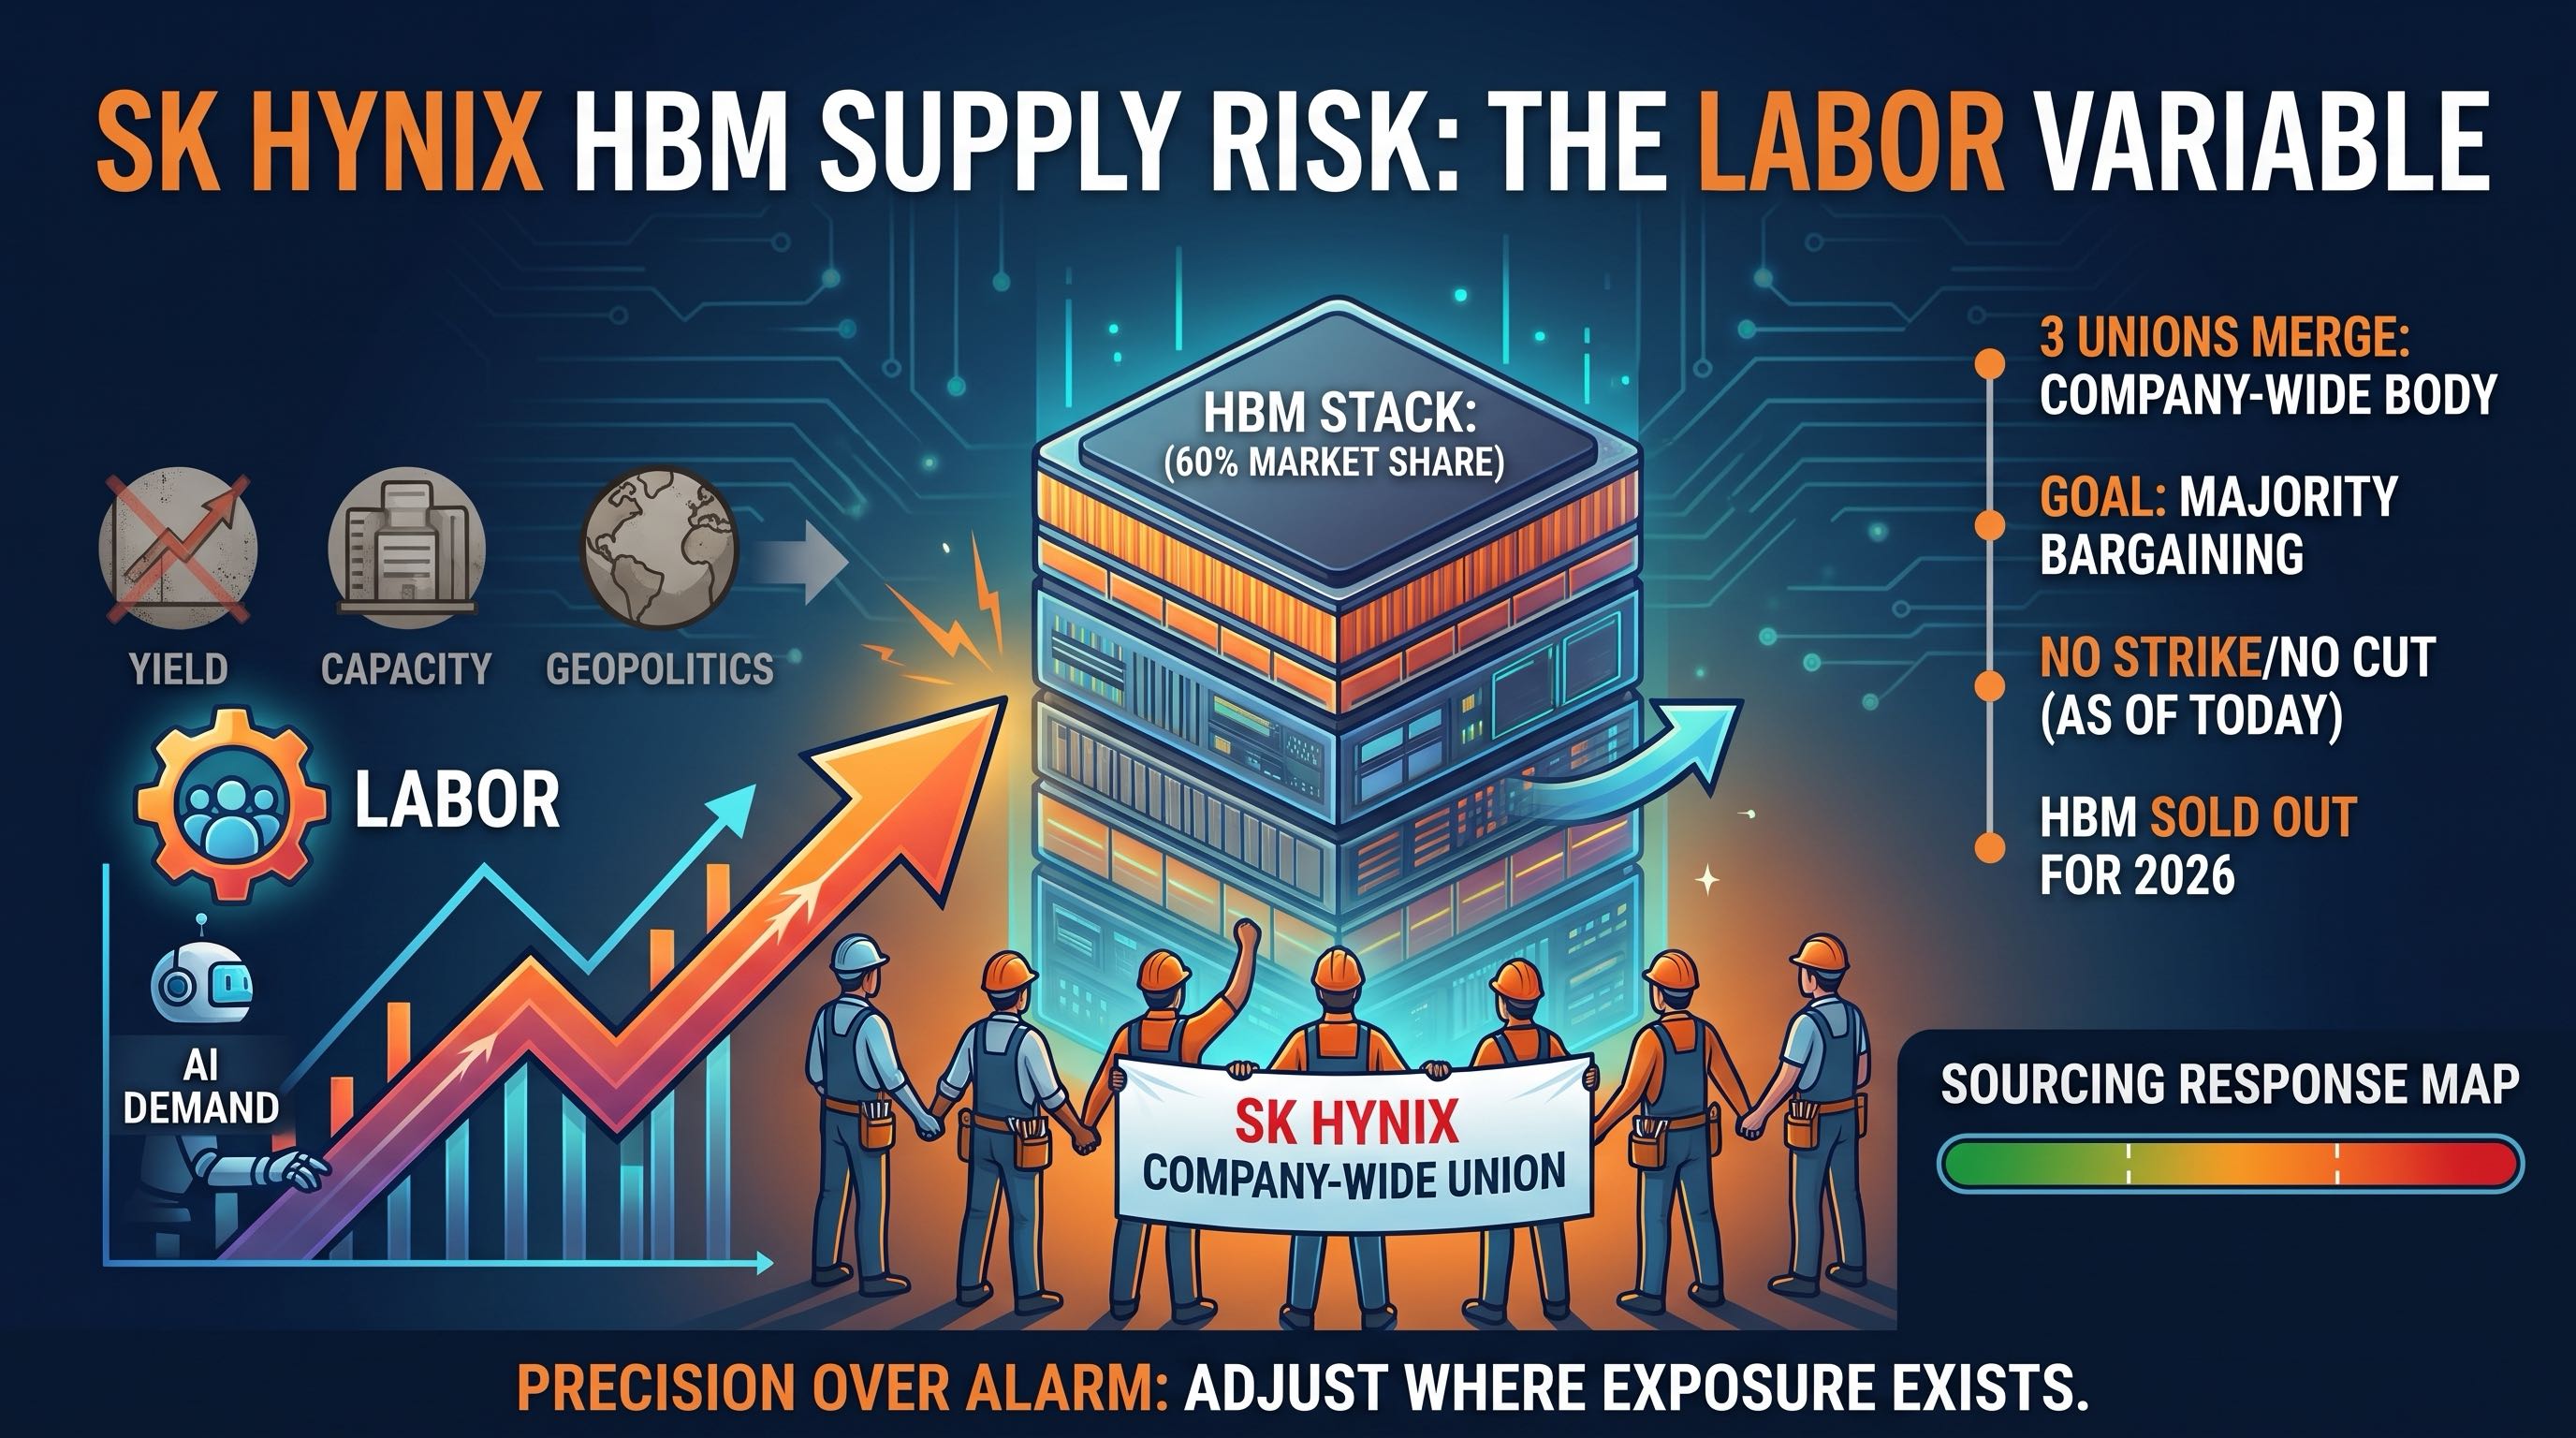
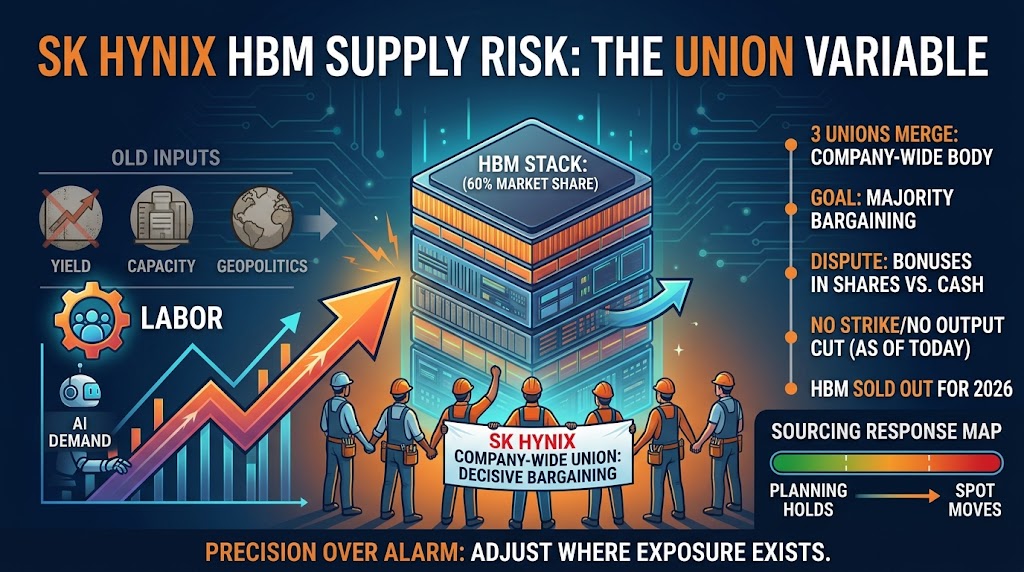
On August 13, SK Hynix's Korean workers merged three fragmented unions into a single company-wide body, with wage talks stuck on one thing: management wants to pay bonuses in shares instead of cash. No strike yet — but it's the first time the world's largest HBM maker has opened a labor front at the tightest point of the allocation cycle. This isn't equity noise; it's a real supply-side tail variable. Here's how spot buyers should read it, what to watch, and when to move.

memorysupply-riskai-demandsupply-chain
Read more →
After AI Drained the Memory Pool: The Mobile DRAM Squeeze Is Killing the Cheap Phone — What Spot Buyers Should Actually Track

August 14, 2026

After AI Drained the Memory Pool: The Mobile DRAM Squeeze Is Killing the Cheap Phone — What Spot Buyers Should Actually Track

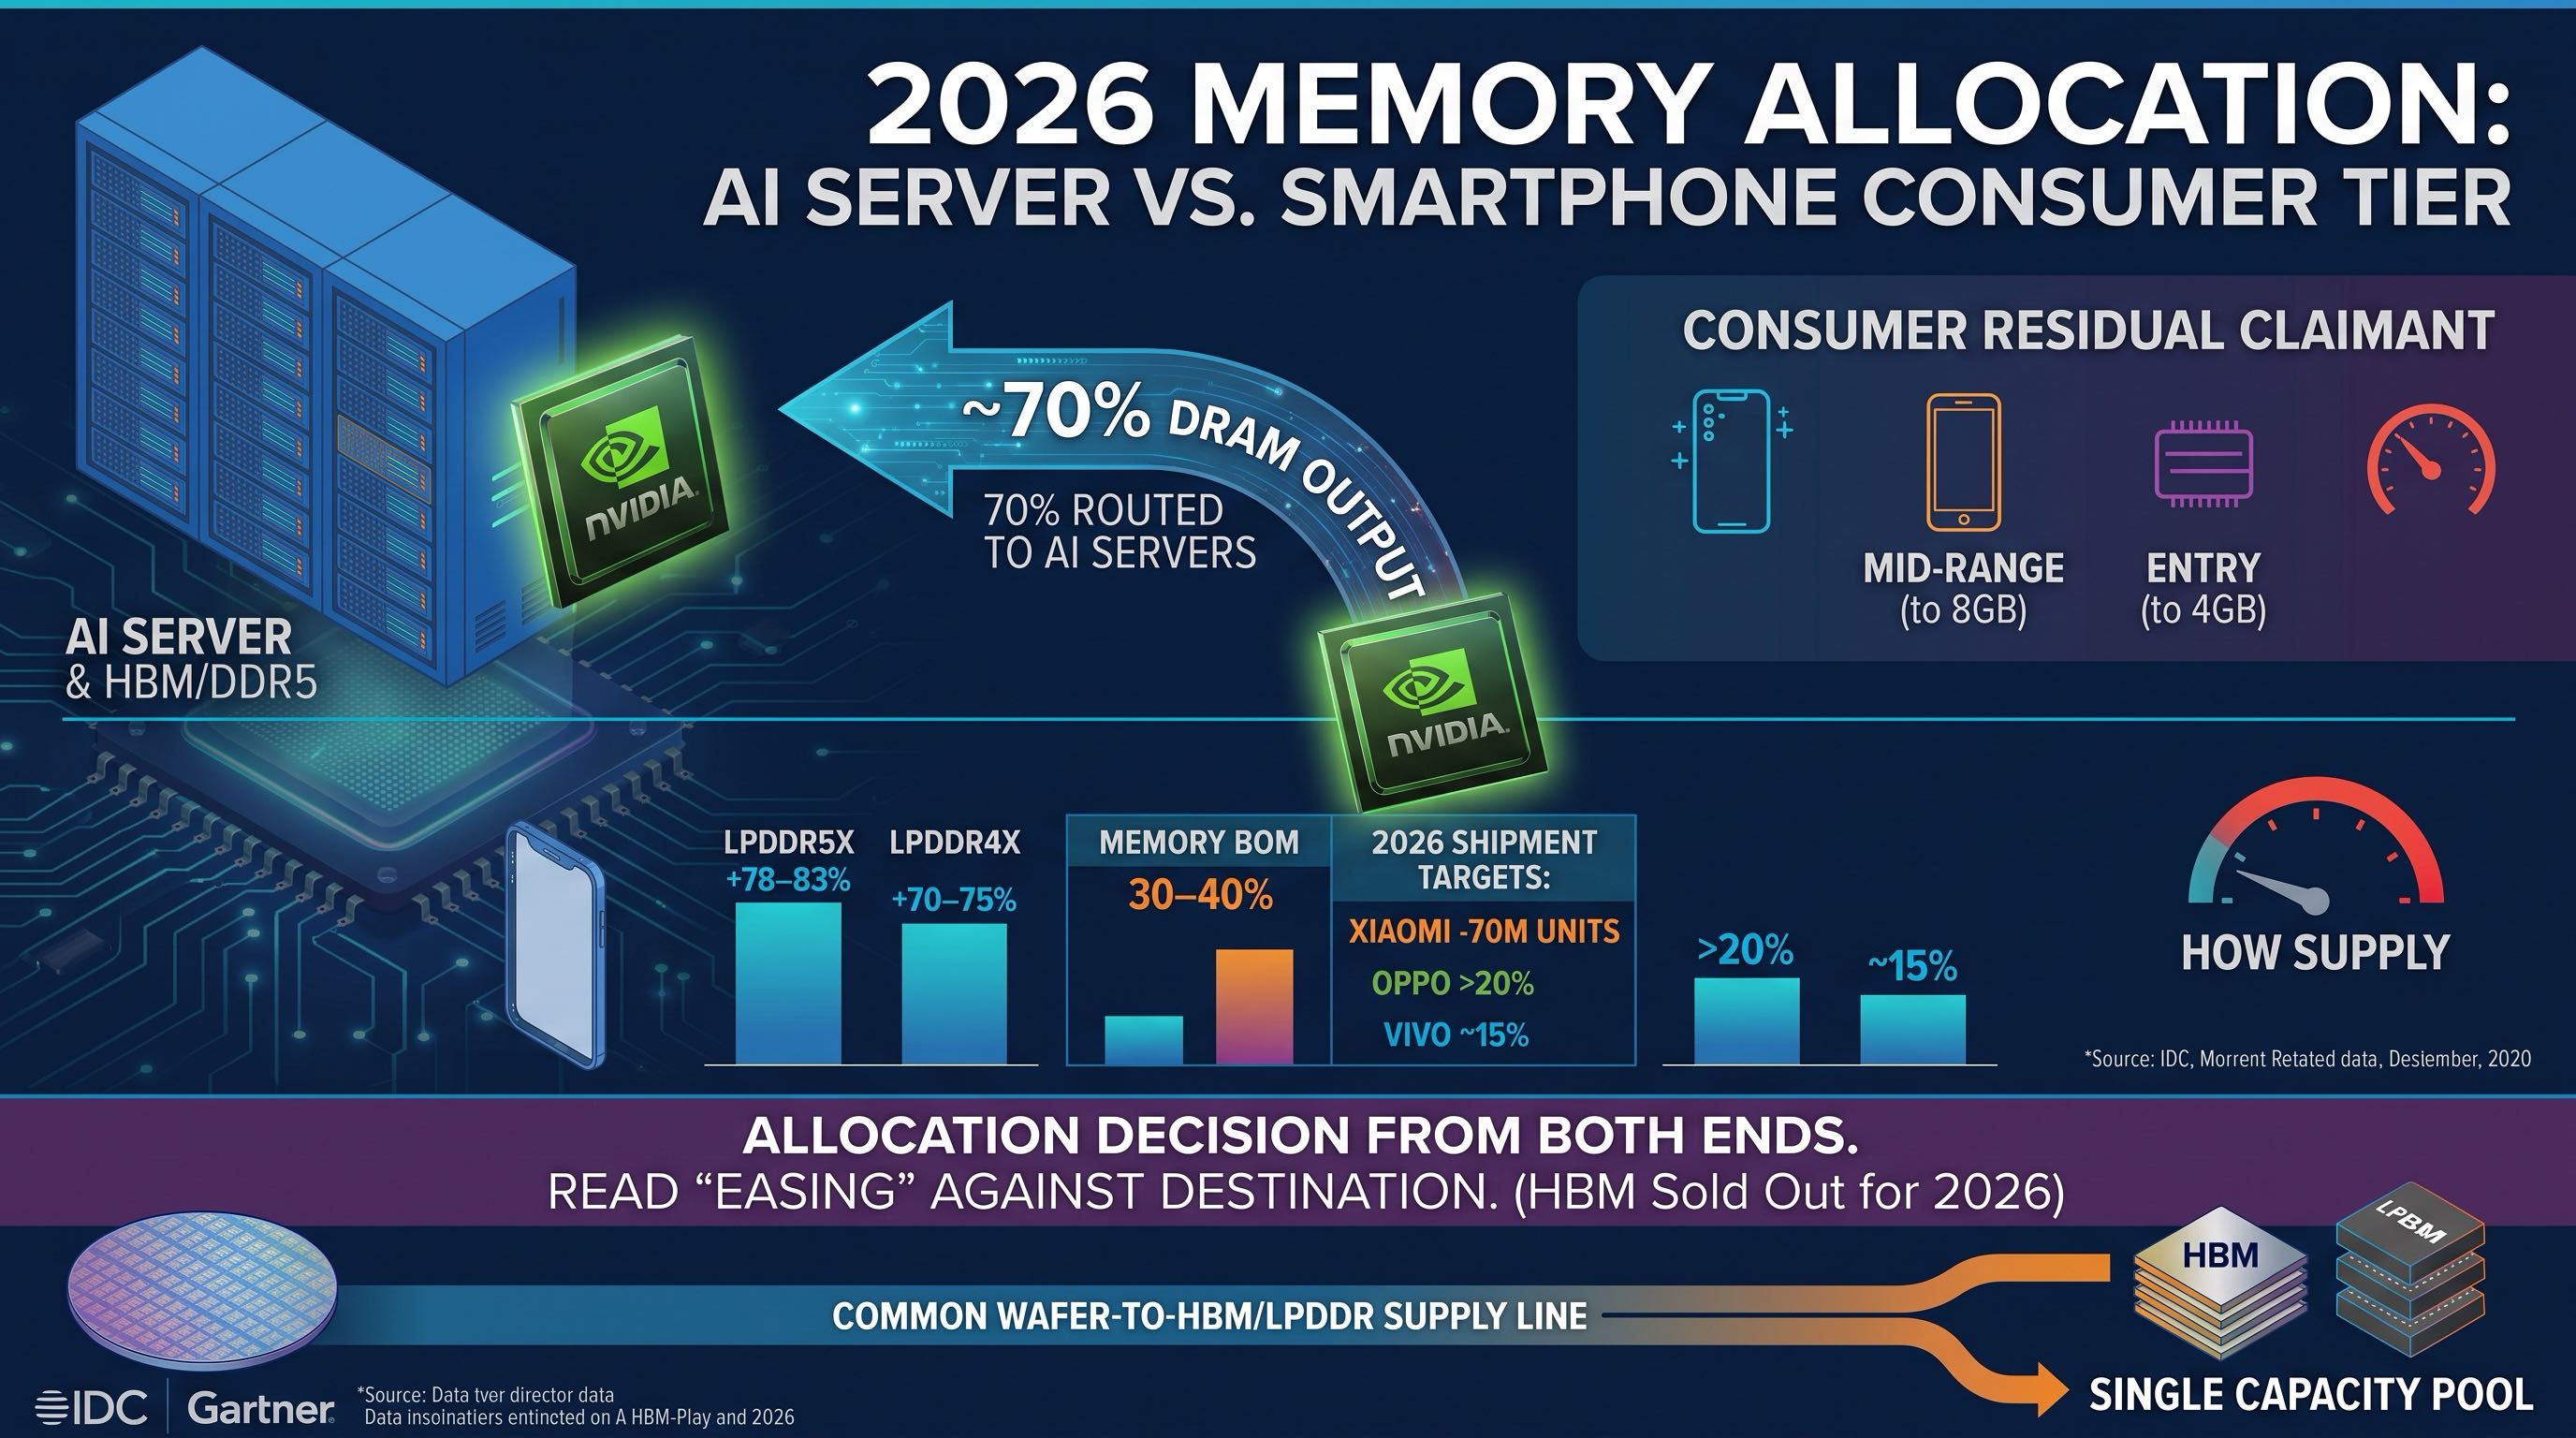
The big three redirected roughly 70% of DRAM output to AI servers, LPDDR5X jumped nearly 80% in a single quarter, and phone makers are cutting orders, downgrading specs, and letting the entry tier collapse. This isn't a consumer-electronics cycle — it's HBM allocation spilling over. For anyone working spot and consumer-grade parts, allocation, quote discipline, and secondary-channel windows now matter more than part selection.

memoryai-demandsupply-riskLPDDR4
Read more →
MLCC Repricing Wave Hardens: Samsung Electro-Mechanics +30% Lands, Taiyo Yuden Follows Sept 1 — Passives Become the Second Front Behind AI Servers

August 10, 2026

MLCC Repricing Wave Hardens: Samsung Electro-Mechanics +30% Lands, Taiyo Yuden Follows Sept 1 — Passives Become the Second Front Behind AI Servers

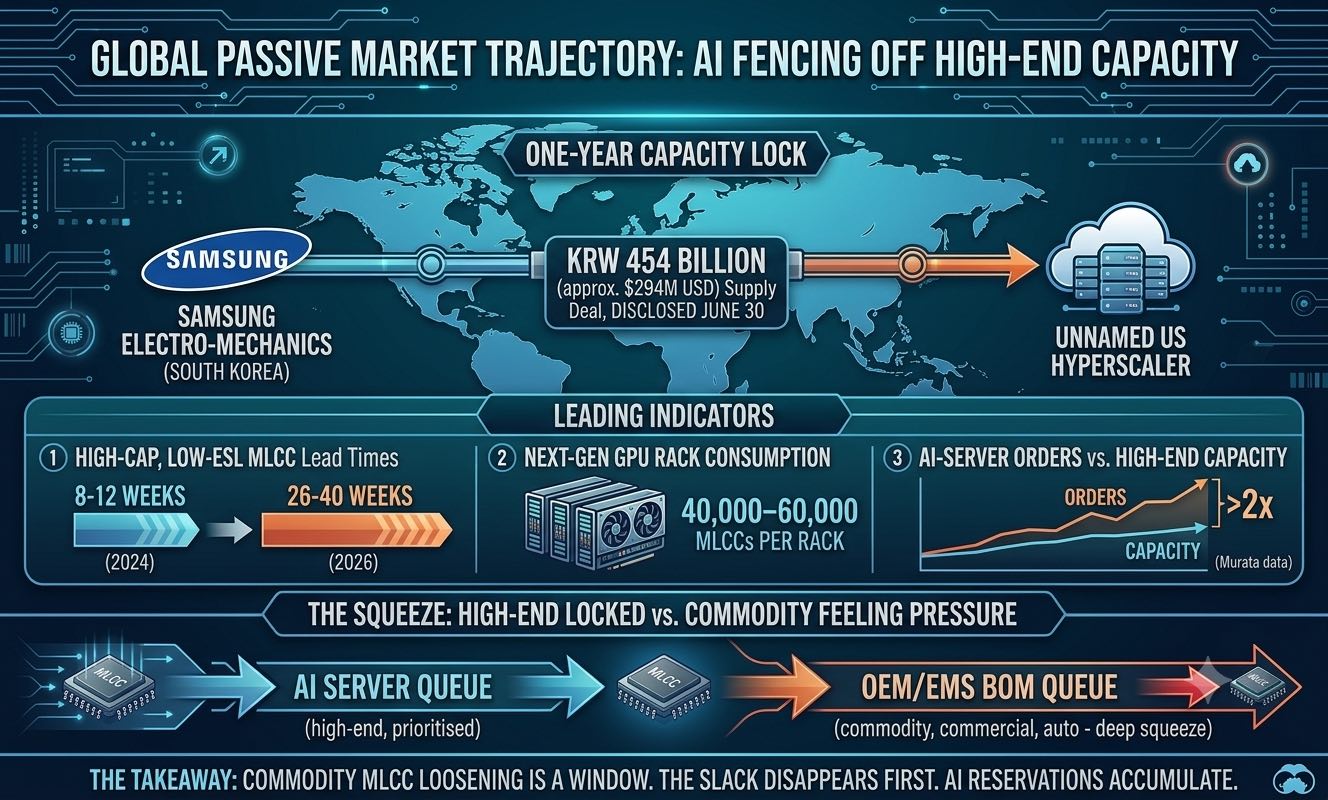
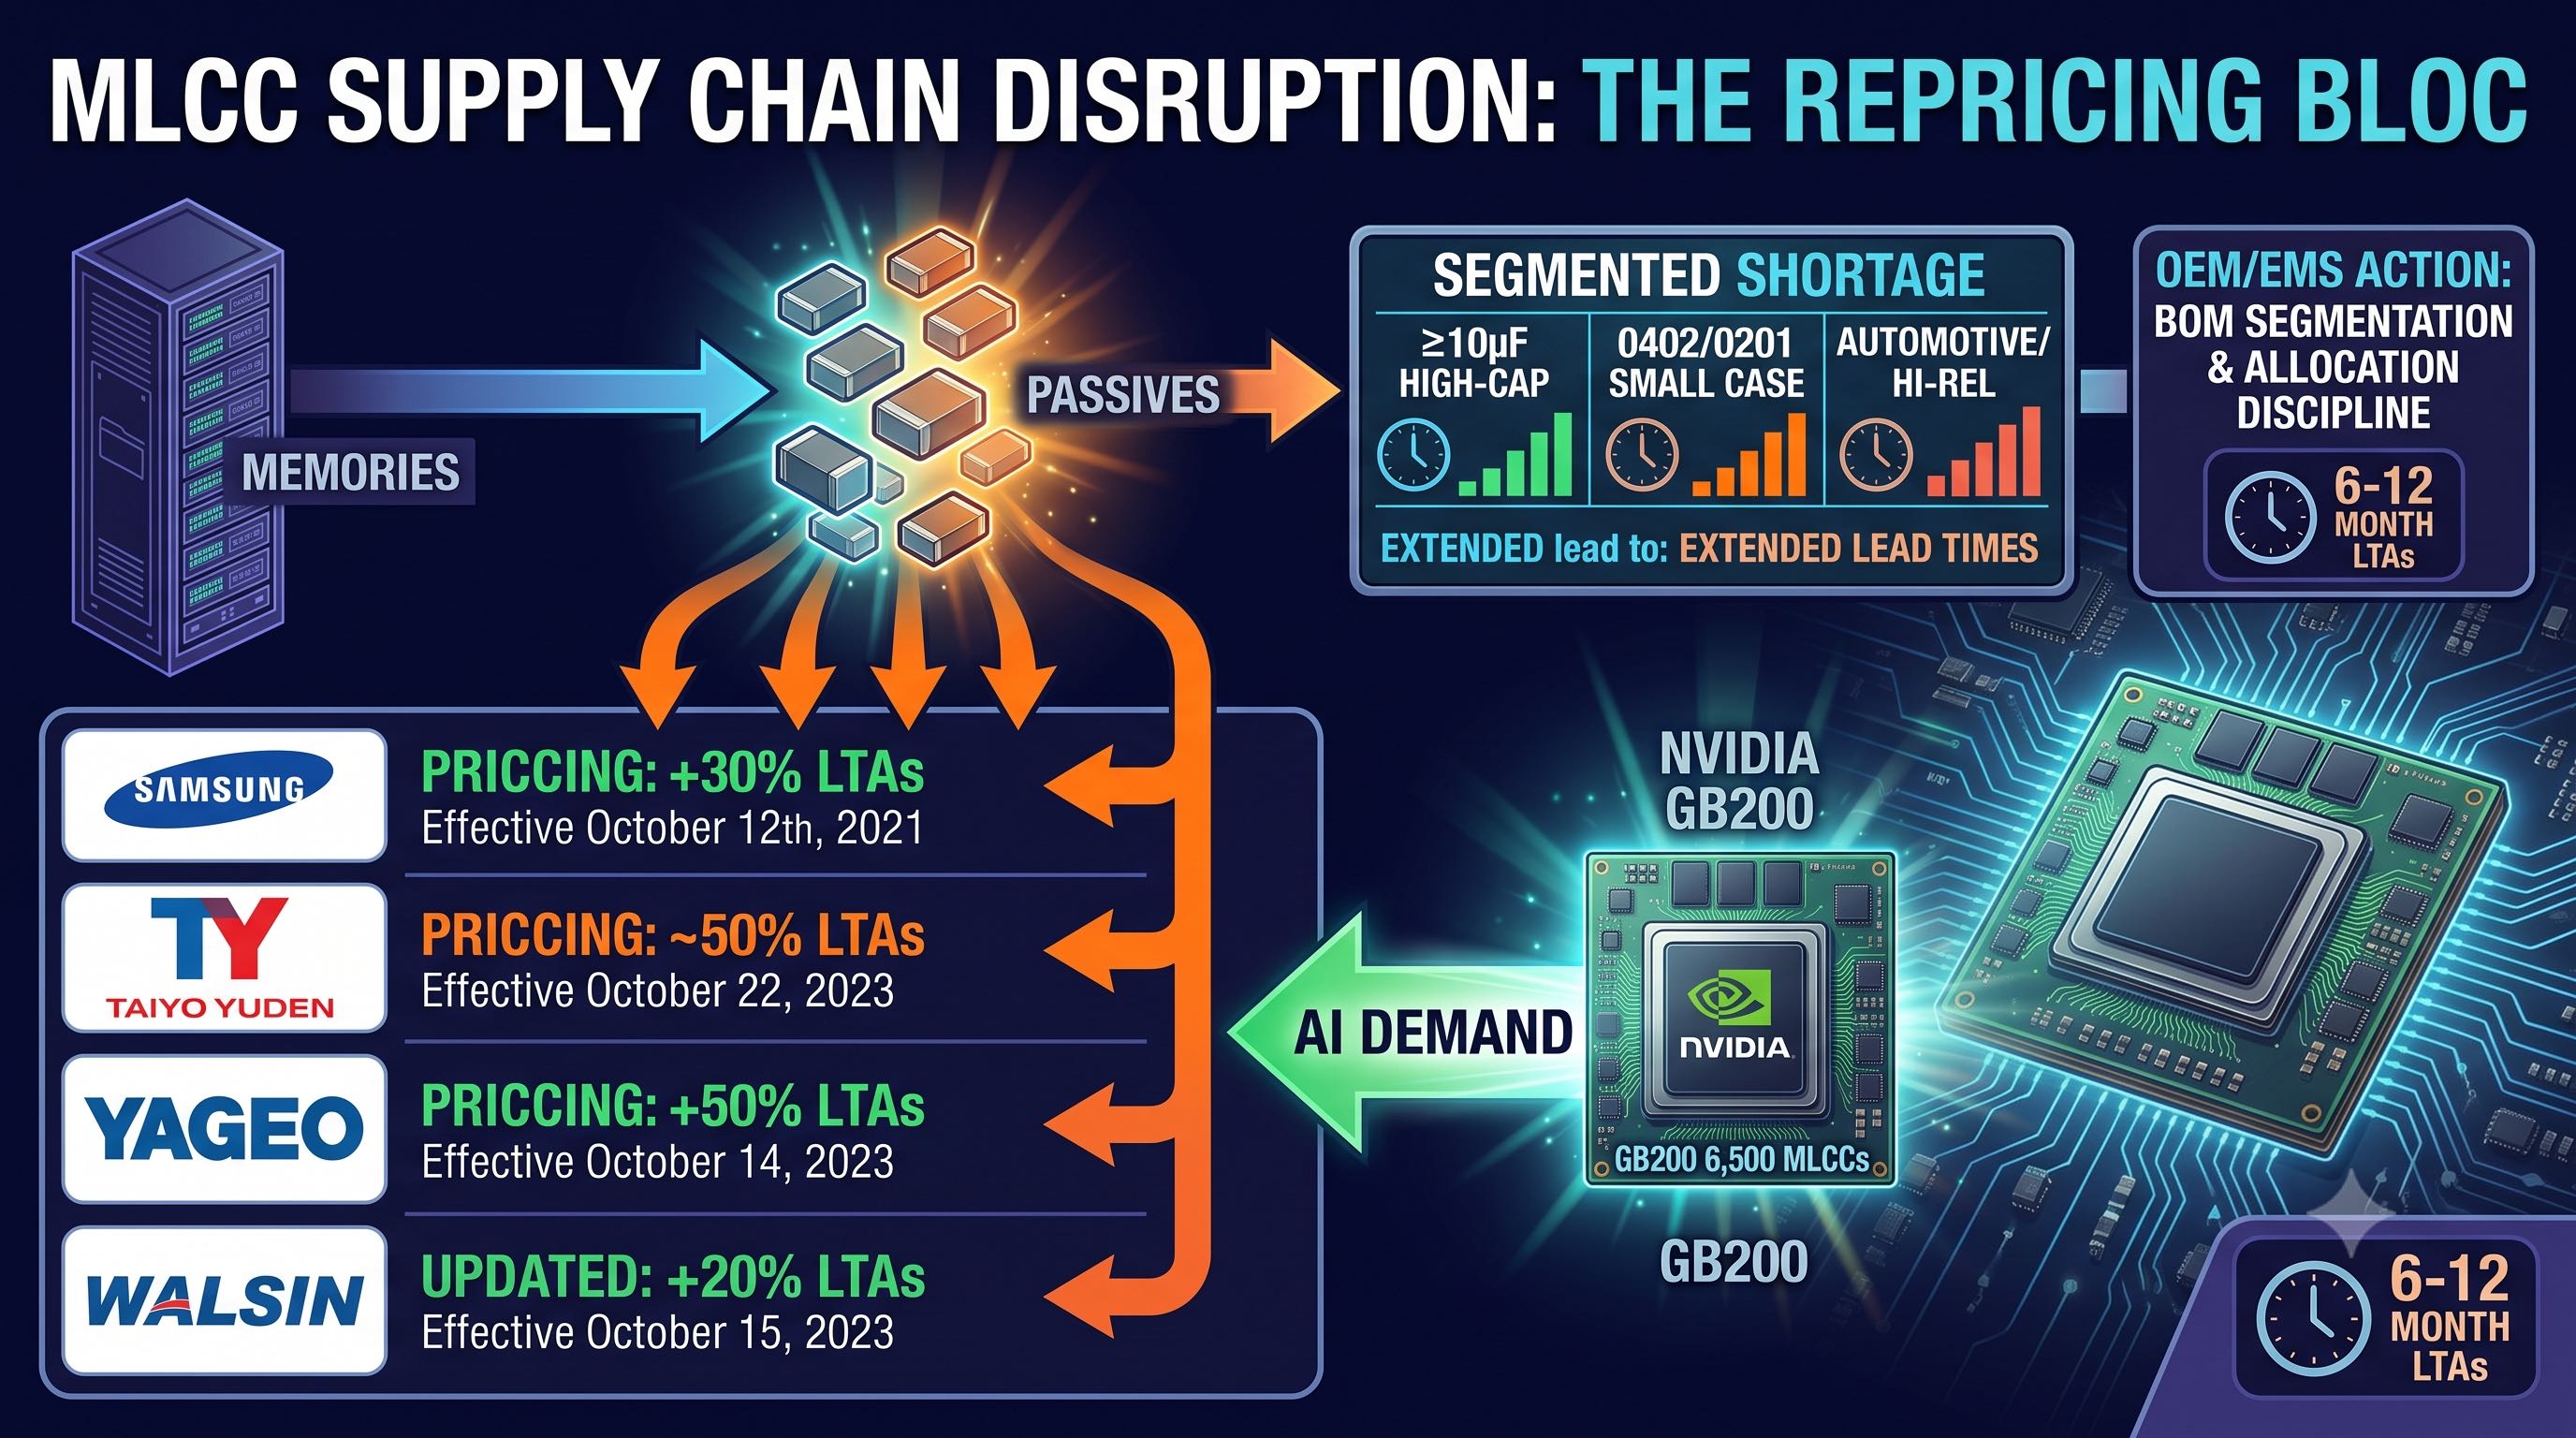
Memory headlines are so loud they buried the other line that is hardening fast: MLCCs. Samsung Electro-Mechanics' portfolio-wide +30% took effect August 1, Taiyo Yuden raises from September 1, and high-cap small-case lead times have stretched to 26-40 weeks. One GB200 board eats ~6,500 MLCCs. Here is how spot buyers and BOM owners should read it.

marketprocurementsupply-risksupply-chain
Read more →
Qualcomm's Sept 1 Across-the-Board Hike: Memory Inflation Just Landed on Your SoC Quote — How Spot Buyers Should Read It

August 3, 2026

Qualcomm's Sept 1 Across-the-Board Hike: Memory Inflation Just Landed on Your SoC Quote — How Spot Buyers Should Read It

Qualcomm is raising Snapdragon prices across the board on Sept 1 and said the quiet part out loud: memory, test, and advanced-packaging input costs are all up. This is the first time memory inflation shows up not as "DRAM/NAND went up again" but as an SoC price sheet. For spot buyers, the quoting logic changes — non-memory BOM is now in the hike lane, and someone will follow.

marketmemoryai-demandprocurement
Read more →
NAND Just Repriced Harder Than DRAM — Why Enterprise SSD Is the Squeeze Spot Buyers Keep Missing

July 31, 2026

NAND Just Repriced Harder Than DRAM — Why Enterprise SSD Is the Squeeze Spot Buyers Keep Missing

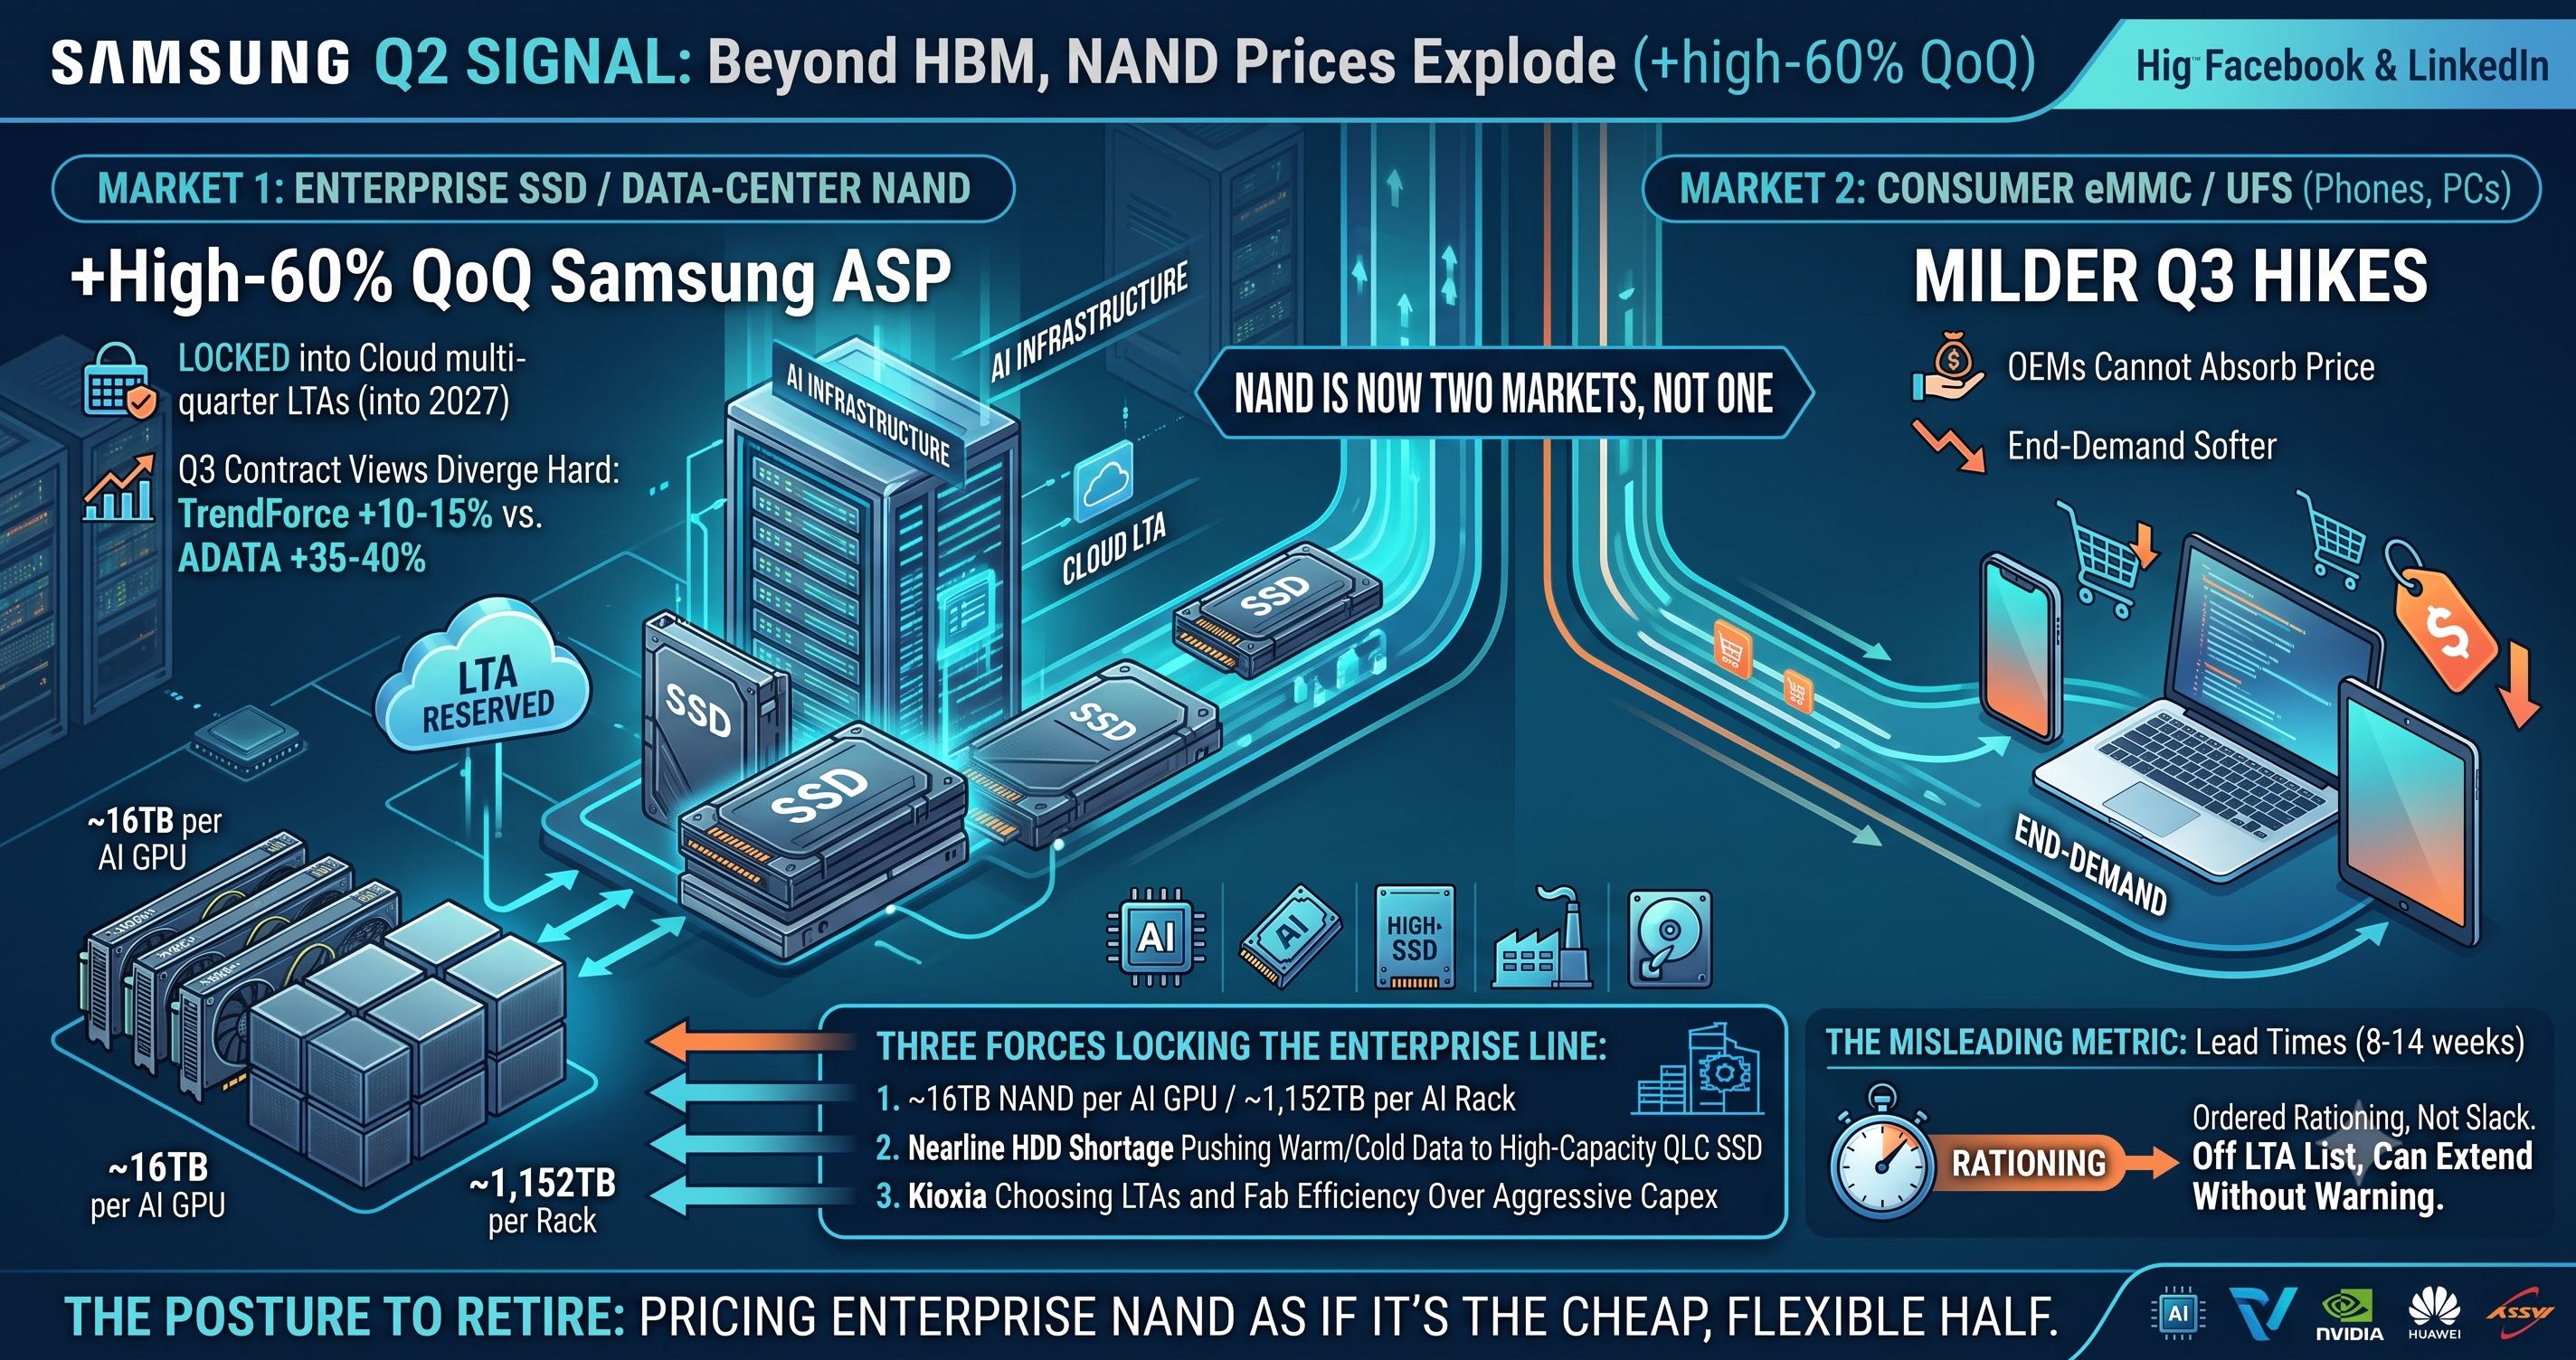
Everyone's watching HBM and server DRAM, but Samsung's own Q2 call laid the numbers bare: NAND ASP rose ~60% QoQ this quarter versus DRAM's ~40%. NAND is the half that climbed harder. Enterprise SSD has quietly become the largest NAND application, locked to cloud LTAs into 2027. Here's the split — enterprise locked, consumer soft — and a working checklist for spot buyers.

memoryai-demandsupply-riskprocurement
Read more →
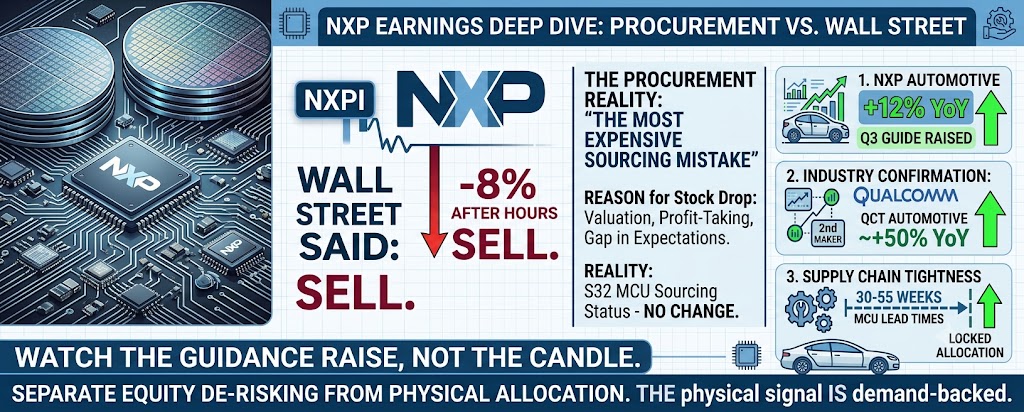
NXP Booked a Record Automotive Quarter and the Stock Still Fell 8% — The Spot-Buyer Read

July 29, 2026

NXP Booked a Record Automotive Quarter and the Stock Still Fell 8% — The Spot-Buyer Read

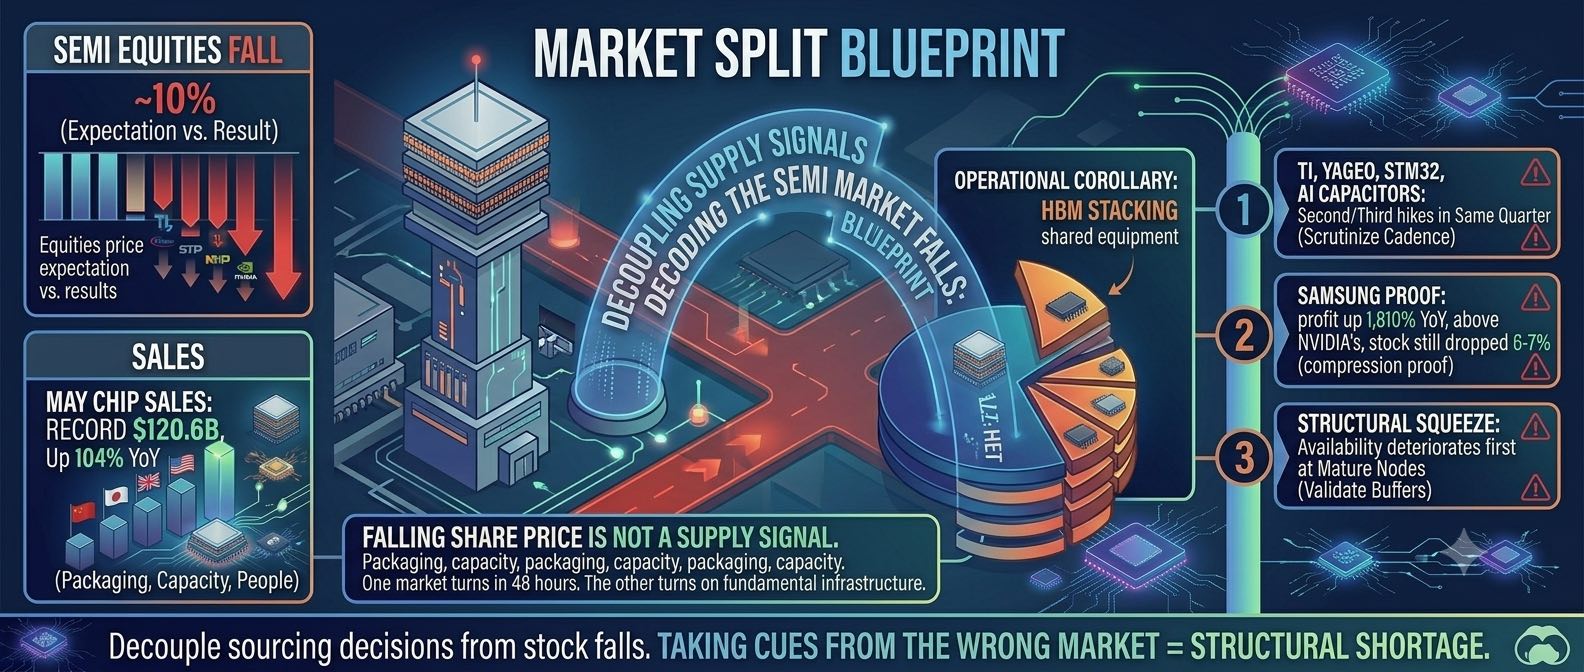
NXP beat on revenue and EPS in Q2 2026, grew automotive +12% YoY (+17% ex-MEMS), and raised Q3 guidance — and the stock still dropped ~7.7% after hours. The real signal isn't 'NXP fell.' It's that financial-market sentiment and physical allocation are running on two separate tracks. Here's how to quote and negotiate automotive parts around that.

marketprocurement2026-q2supply-chain
Read more →
$950B Just Locked Memory Capacity to 2030 — Three Things Spot Buyers Should Actually Do

July 27, 2026

$950B Just Locked Memory Capacity to 2030 — Three Things Spot Buyers Should Actually Do

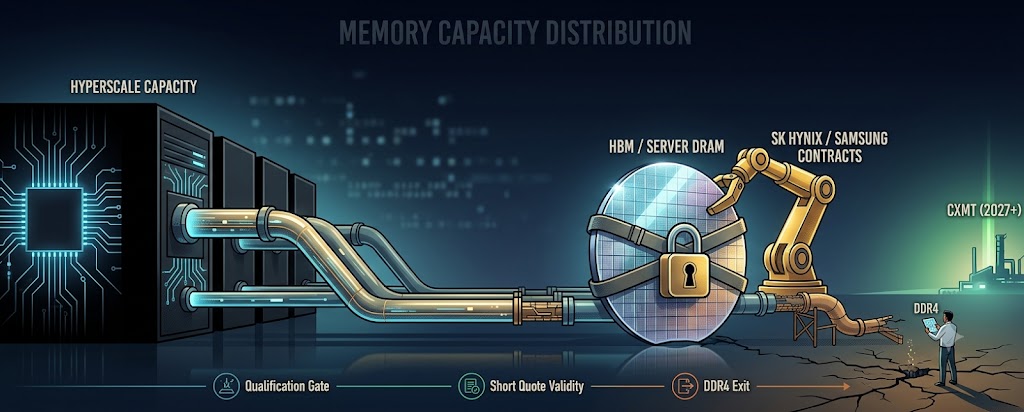
Over the weekend Korea announced ~$950B in SK Hynix + Samsung AI-chip supply pacts with US firms. This isn't a "they'll expand and cut prices" story — it's a supply-structure signal that hands leading HBM and server-DRAM capacity to hyperscalers under multi-year contracts. For spot and commercial buyers, marginal allocation only gets thinner. Here are three things you can act on this week.

memoryai-demandsupply-chainsamsung
Read more →
China-Made DDR5 Dies Are Finally Narrowing the Gap — In the Same Week Spot Hit a Record. Here's the Second-Source Read for Spot Buyers

July 24, 2026

China-Made DDR5 Dies Are Finally Narrowing the Gap — In the Same Week Spot Hit a Record. Here's the Second-Source Read for Spot Buyers

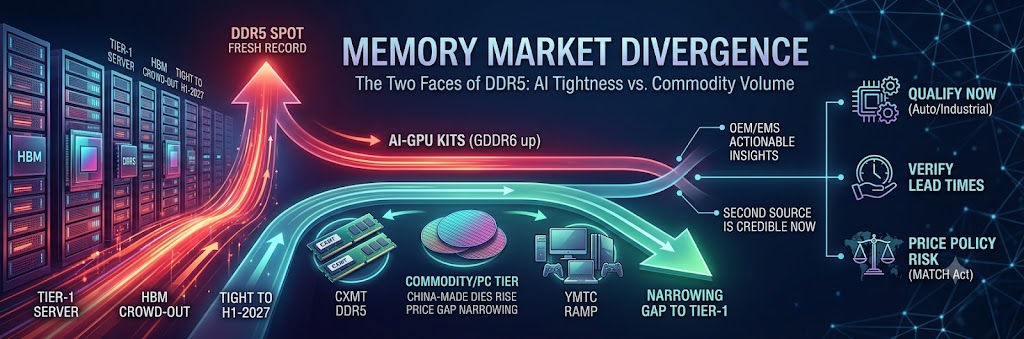
DDR5 module spot set another all-time high this week, yet the same industry read flags China-made (CXMT-class) dies narrowing the price gap to tier-1 makers. That's not servers loosening — it's the commodity/PC tier finally opening a real substitution window. Here's which parts can take a second source, which can't move, and the three gates to clear first.

memorysupply-chainsupply-riskmarket
Read more →
HBM Is Eating DDR5's Wafers: Why Server Memory Stays Tight Into 2027 — and Consumer Price Cuts Don't Change That

July 22, 2026

HBM Is Eating DDR5's Wafers: Why Server Memory Stays Tight Into 2027 — and Consumer Price Cuts Don't Change That

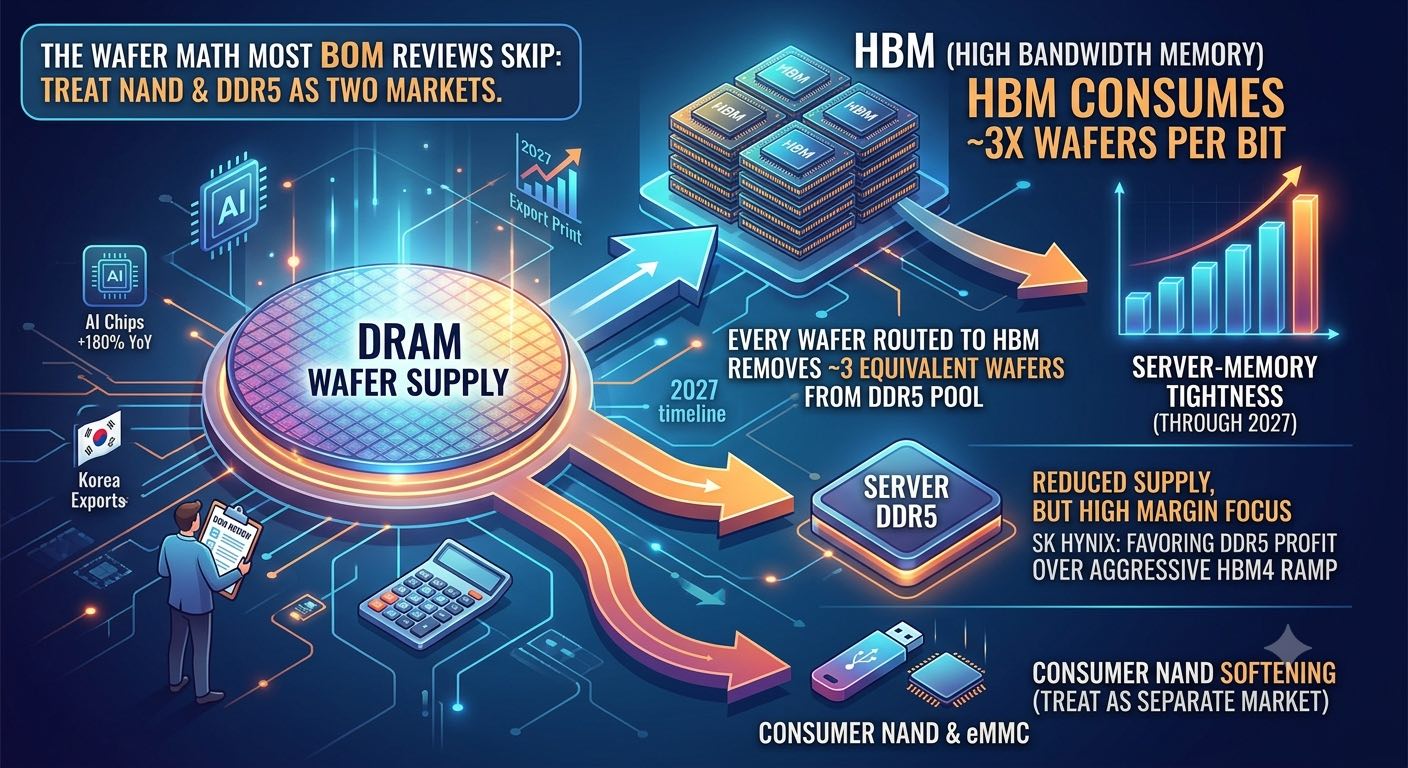
One sentence: every wafer that goes into HBM pulls roughly three out of the DDR5 line. Makers are openly prioritizing higher-margin DDR5 over the HBM4 ramp, so the server-DDR5 crunch isn't a cyclical wobble — it's a structural gap written into wafer allocation, holding until new capacity lands in H1 2027. Consumer NAND/eMMC is cooling, but that's a different book — don't let it discount your server parts.

memoryai-demandsupply-risksupply-chain
Read more →
TSMC Is Putting Advanced Packaging in Arizona — and Not One Lead Time on Your Desk Gets Shorter Because of It

July 20, 2026

TSMC Is Putting Advanced Packaging in Arizona — and Not One Lead Time on Your Desk Gets Shorter Because of It

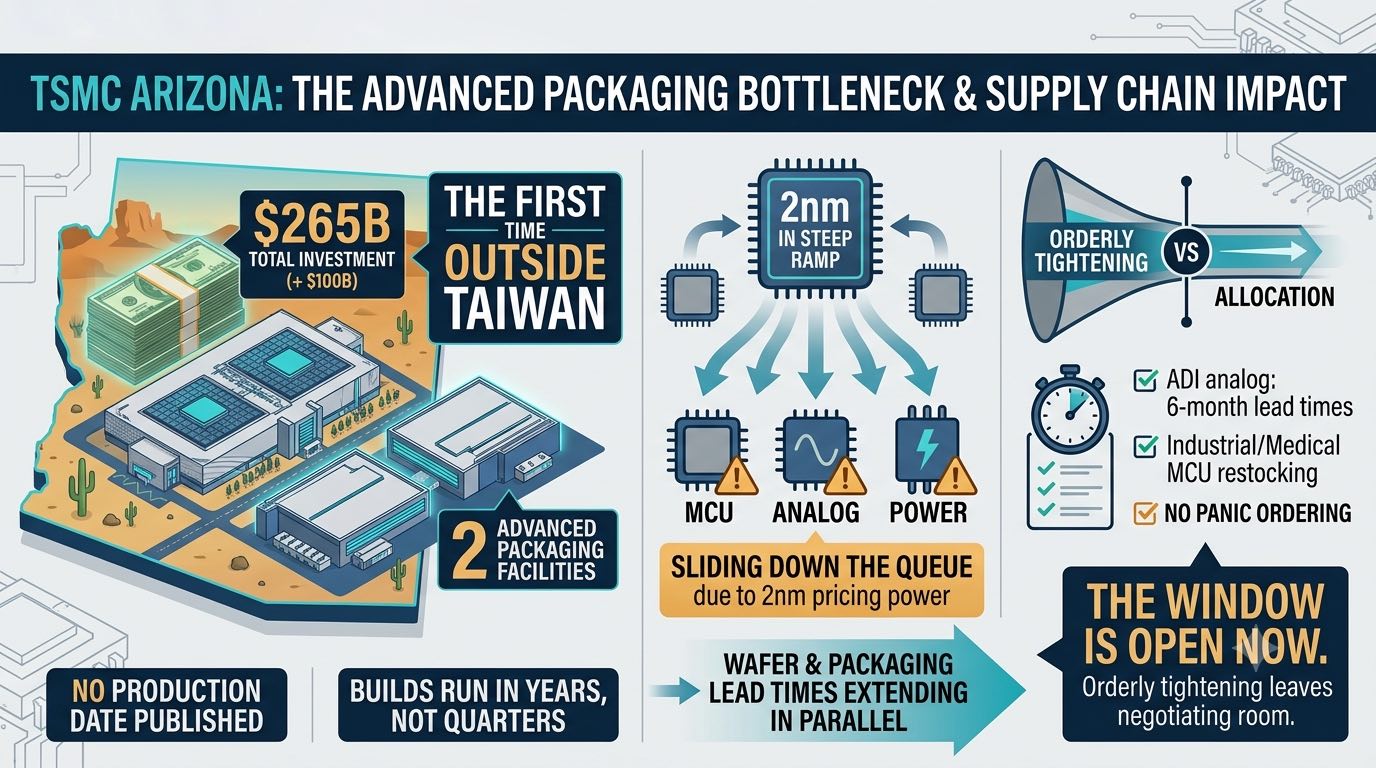
On July 16 TSMC released 2Q26 results and a $100B Arizona expansion on the same day. The earnings looked excellent. The part that actually carries information for spot buyers is buried in the investment announcement: two advanced packaging facilities, the first TSMC has ever committed outside Taiwan. That is an official confirmation of what has been constraining this cycle — and it is not wafers.

marketai-demandprocurement2026-q2
Read more →
The Price Wave Just Left the Memory Aisle: Analog, MCU, Power and Passives Are All Repricing — and the "Cheap" Half of Your BOM Isn't Cheap Anymore

July 17, 2026

The Price Wave Just Left the Memory Aisle: Analog, MCU, Power and Passives Are All Repricing — and the "Cheap" Half of Your BOM Isn't Cheap Anymore

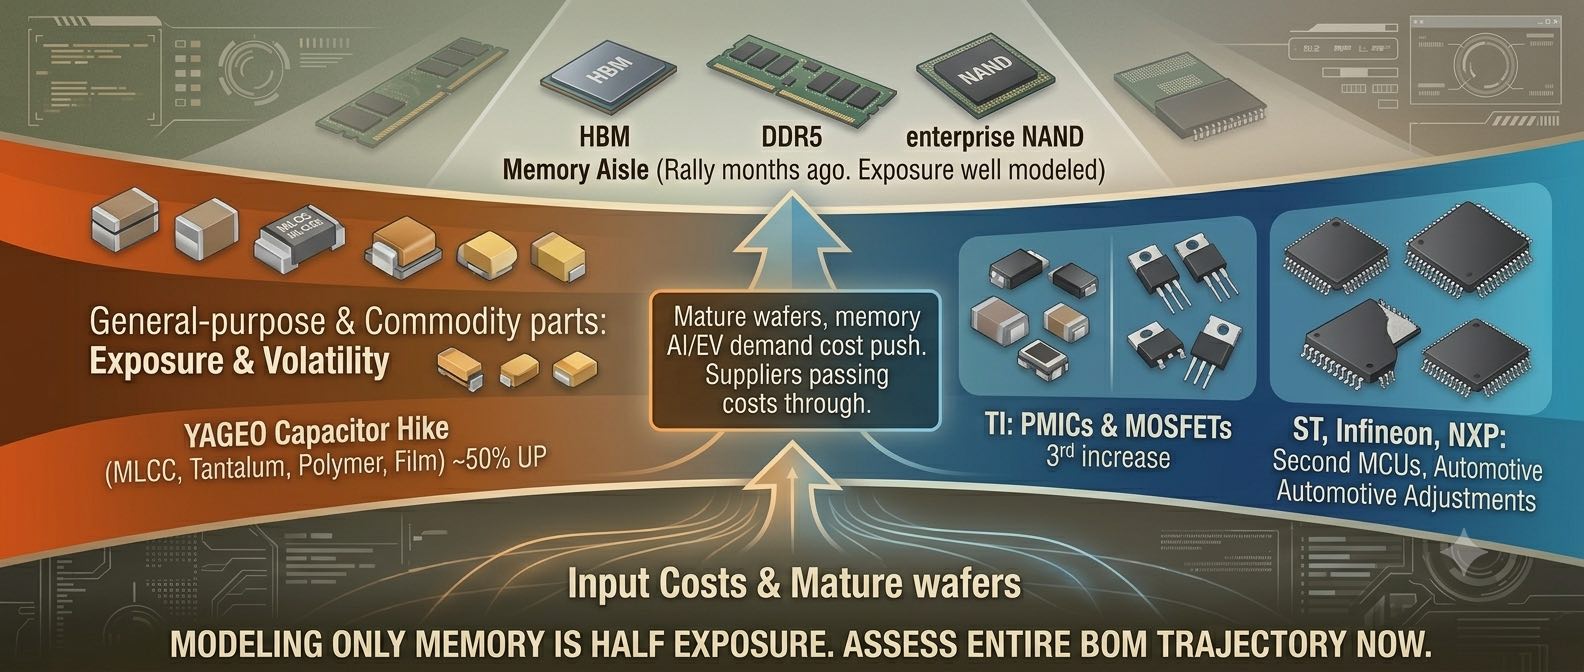
For six months the market watched memory. The real shift in July is that the price wave has left the memory aisle. YAGEO's broadest capacitor hike in years, TI's third increase of 2026, second rounds from ST/Infineon/NXP, and general-purpose MLCC now moving 6-13%. The parts everyone treated as jellybeans are now the front line of repricing.

marketprocurementsupply-chainsupply-risk
Read more →
Ingenic's Profit Just Jumped Over 400% — The Memory Super-Cycle Has Reached Specialty Memory, and Spot Buyers Should Know Which Parts

July 15, 2026

Ingenic's Profit Just Jumped Over 400% — The Memory Super-Cycle Has Reached Specialty Memory, and Spot Buyers Should Know Which Parts

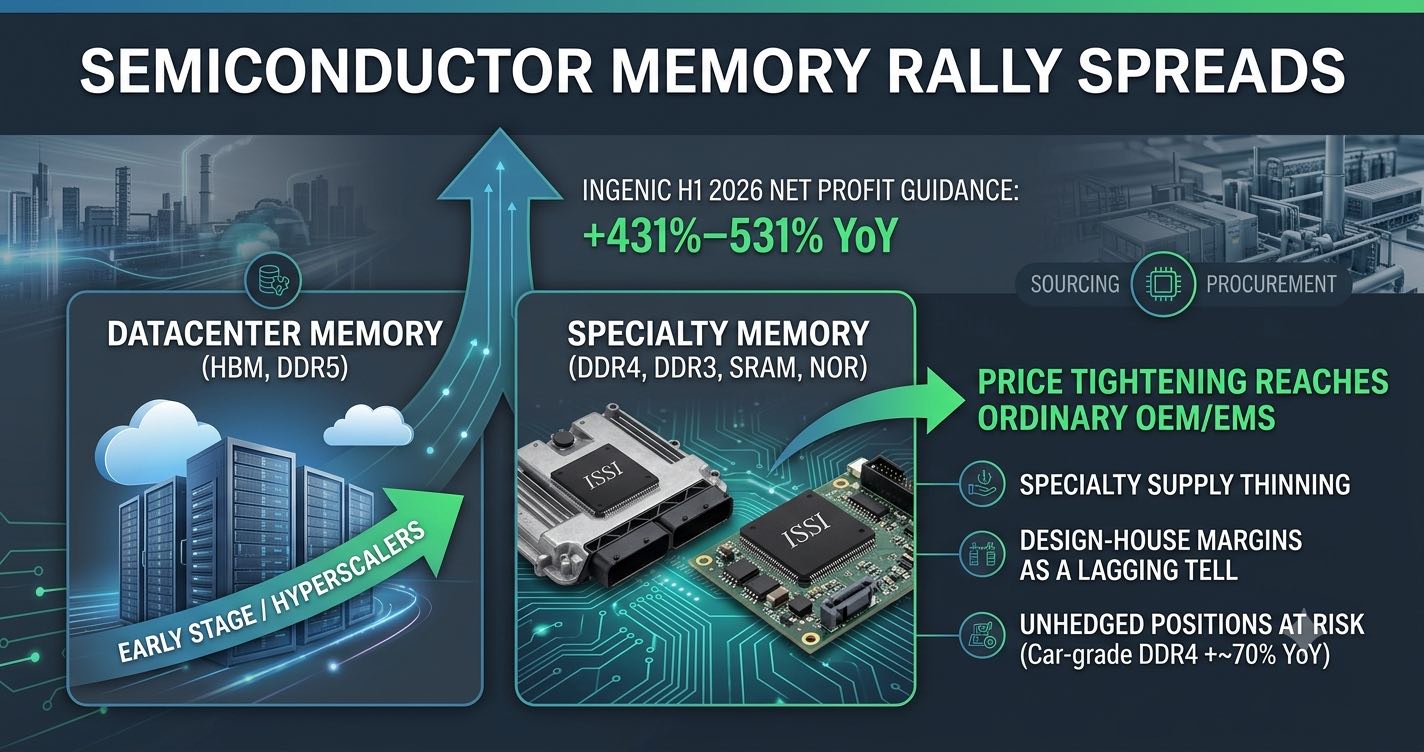
On July 13, Ingenic guided first-half net profit up 431%-531% year-on-year. Don't read it as one company's earnings — read it as a signal. This rally is no longer just an HBM and DDR5 story. It has reached the ISSI specialty DRAM / SRAM / NOR lines, the exact parts industrial, automotive, and code-storage BOMs actually run.

memorysupply-riskindustrialprocurement
Read more →
Micron Just Spent Up to $3B to Lock a Decade of Silicon Wafers — and Wrote Memory Tightness Into 2027

July 10, 2026

Micron Just Spent Up to $3B to Lock a Decade of Silicon Wafers — and Wrote Memory Tightness Into 2027

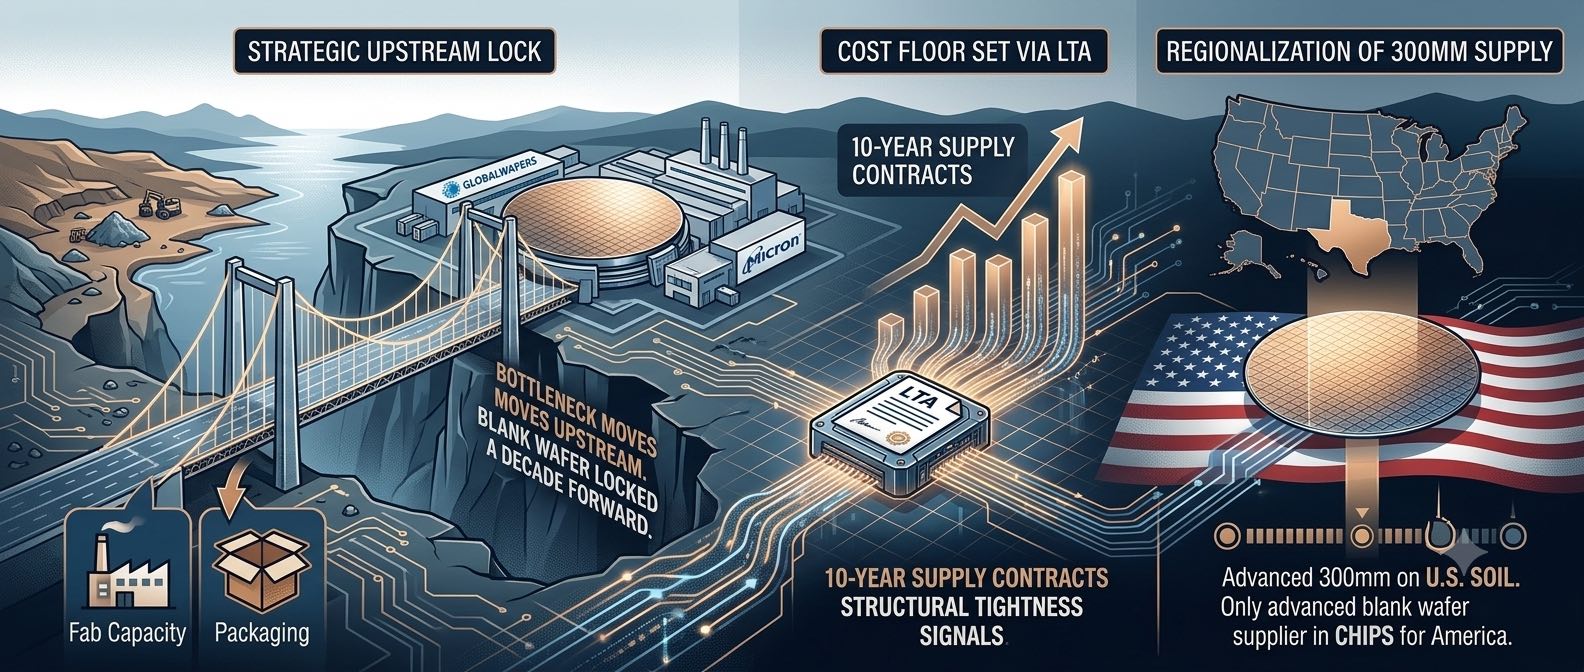
On July 9 Micron committed up to $3 billion to strengthen the U.S. chip ecosystem, anchored by $500M in strategic financing for GlobalWafers' 300mm plant in Sherman, Texas, plus a 10-year raw silicon wafer supply deal. This isn't buying chips — it's buying the raw material to make them. For spot buyers, the signal is blunt: don't bet on a near-term price floor drop.

memorysupply-chainsupply-riskprocurement
Read more →
The Memory Rally Just Split in Two: Why 3Q26 Rewards Spot Buyers Who Stop Treating "Memory" as One Trade

July 8, 2026

The Memory Rally Just Split in Two: Why 3Q26 Rewards Spot Buyers Who Stop Treating "Memory" as One Trade

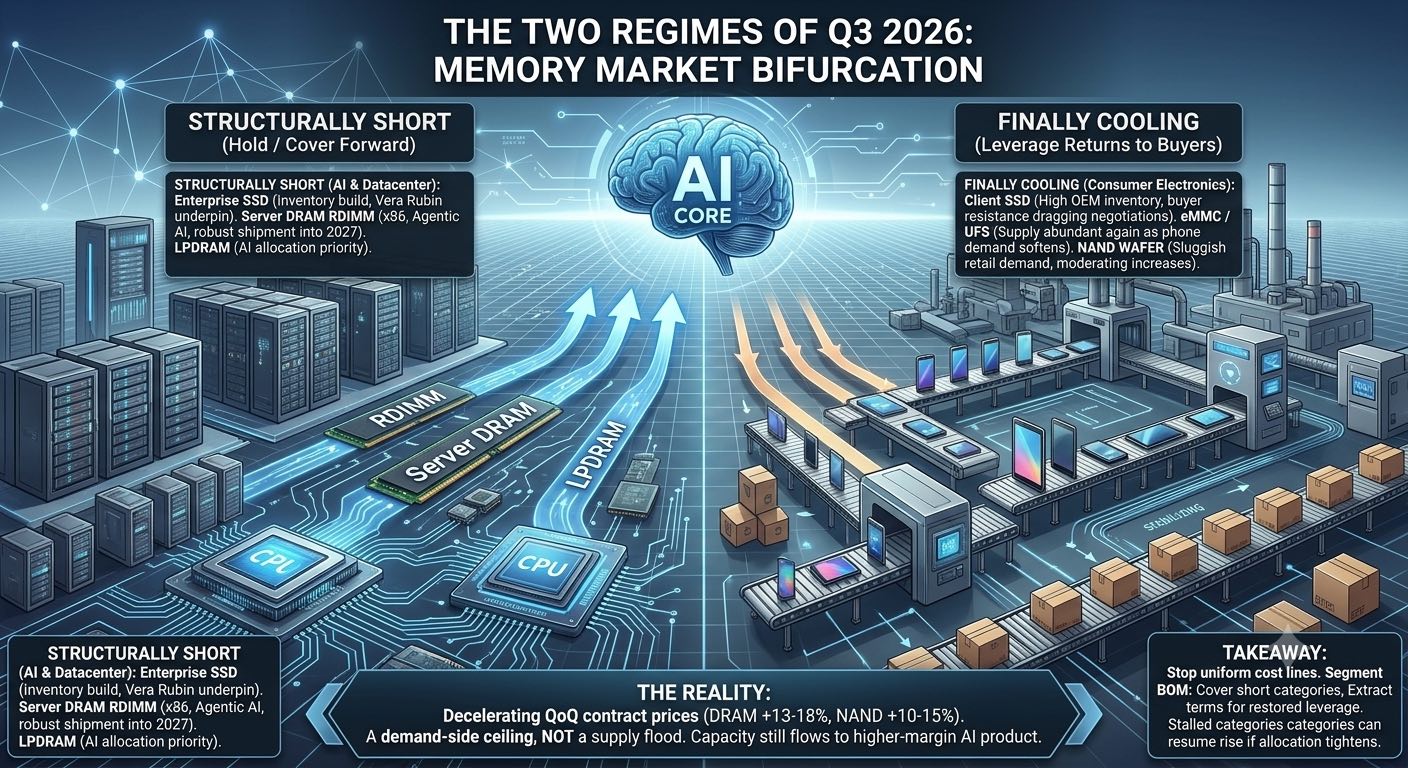
On July 3, TrendForce set the tone for 3Q26: conventional DRAM contract prices up 13-18% QoQ, NAND up 10-15%, both slower than prior quarters. The real signal is the split underneath: AI servers and enterprise SSD keep climbing while client SSD, eMMC/UFS and wafer hit the consumer affordability ceiling. The first quarter in a year worth trading in two halves.

marketmemoryai-demandprocurement
Read more →
SK hynix Lists on Nasdaq July 10: How the HBM Leader's Capital-Market Move Reshapes the Allocation Signal for Spot Buyers

July 6, 2026

SK hynix Lists on Nasdaq July 10: How the HBM Leader's Capital-Market Move Reshapes the Allocation Signal for Spot Buyers

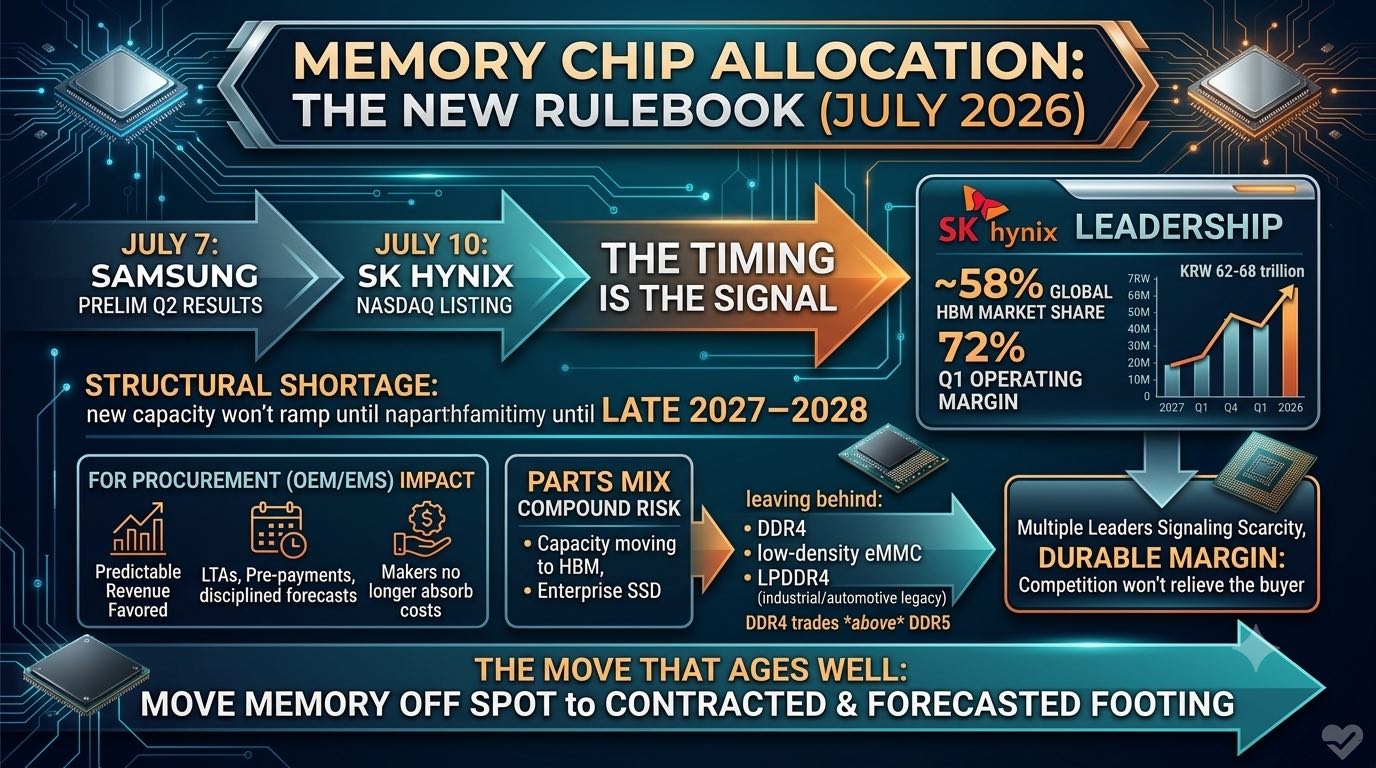
SK hynix lists ADRs on Nasdaq on July 10, with Samsung's Q2 preliminary print landing July 7. Together they tie the memory leader's capacity pricing to the capital markets. For spot buyers and industrial OEMs this is not a finance headline — it is a 2026-2027 allocation weathervane. Here is how to read it across parts, timing and channel.

memoryai-demandmarketsupply-risk
Read more →
A Single $294M MLCC Long-Term Deal Just Locked Away More AI-Server Capacitor Capacity — Which Parts and Windows Spot Buyers Should Watch

July 1, 2026

A Single $294M MLCC Long-Term Deal Just Locked Away More AI-Server Capacitor Capacity — Which Parts and Windows Spot Buyers Should Watch

On June 30, Samsung Electro-Mechanics disclosed a one-year MLCC supply contract worth about $294M with an unnamed US cloud provider, shipping from January 2027. The dollar figure is small; the signal is not. This is capacity being locked by contract, not another price hike — and for spot and secondary-channel buyers, the parts to move on are the high-cap codes sitting in your own BOM.

marketai-demandprocurementsamsung
Read more →
China Just Wrote Rare Earths and Dual-Use Into Its June 22 Retaliation List — What Spot Buyers Should Actually Check Is Their Own BOM

June 29, 2026

China Just Wrote Rare Earths and Dual-Use Into Its June 22 Retaliation List — What Spot Buyers Should Actually Check Is Their Own BOM

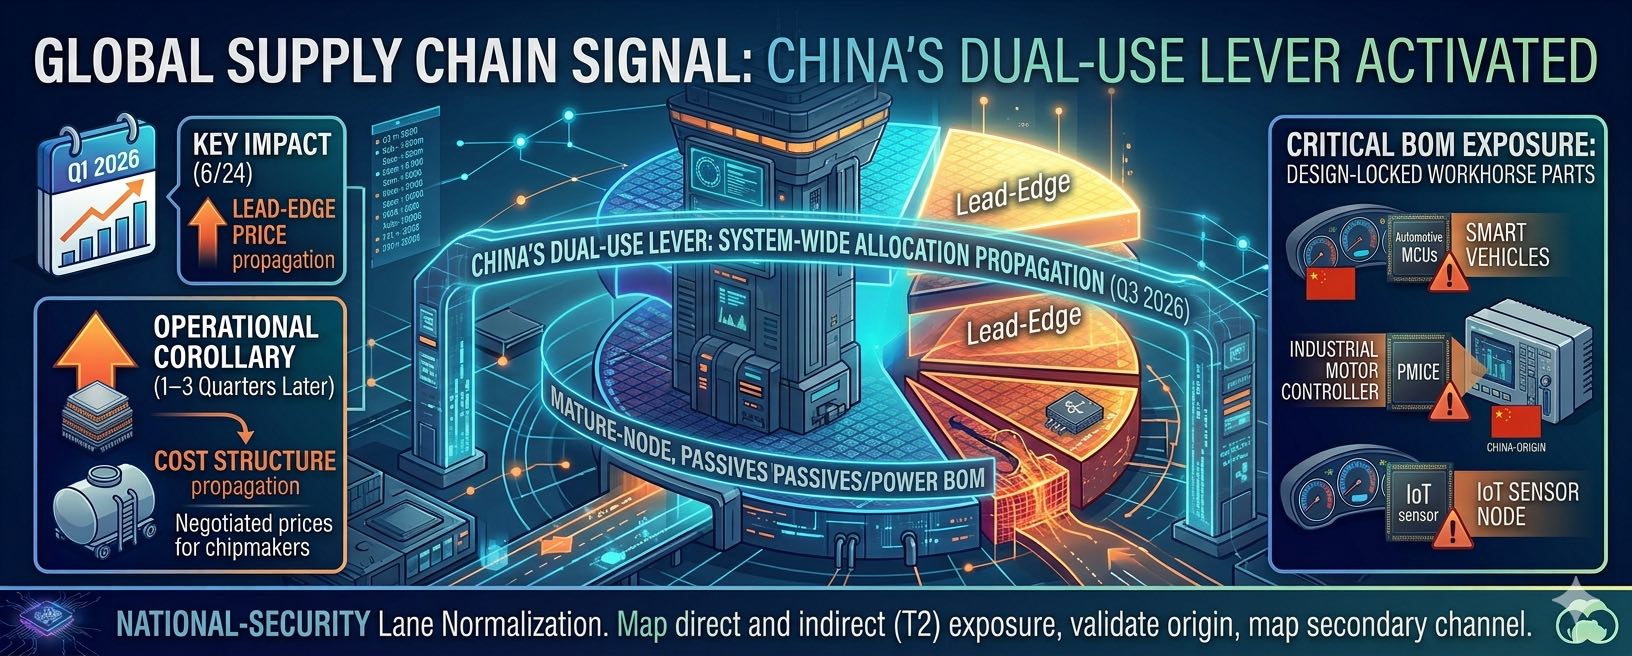
On June 22 China's Commerce Ministry put 10 US firms on its export-control list and the Finance Ministry barred procurement from 46 more; a rare-earth miner and a magnet maker were named. For anyone trading spot chips and excess inventory, the real signal isn't the sanction — it's the words "dual-use" and "worldwide." Here's how to turn that into things you can do today.

marketprocurementsupply-risksupply-chain
Read more →
TSMC Just Hiked Every Node Below 7nm by 5–10% — But the Spot-Channel Signal Is in the Mature Capacity Being Pulled Away, Not the Leading Edge

June 26, 2026

TSMC Just Hiked Every Node Below 7nm by 5–10% — But the Spot-Channel Signal Is in the Mature Capacity Being Pulled Away, Not the Leading Edge

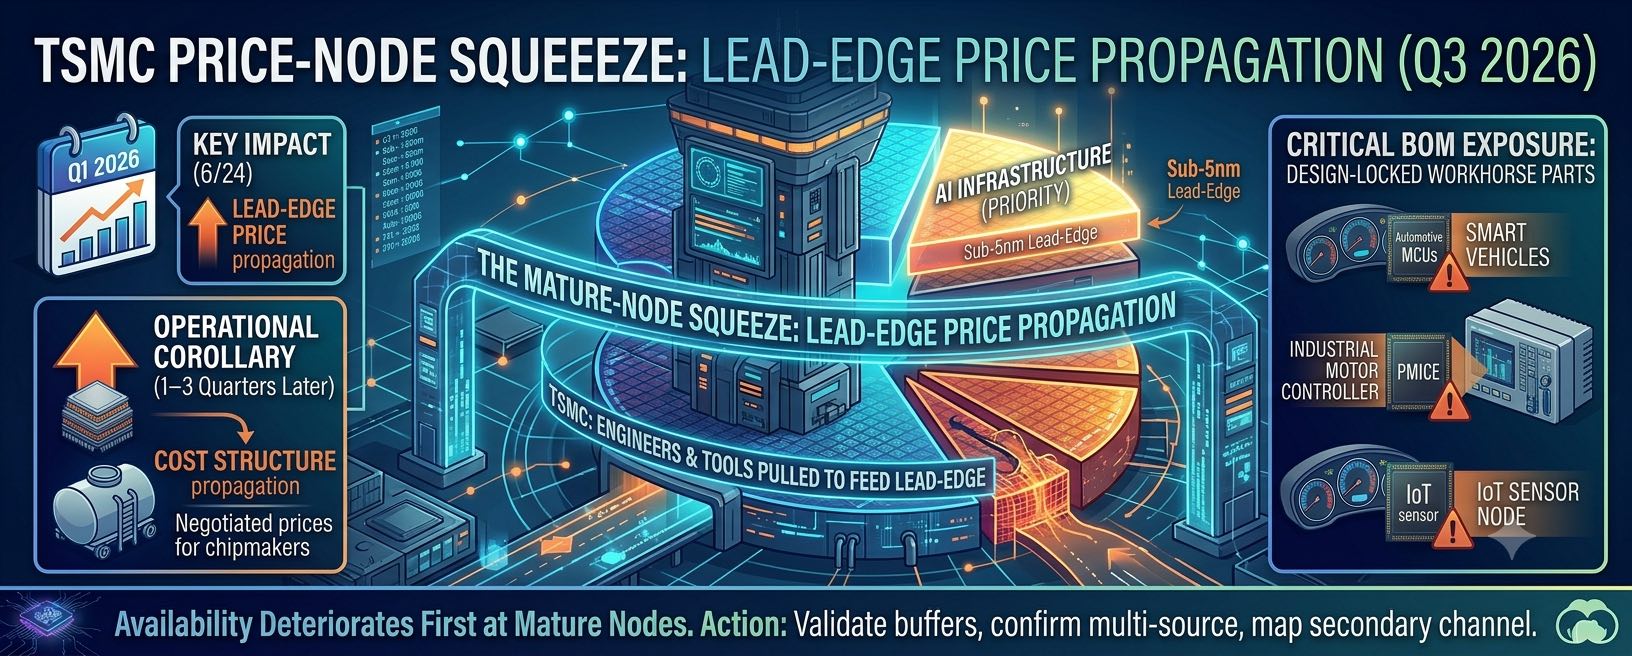
On June 24 TSMC told customers it is raising prices 5–10% across all advanced nodes, 7nm and down. Spot buyers don't touch N2 wafers, so the headline number isn't your trade. The real signal is on the other side: TSMC is moving people and tools to sub-5nm, and mature-node parts are about to get tight. Here's where the cut lands and which parts to watch.

marketai-demandprocurementsupply-risk
Read more →
Analog and Power Majors Fire Their Second Hike of the Year This Week: ST on June 28, TI and Infineon on July 1 — What Spot Buyers Pull and What Windows They Hold

June 24, 2026

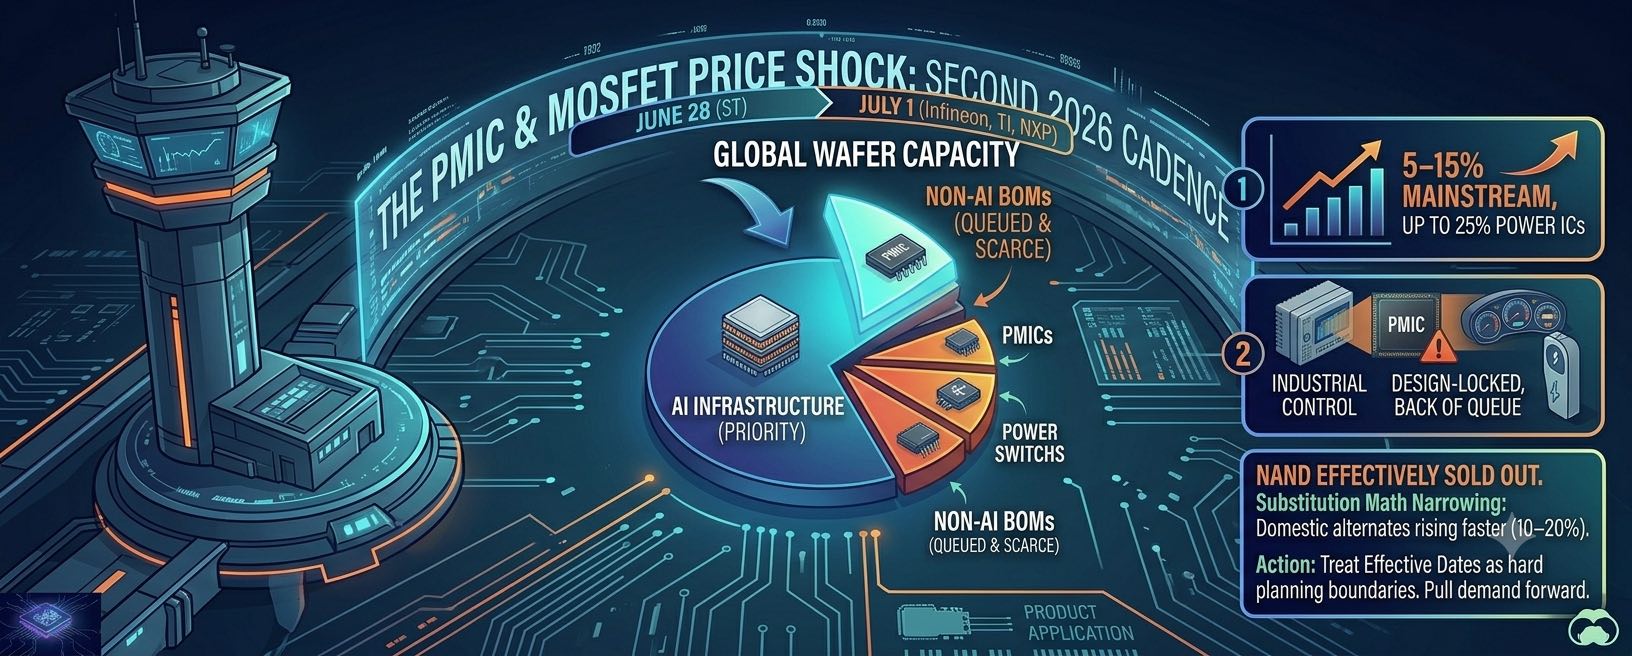
Analog and Power Majors Fire Their Second Hike of the Year This Week: ST on June 28, TI and Infineon on July 1 — What Spot Buyers Pull and What Windows They Hold

This isn't one vendor moving. ST, Infineon, TI and NXP all land their second 2026 increase inside the same week, 5%–15% across PMICs, MOSFETs and power devices — parts on every BOM. Here's a working read for people actually moving inventory: which parts get hit first, how the move travels through the channel, and what to lock before the weekend.

marketprocurementsupply-chainai-demand
Read more →
Enterprise SSD Is Draining the NAND Pool: How General-Purpose Parts, eMMC and UFS Get Pushed Into the Spot and Secondary Channel

June 22, 2026

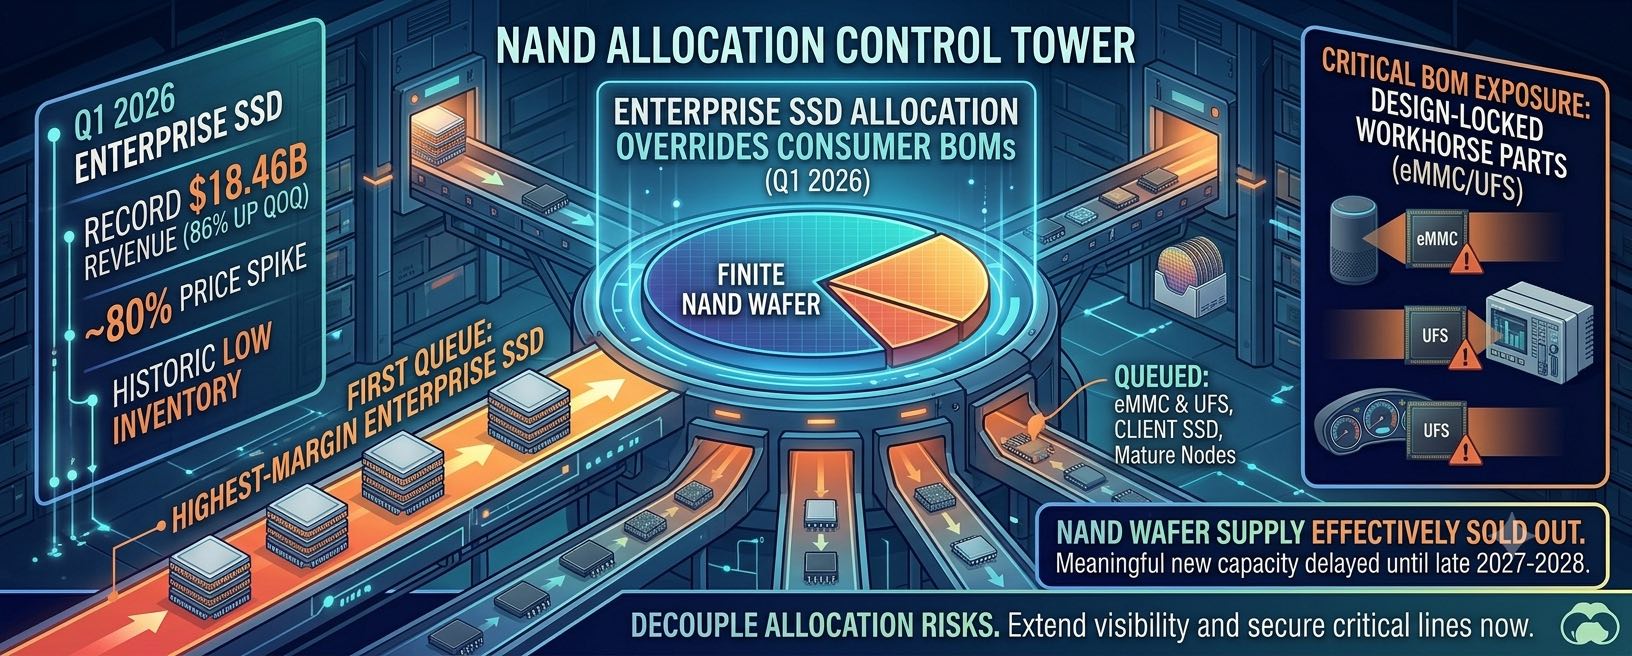
Enterprise SSD Is Draining the NAND Pool: How General-Purpose Parts, eMMC and UFS Get Pushed Into the Spot and Secondary Channel

Q1 enterprise SSD revenue hit a record $18.46B, up 86% QoQ, with contract prices up ~80% in a single quarter and supplier inventory at historic lows. AI is maxing out high-margin enterprise SSD capacity, dragging general NAND, eMMC and UFS up and out. Here's the practical read for spot buyers: what moves first, what to clear, what to stock.

memoryai-demandprocurement2026-q2
Read more →
Why Micron's June 24 Earnings Is the Real Test of the AI Memory Supercycle — Three Numbers Spot Buyers Should Watch

June 19, 2026

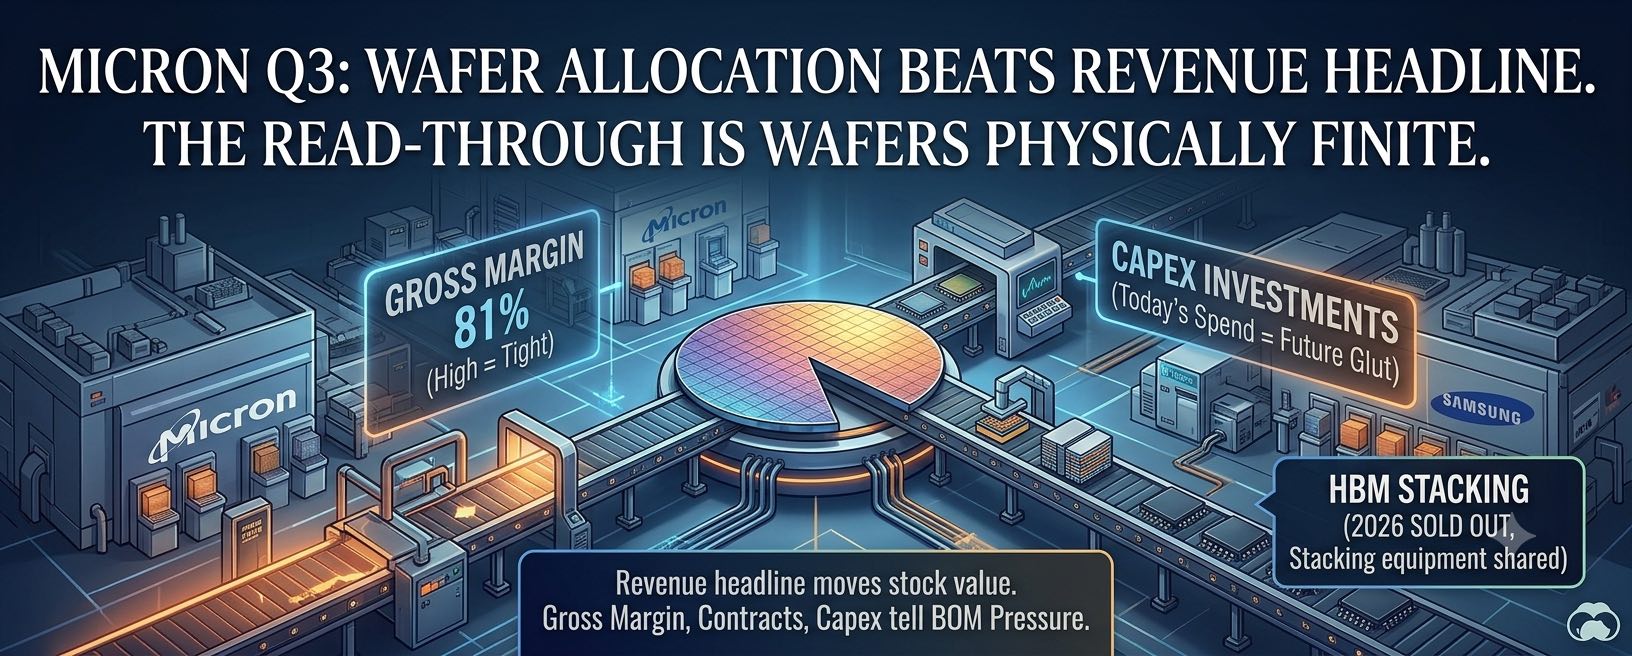
Why Micron's June 24 Earnings Is the Real Test of the AI Memory Supercycle — Three Numbers Spot Buyers Should Watch

Micron reports FQ3 after the close on June 24, and Wall Street's revenue estimates span $33.7B to $40.9B. For anyone sourcing mainstream DDR5, DDR4, LPDDR, or enterprise SSD, this print signals whether makers keep diverting capacity into HBM or start loosening. Here are the three numbers that matter and what to do now.

memoryai-demandmarketsupply-risk
Read more →
The Chip Market Has Split in Two: MCUs Are Still in Allocation While Analog and Discretes Loosen — Where Spot Buyers Should Move Now

June 17, 2026

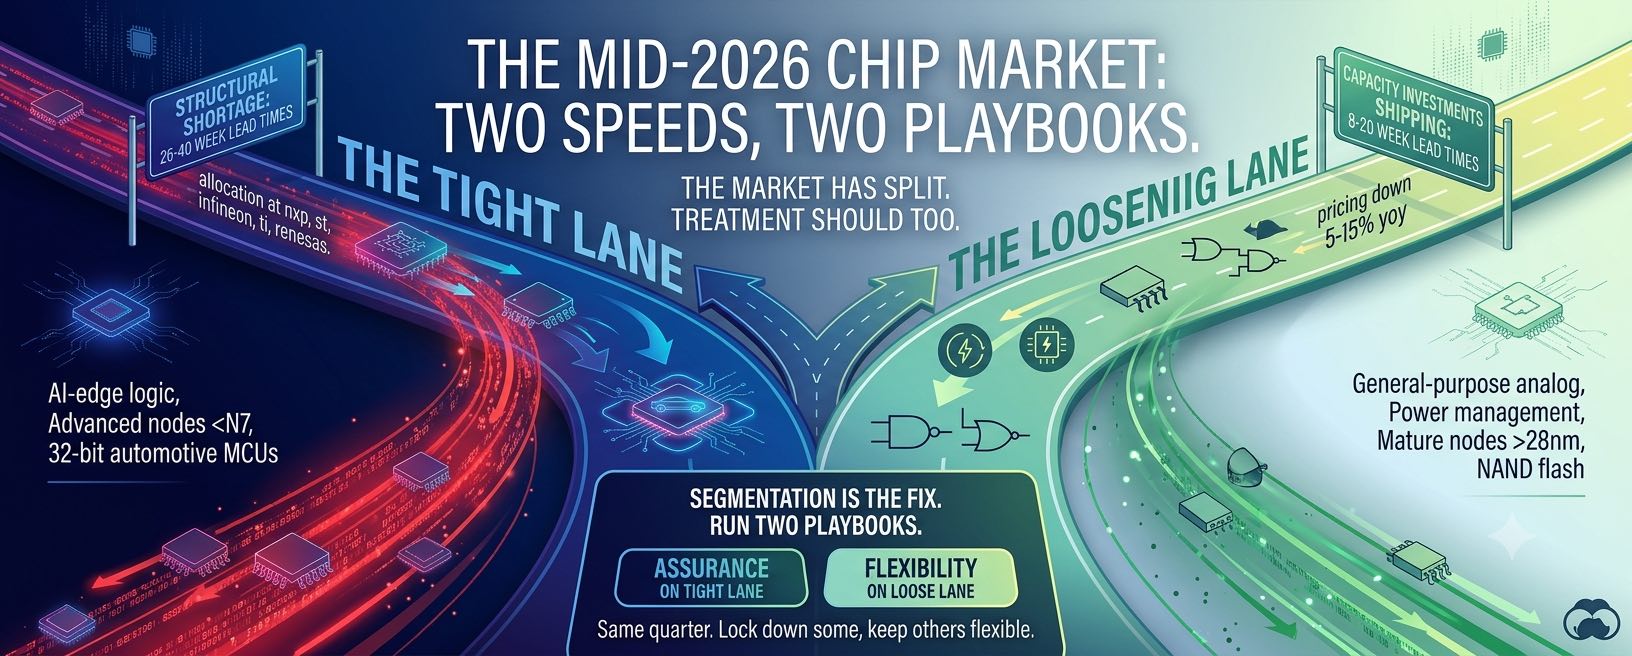
The Chip Market Has Split in Two: MCUs Are Still in Allocation While Analog and Discretes Loosen — Where Spot Buyers Should Move Now

Mid-2026 isn't a blanket shortage — it's a two-speed market. AI-edge logic and automotive MCUs are locked at 26–40 weeks, while analog, discretes, mature-node logic and NAND quietly soften 5–15%. Anyone still sourcing on a single "chip shortage" headline is losing on both ends. Here's the spot-desk read: what to chase, what to wait out, and how to turn dead stock into cash.

marketprocurementindustrialsupply-chain
Read more →
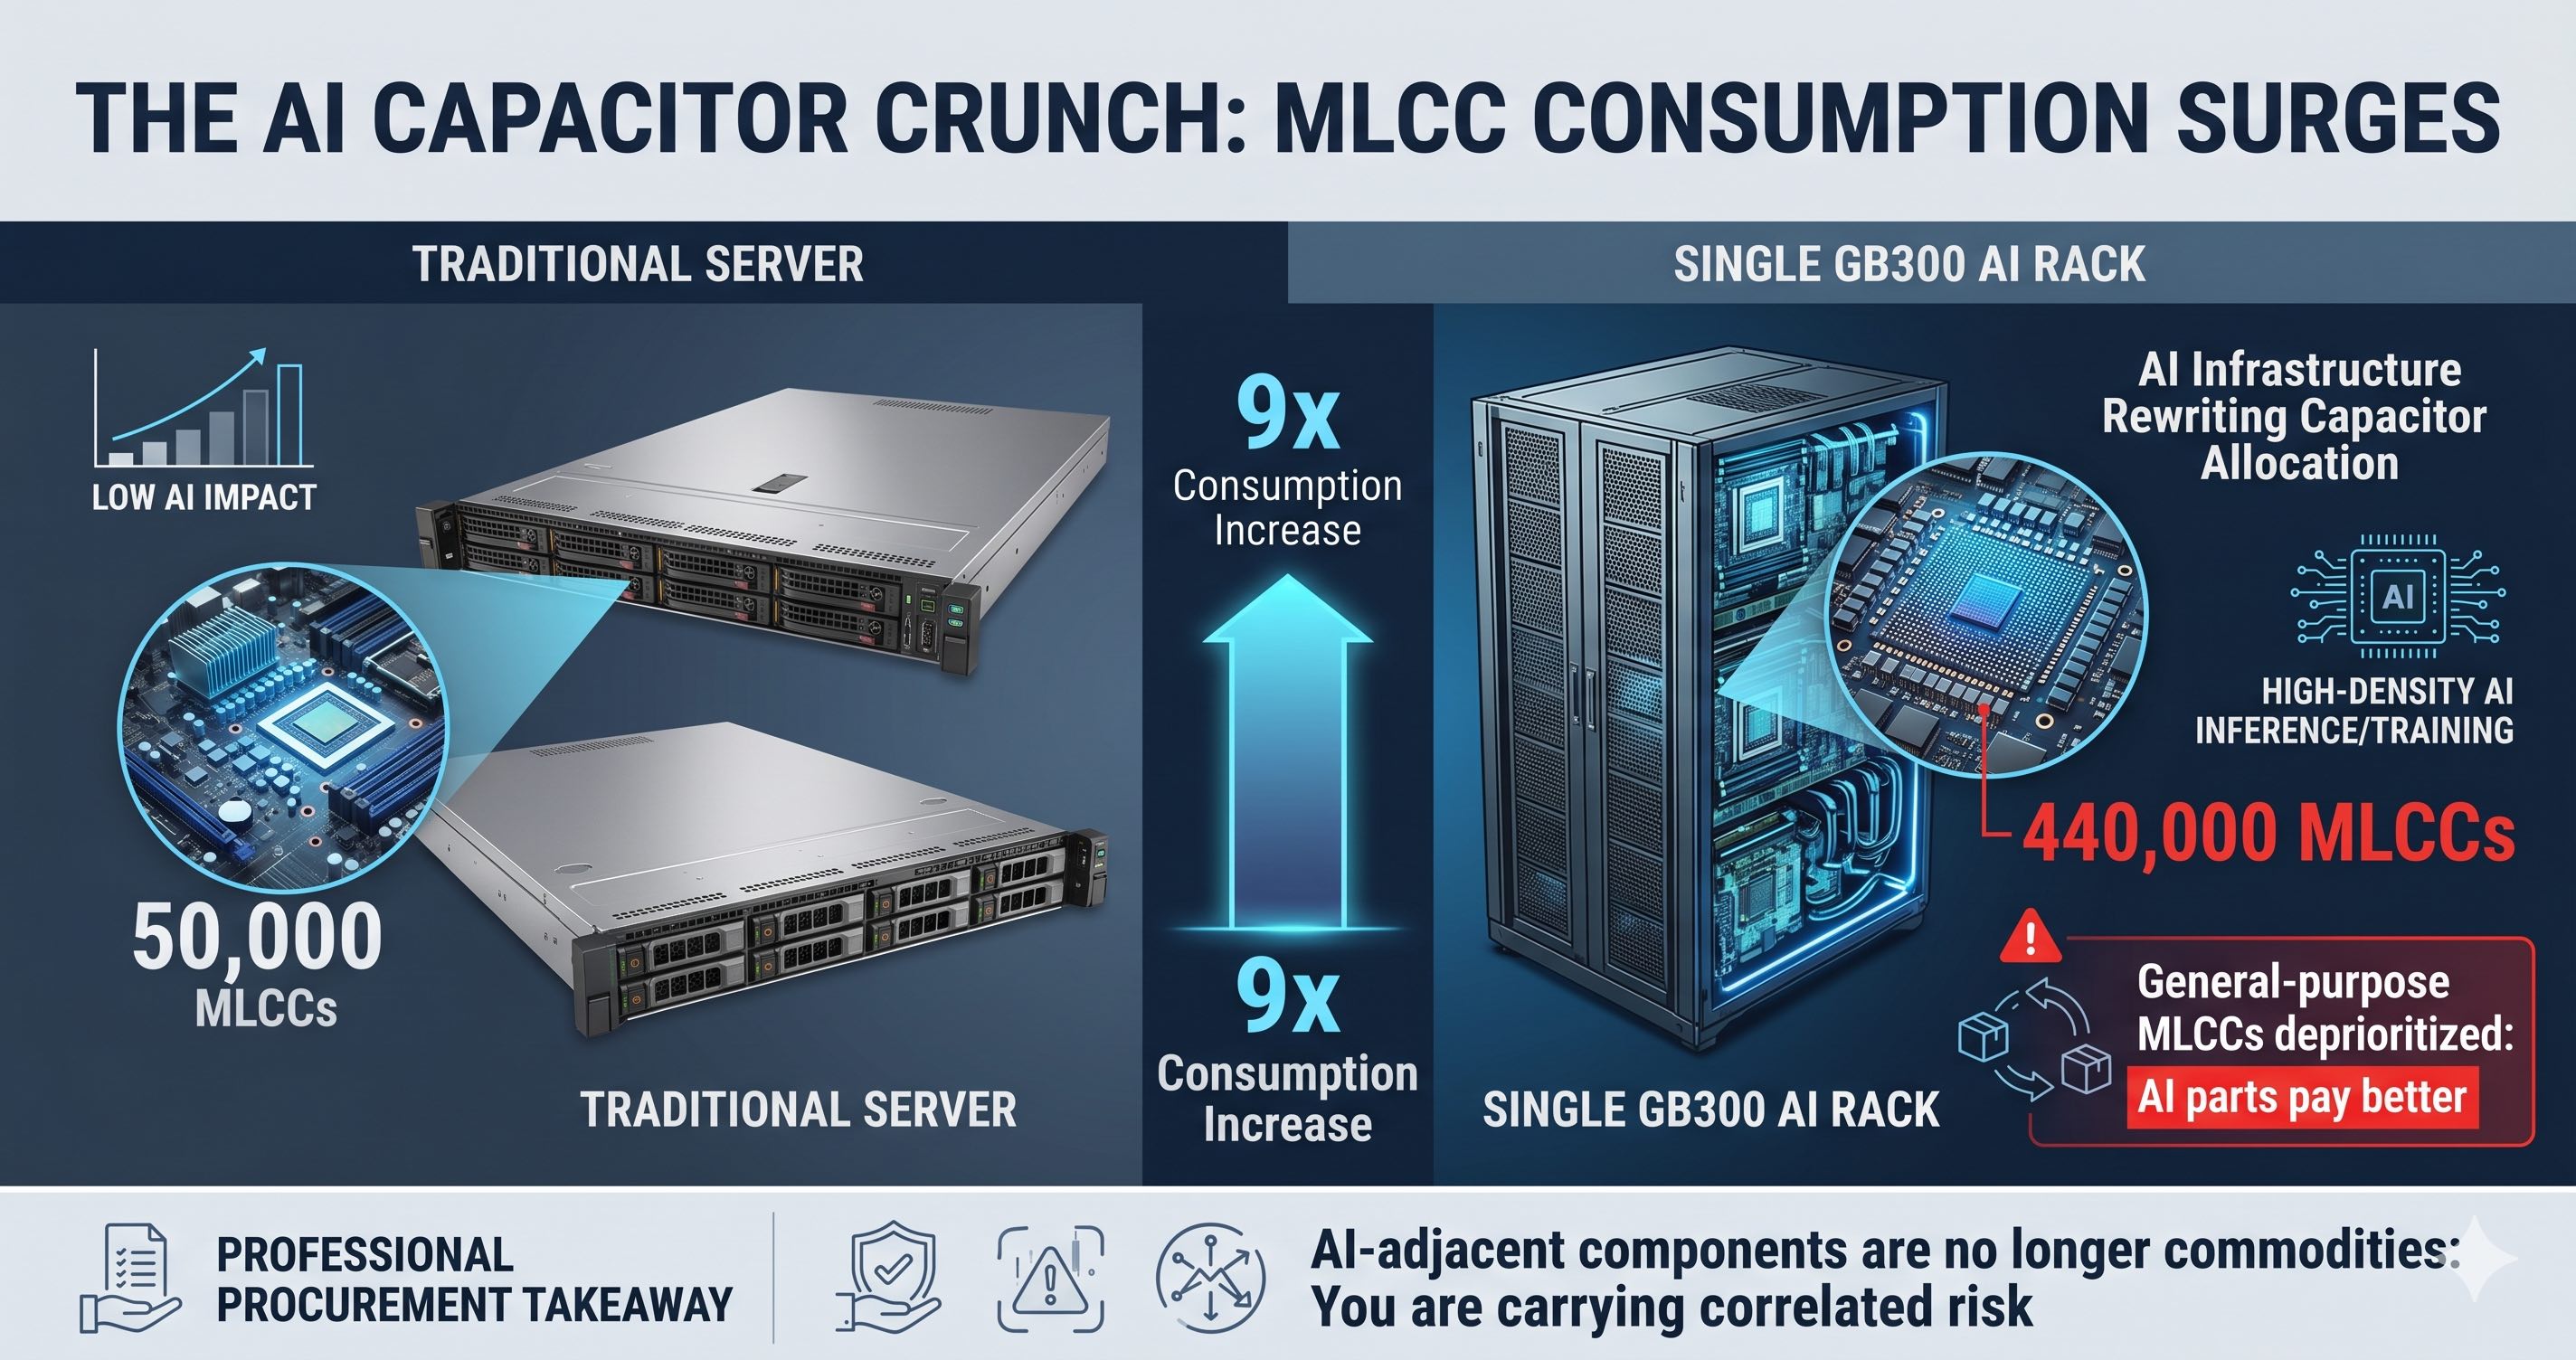
One AI Rack Now Eats 440,000 MLCCs: How the Passive Squeeze Is Pushing General-Purpose Capacitors Into the Spot and Secondary Channel

June 12, 2026

One AI Rack Now Eats 440,000 MLCCs: How the Passive Squeeze Is Pushing General-Purpose Capacitors Into the Spot and Secondary Channel

A single GB300 rack consumes nearly 9x the MLCCs of a traditional server, and the Big Three are routing capacity to high-margin AI parts. The real story isn't the price hike — it's general-purpose and industrial MLCC allocation getting crowded out, with orders spilling into the secondary and spot channel. Here's what's loosening, what's tightening, and what to stock.

marketai-demandprocurement2026-q2
Read more →
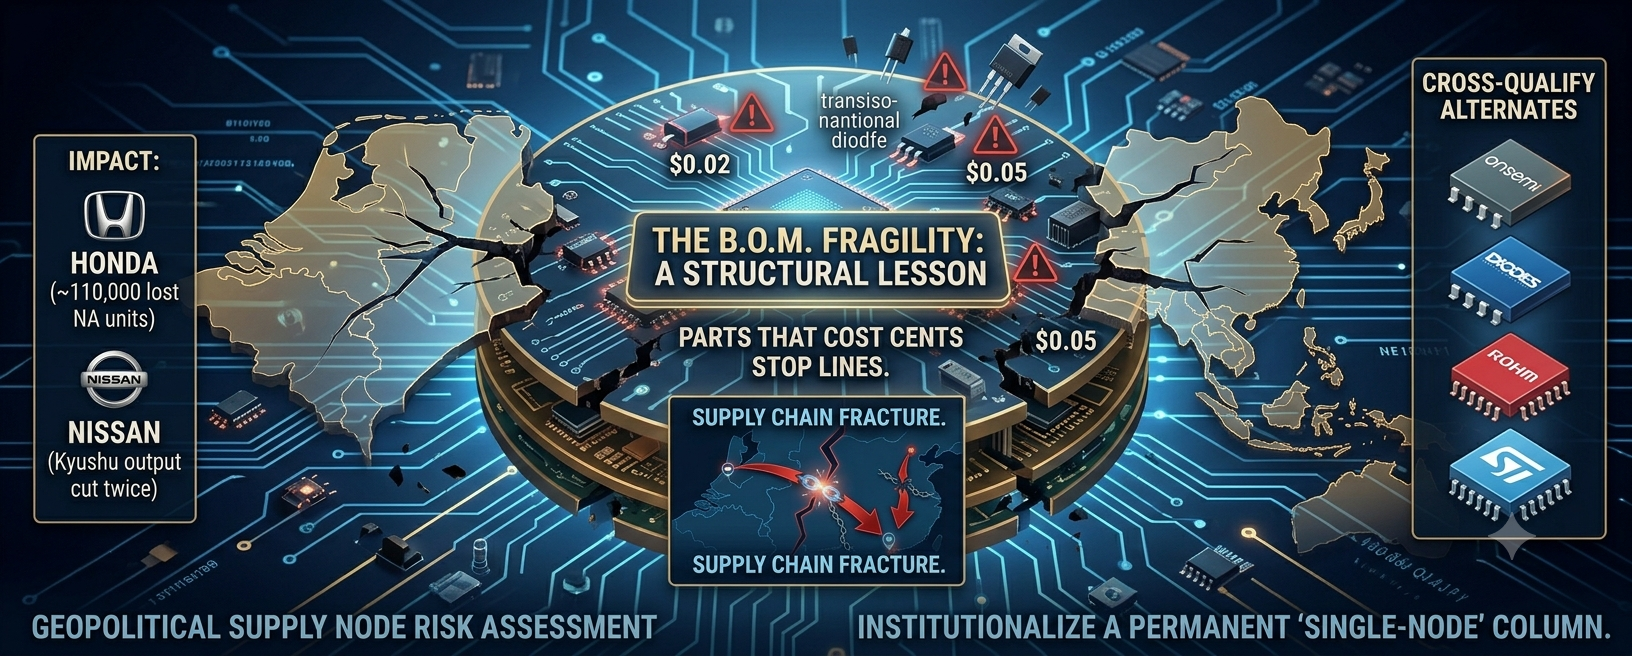
Nexperia Discretes Are Still Stuck: How the Dongguan Export Halt Hits Your Industrial and Automotive BOMs — and What to Pull Now

June 10, 2026

Nexperia Discretes Are Still Stuck: How the Dongguan Export Halt Hits Your Industrial and Automotive BOMs — and What to Pull Now

The Nexperia disruption that started in late September 2025 still isn't resolved. Export out of the Dongguan back-end plant is jammed, and some legacy parts won't see new material until July 2026 or later. This isn't a slow price story you can absorb — it's cheap diodes, MOSFETs, and logic gates that stop a line when a single one goes missing. Here's a working checklist for spot buyers and industrial procurement.

supply-riskprocurementsupply-chain2026-q2
Read more →
SLC and MLC NAND Just Became Endangered Parts: A Practical Sourcing Playbook for the Low-Density eMMC Squeeze

June 5, 2026

SLC and MLC NAND Just Became Endangered Parts: A Practical Sourcing Playbook for the Low-Density eMMC Squeeze

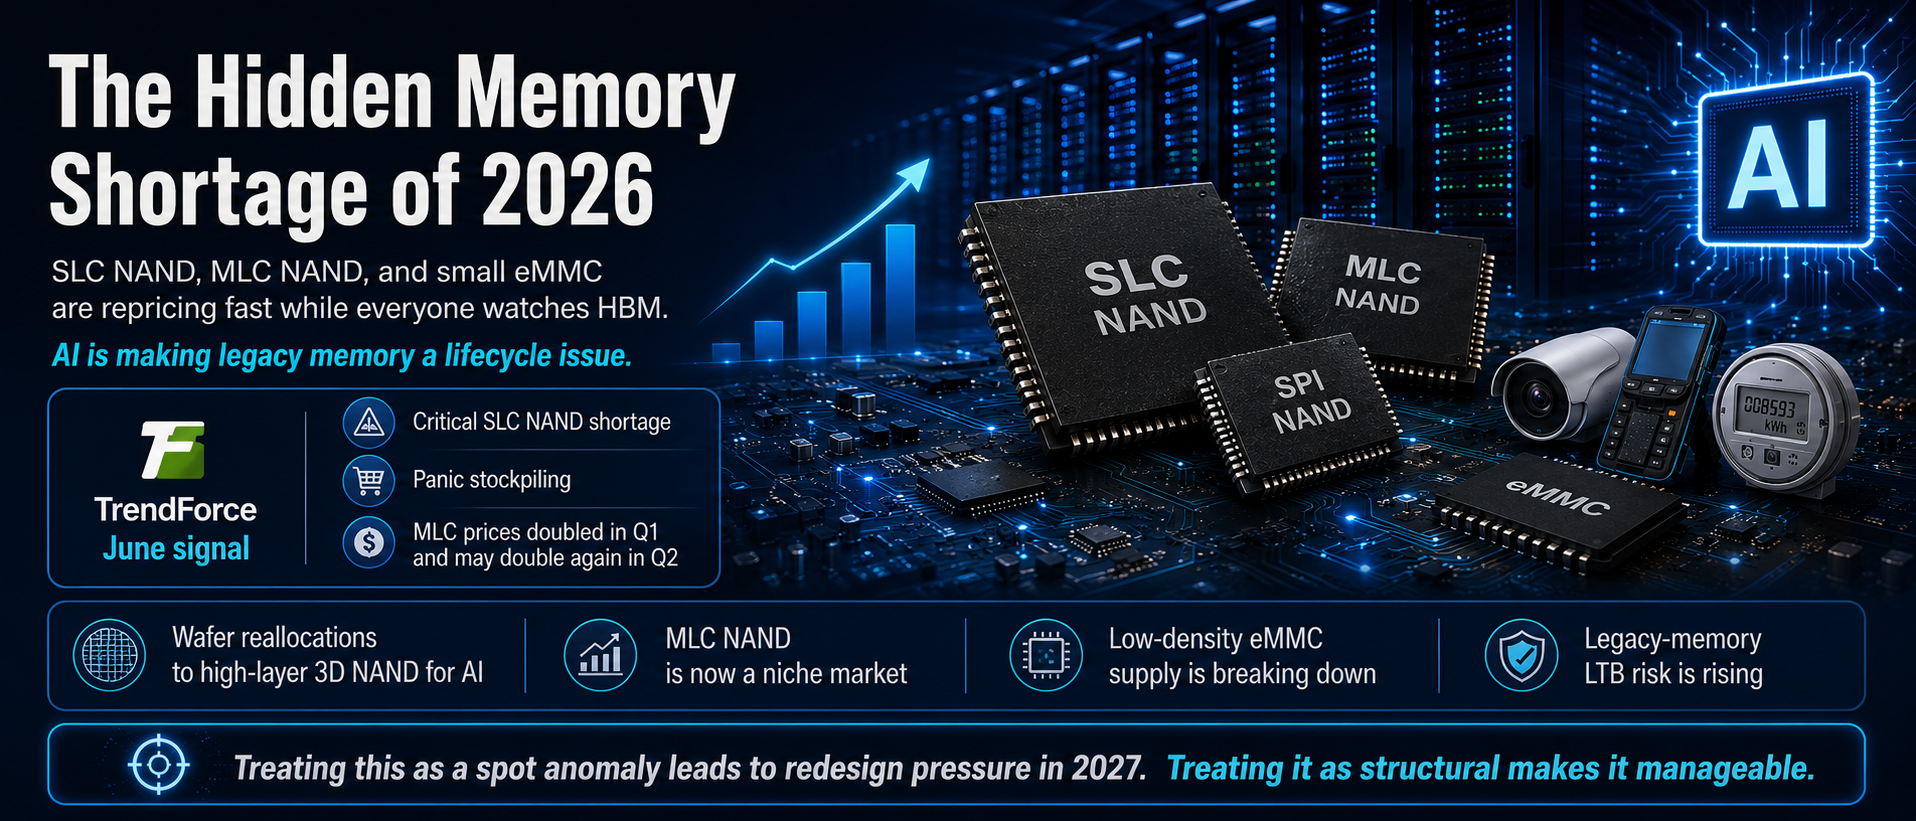
TrendForce's June data shows a critical SLC NAND shortage triggering panic stockpiling, while MLC contract prices doubled in Q1 2026 and may double again in Q2. The trigger: low-density eMMC supply disruptions as major fabs abandon legacy nodes for AI-grade 3D NAND. Here is a step-by-step playbook for industrial and automotive buyers.

memoryeMMCindustrialsupply-risk
Read more →
China Tightens Its Grip on SiC: $500 Substrates, the 8-Inch Transition, and What 800V AI Data Centers Mean for Power Sourcing

June 5, 2026

China Tightens Its Grip on SiC: $500 Substrates, the 8-Inch Transition, and What 800V AI Data Centers Mean for Power Sourcing

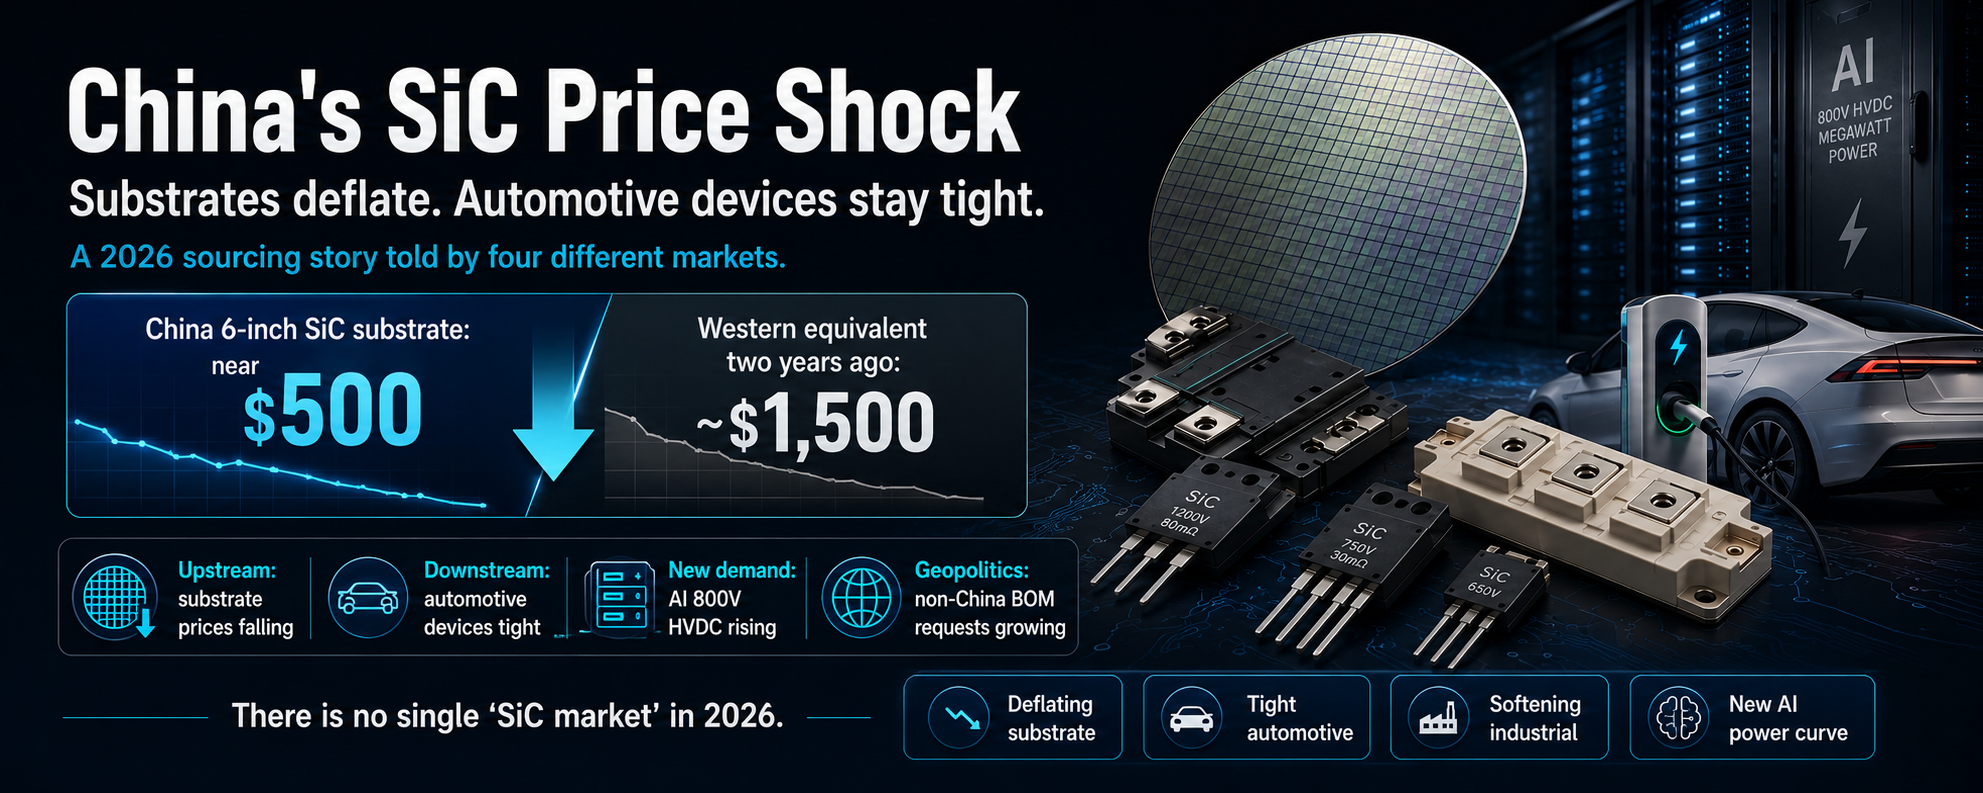
DigiTimes reported on June 4 that China is consolidating control over the SiC supply chain just as the industry shifts to 8-inch wafers. Substrate prices have crashed to around $500 a piece while automotive-grade SiC MOSFETs stay tight, and 800V HVDC AI data centers are opening a second demand lane. Here is what the split market means for buyers and brokers.

marketai-demandsupply-risksupply-chain
Read more →
The Price Wave Just Moved From Memory to Power: Infineon's July 1 Second Hike and What Spot Buyers Should Do Now

June 3, 2026

The Price Wave Just Moved From Memory to Power: Infineon's July 1 Second Hike and What Spot Buyers Should Do Now

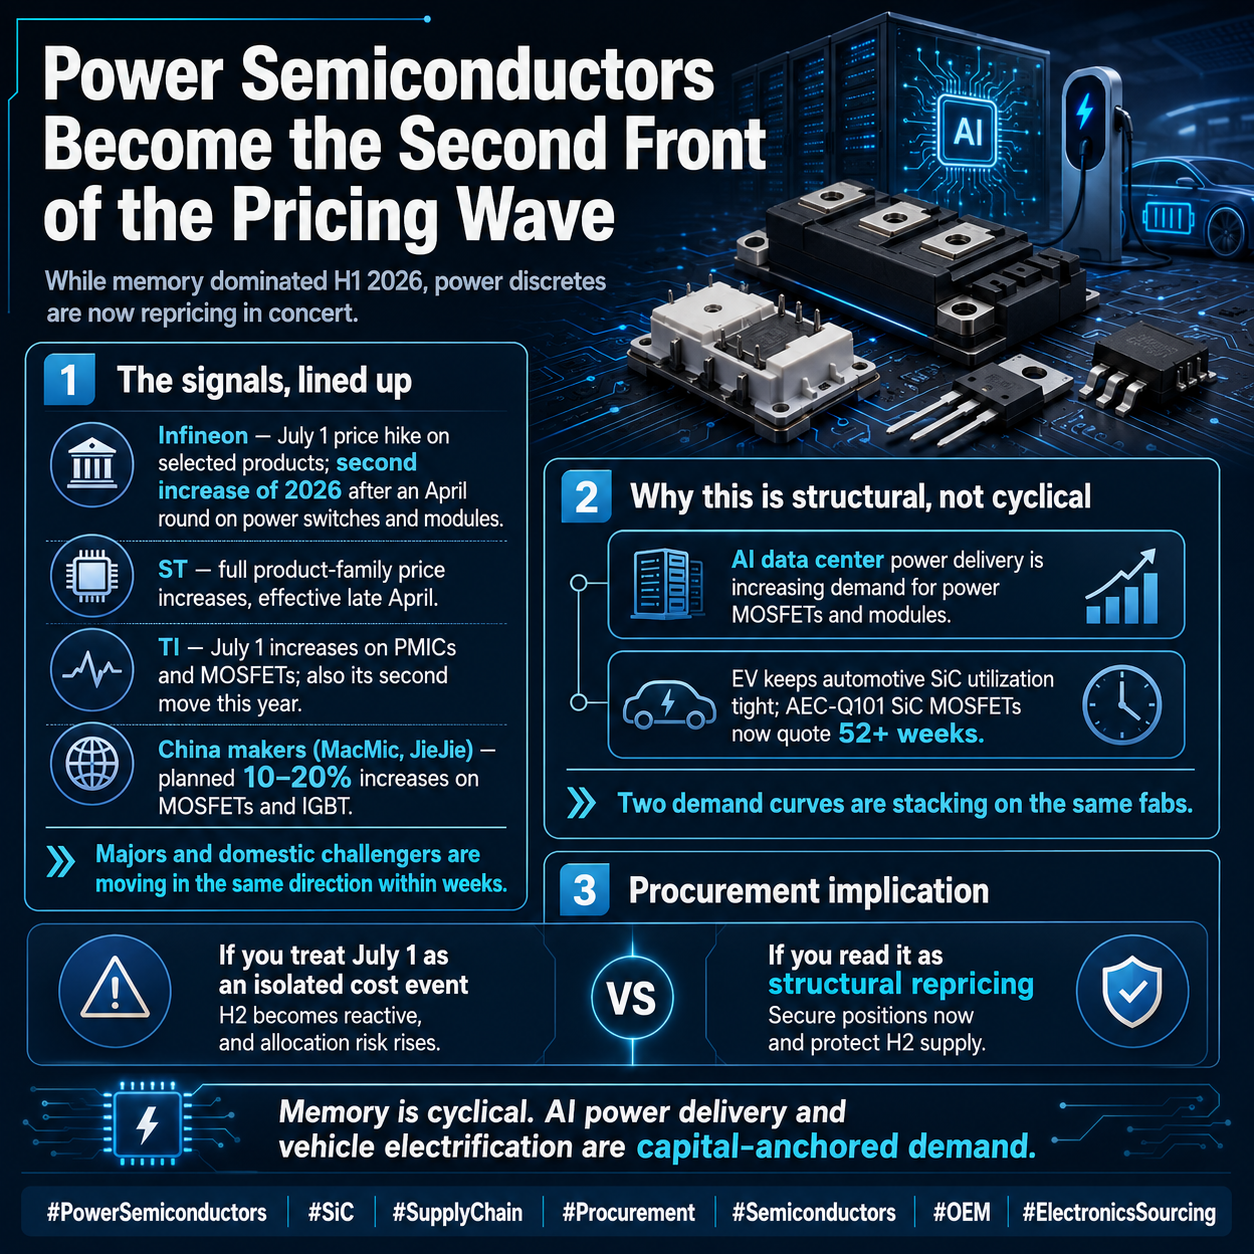
Everyone spent H1 chasing DRAM, NAND, and HBM allocation. Power semiconductors got ignored. But Infineon's May 26 notice of a July 1 second hike, ST's full-line repricing, and Chinese MOSFET/IGBT makers raising 10-20% turn power into the second front of the 2026 pricing wave. Here's the breakdown for spot buyers: what moves first, where the window opens, how to source.

marketai-demandprocurement2026-q2
Read more →
Samsung Ships First HBM4E Samples — Why the 2027 AI Memory Allocation Game Just Moved to Q2 2026

June 1, 2026

Samsung Ships First HBM4E Samples — Why the 2027 AI Memory Allocation Game Just Moved to Q2 2026

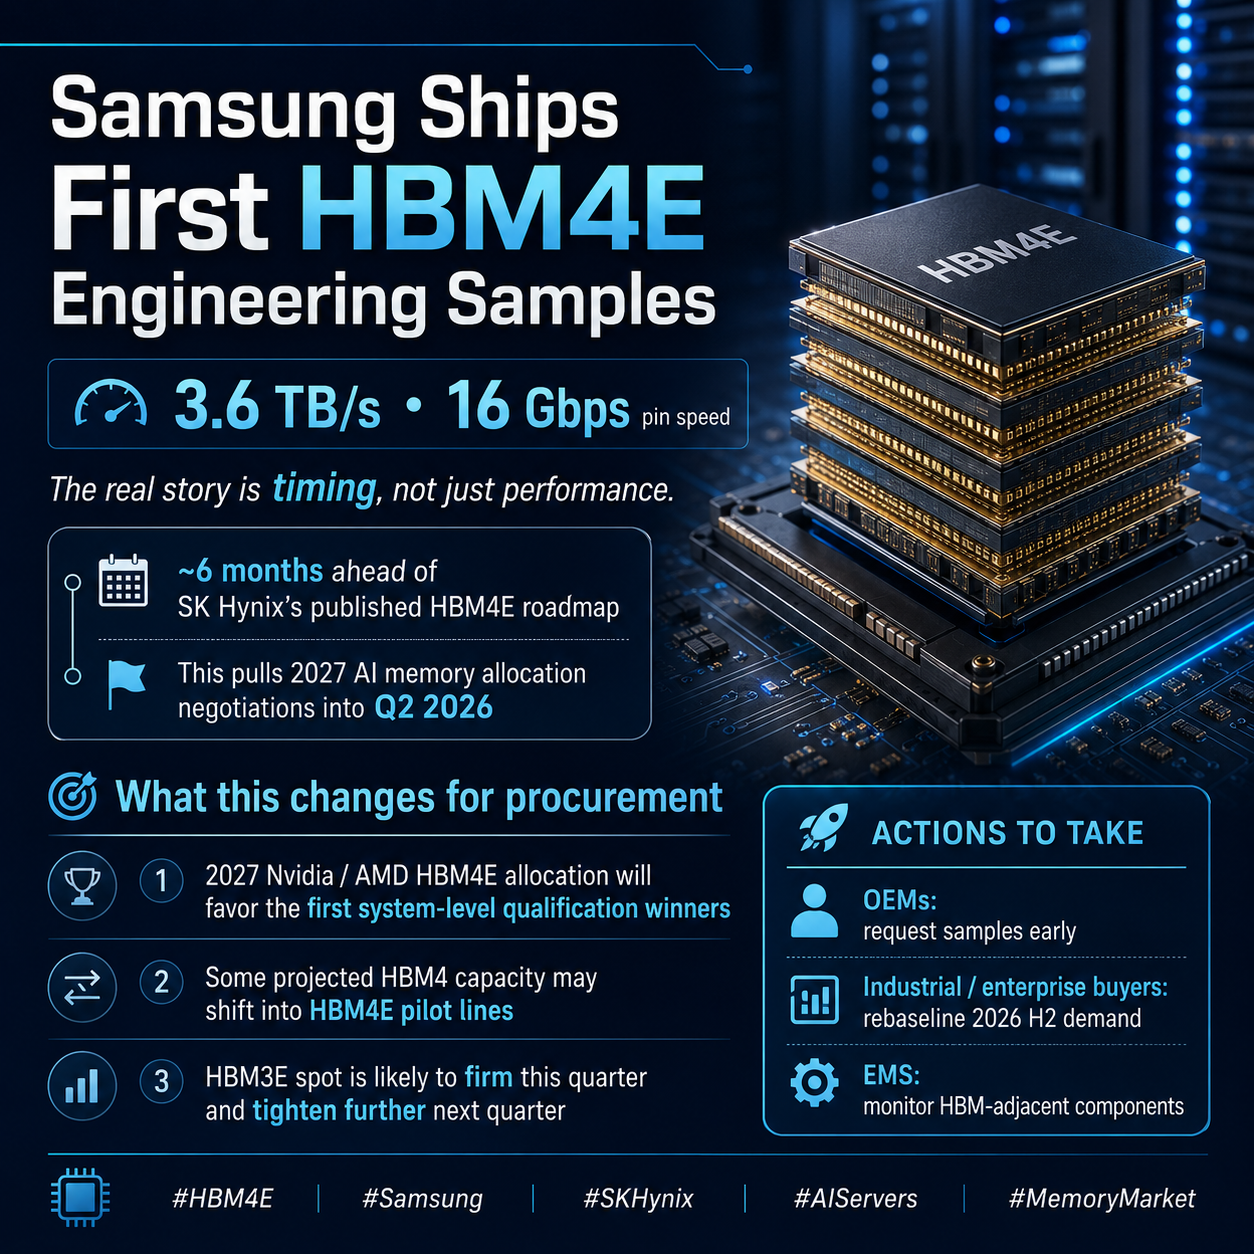
On May 30, Samsung delivered industry-first HBM4E engineering samples at 3.6 TB/s — roughly six months ahead of SK Hynix's published HBM4E roadmap. Surface read: a performance milestone. Real read: the 2027 AI server memory allocation game just got pulled into Q2 2026. Here is what AI server buyers and HBM3E spot brokers should do this month.

memoryai-demandsamsungsupply-chain
Read more →
Kioxia Sells Out 2026 NAND While 332-Layer QLC and 122TB / 245TB SSDs Push Nearline HDDs Out of AI Inference Stacks

May 29, 2026

Kioxia Sells Out 2026 NAND While 332-Layer QLC and 122TB / 245TB SSDs Push Nearline HDDs Out of AI Inference Stacks

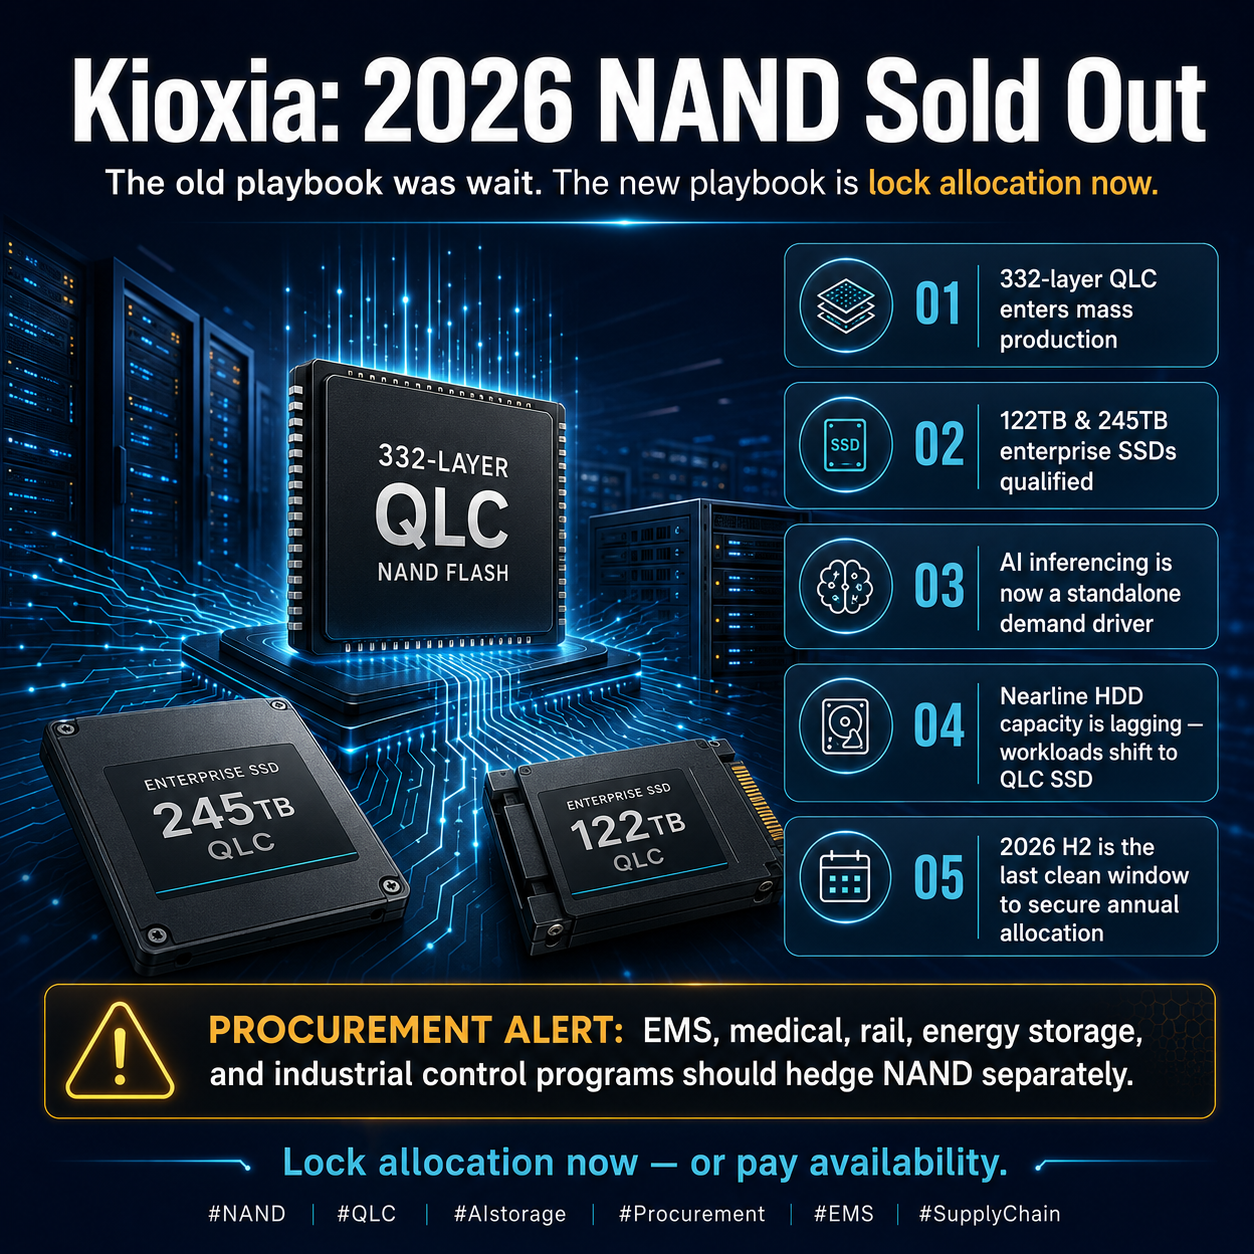
Kioxia management has stated outright that calendar 2026 NAND production is already sold out, with tightness running into 2027. The 332-layer QLC node is moving into mass production, 122TB and 245TB enterprise SSDs have cleared customer qualification, and AI inferencing plus nearline-HDD displacement are quietly becoming the second leg of NAND demand.

memoryai-demandsupply-risksupply-chain
Read more →
MLCC Lead Times Stretch to 40 Weeks as AI Server Boards Drain High-Capacitance Stock — The Next Front for Spot Buyers

May 28, 2026

MLCC Lead Times Stretch to 40 Weeks as AI Server Boards Drain High-Capacitance Stock — The Next Front for Spot Buyers

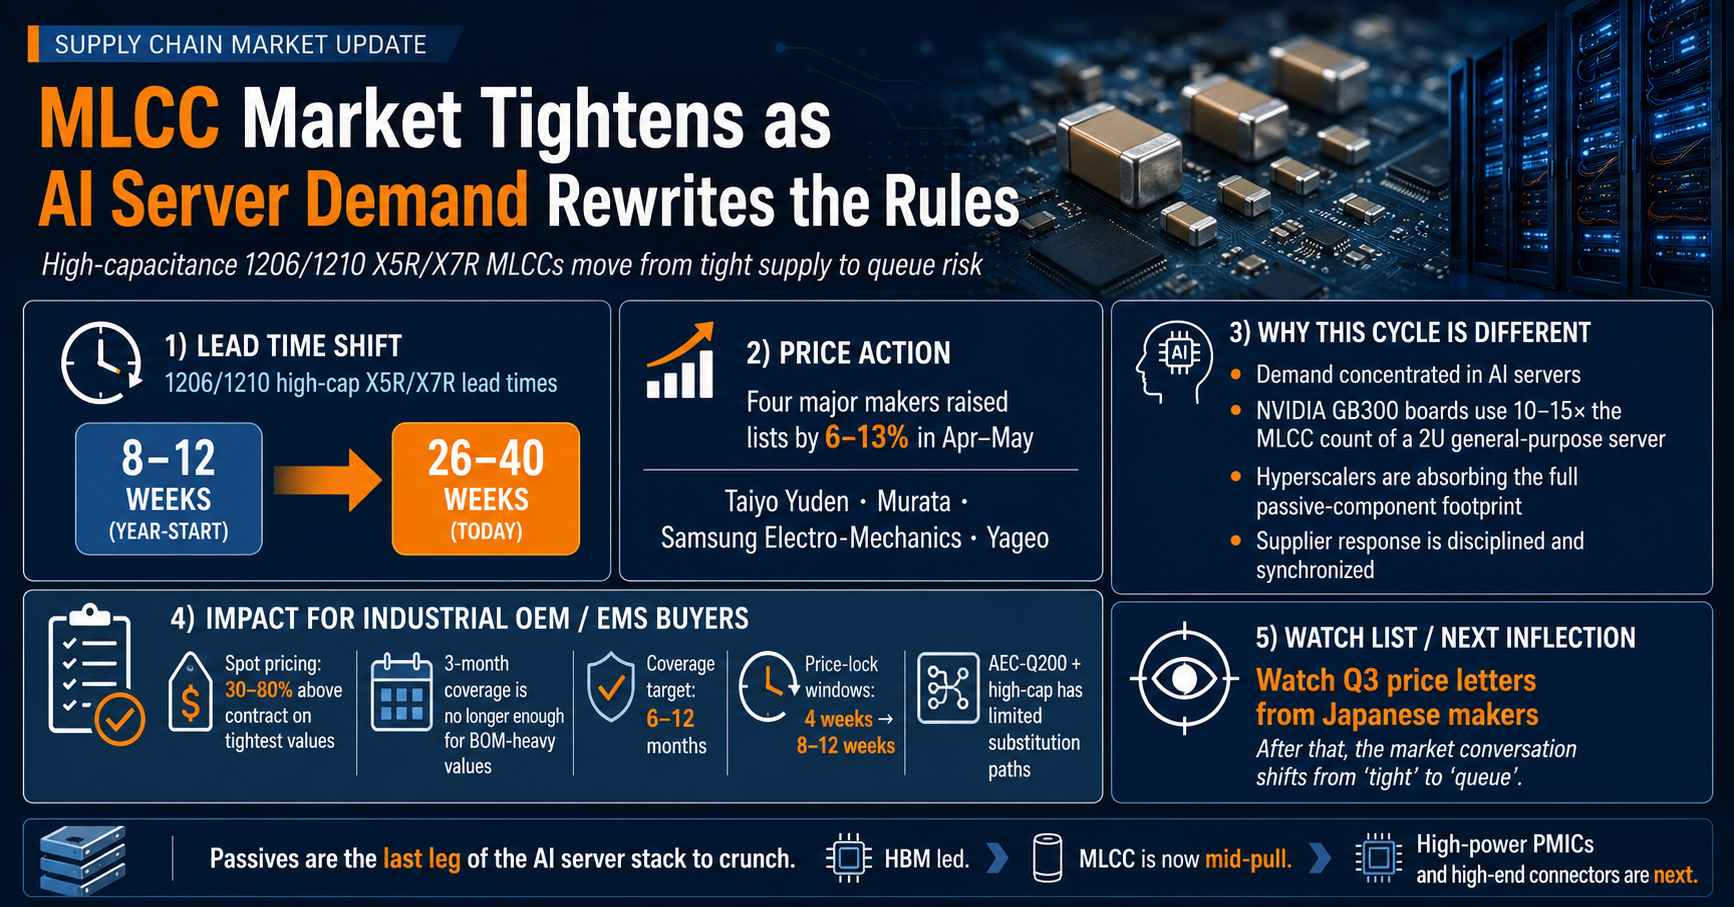
Taiyo Yuden, Murata, Samsung Electro-Mechanics, and Yageo all rolled 6-13% price hikes between April and May. 1206/1210 X5R/X7R high-capacitance lead times jumped from 8-12 weeks at year-start to 26-40 weeks. AI server boards burn 10-15x the MLCC count of general-purpose servers. Here's what spot, EMS, and industrial buyers need to do this quarter.

marketprocurementsupply-chainai-demand
Read more →
Samsung Lifts DDR5 Contract Prices Up to 60% as 2026 Memory Allocation Is Sold Out

May 27, 2026

Samsung Lifts DDR5 Contract Prices Up to 60% as 2026 Memory Allocation Is Sold Out

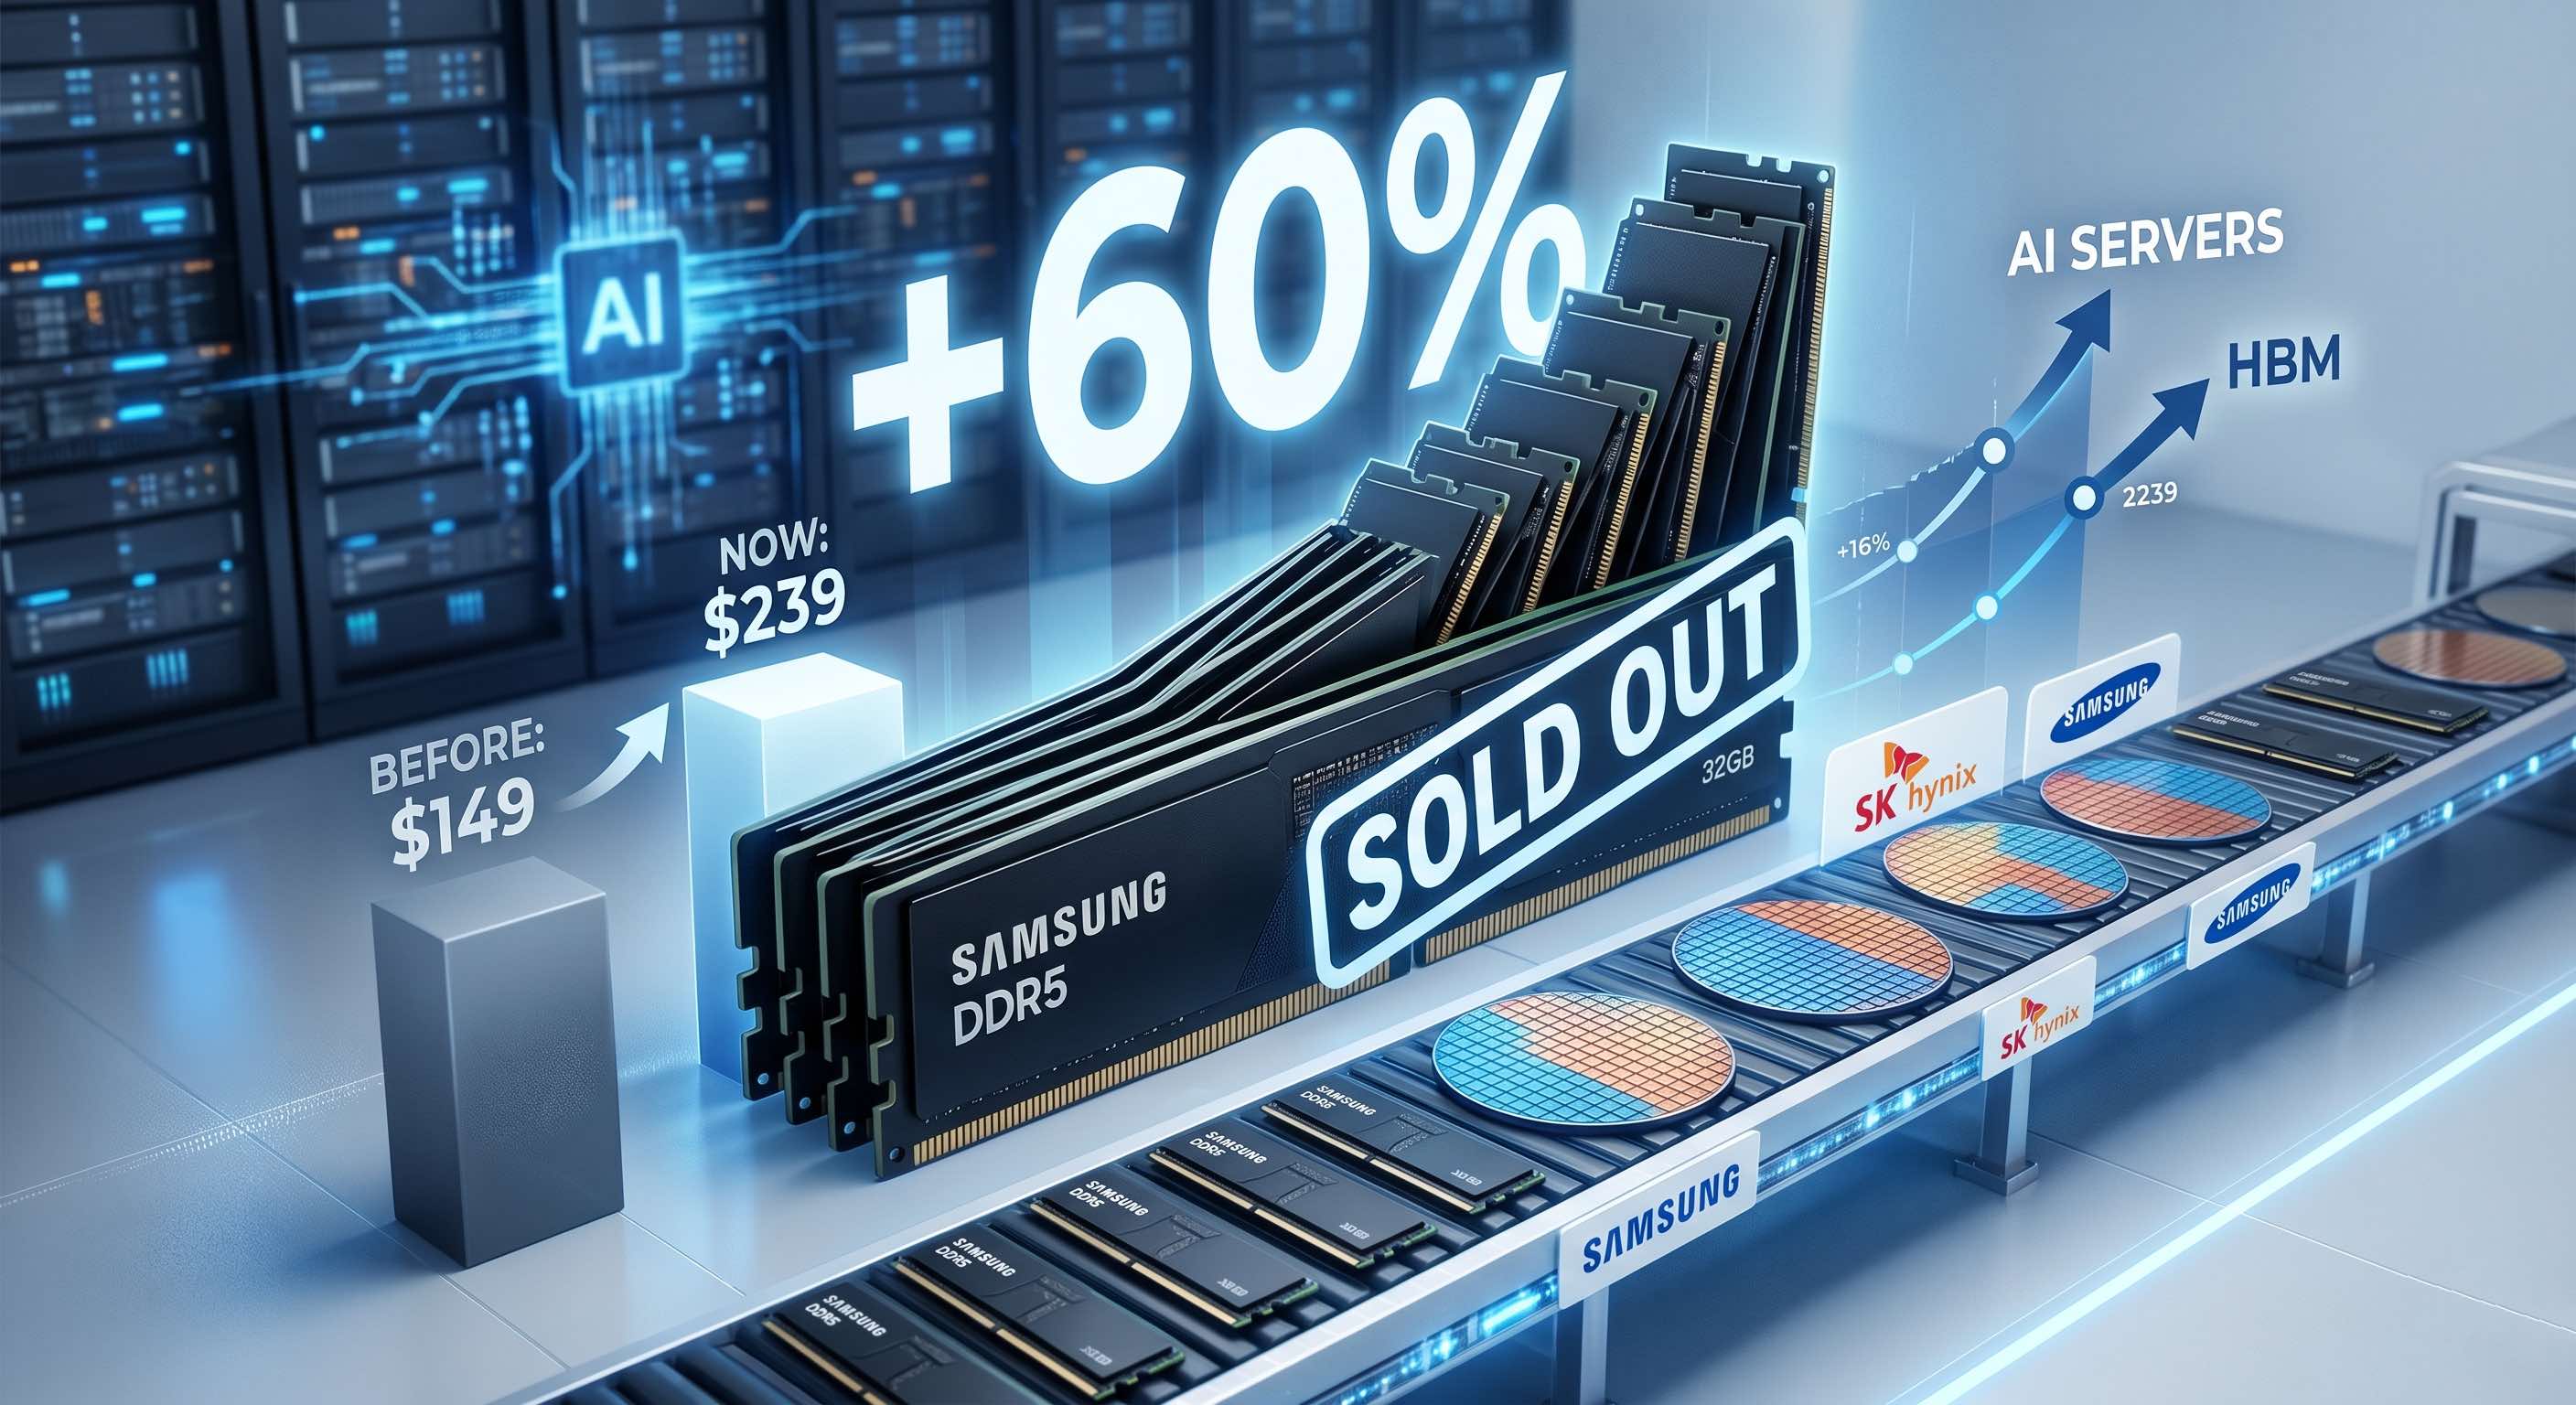
Samsung pushed 32GB DDR5 contract pricing from $149 to $239 — a near-60% jump in two months. SK hynix has publicly admitted its 2026 HBM, DRAM and NAND capacity is essentially sold out. AI servers are draining wafer capacity straight out of DDR5, LPDDR and NAND. For EMS, ODM and factory buyers, BOM memory cost needs to be repriced every month for the next 18 months.

marketmemoryai-demandprocurement
Read more →
TI on July 1, NXP on June 1 — the same-year second price wave is here, and the industrial / automotive MCU window for brokers is opening, not closing

May 26, 2026

TI on July 1, NXP on June 1 — the same-year second price wave is here, and the industrial / automotive MCU window for brokers is opening, not closing

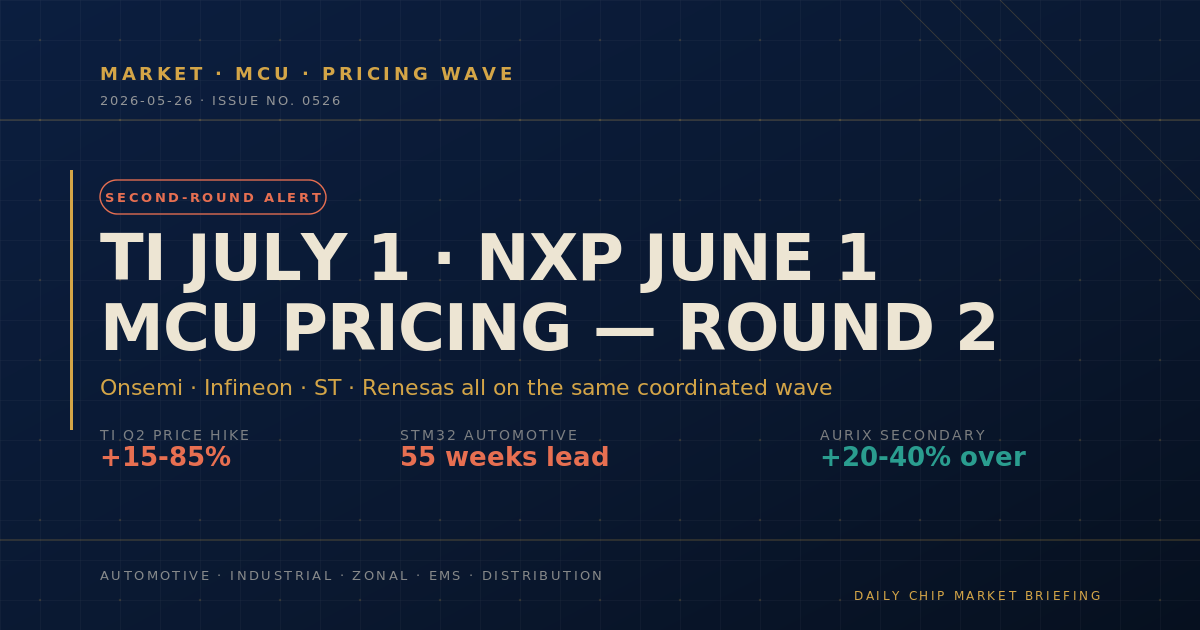
TI fired the second round of 2026 price hikes for July 1. NXP follows on June 1. Onsemi already raised on April 1. Infineon's April 1 increase is now six weeks in. Layer on STM32 TSX at 55 weeks and Renesas auto-grade at 20-45 weeks, and the OEM question is no longer how much it will cost but whether one last order can land before the next reset. Here is how brokers should be reading and pricing this.

marketprocurement2026-q2industrial
Read more →
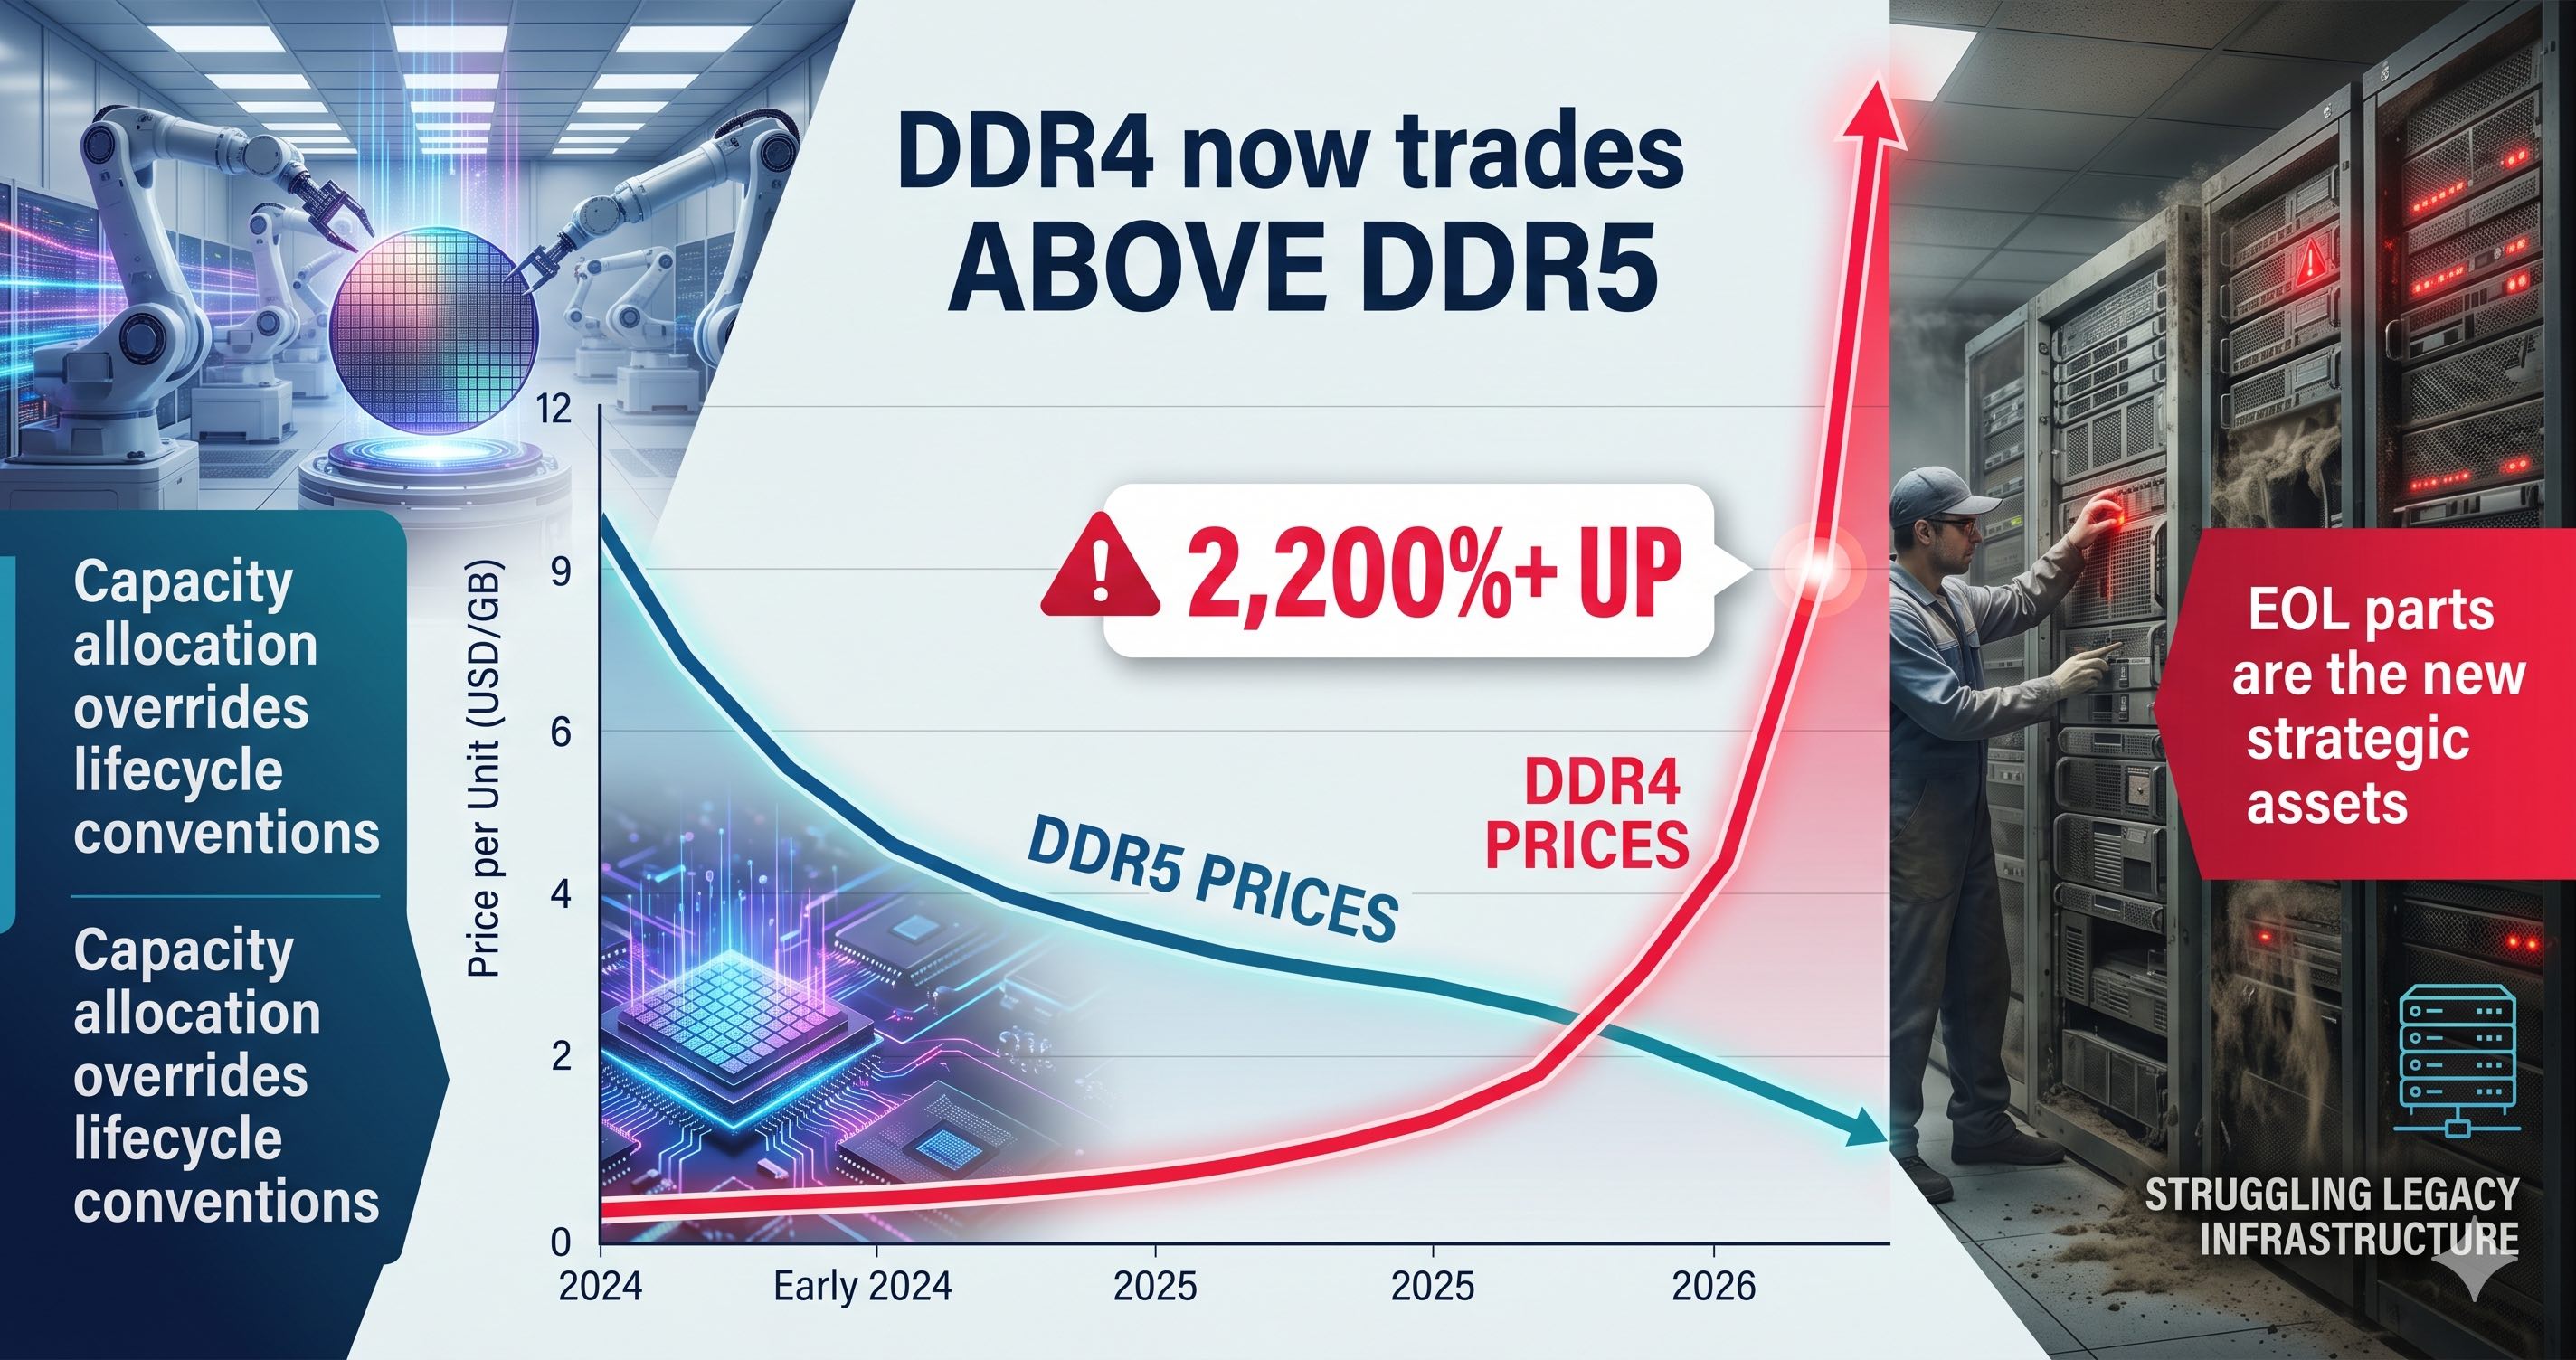
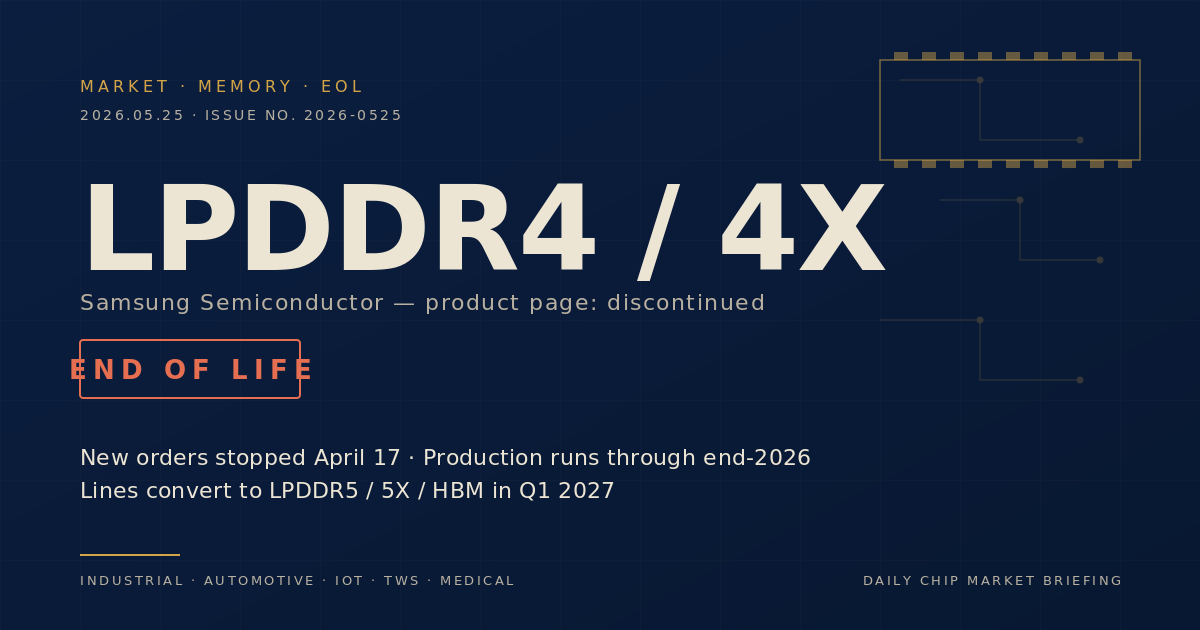
Samsung Pulls the Plug on LPDDR4 / LPDDR4X: Three Things Industrial and Automotive Procurement Teams Need to Do This Quarter

May 25, 2026

Samsung Pulls the Plug on LPDDR4 / LPDDR4X: Three Things Industrial and Automotive Procurement Teams Need to Do This Quarter

Samsung's product pages now show LPDDR4 and LPDDR4X as discontinued. No new orders since April 17, production until end-2026, lines convert to LPDDR5 and HBM in Q1 2027. Phones are not the real story. Industrial, automotive infotainment, TWS and IoT — anything with a 5-to-15-year lifecycle — is where this hurts. Three actions to take this quarter.

memoryLPDDR4samsungsupply-risk
Read more →